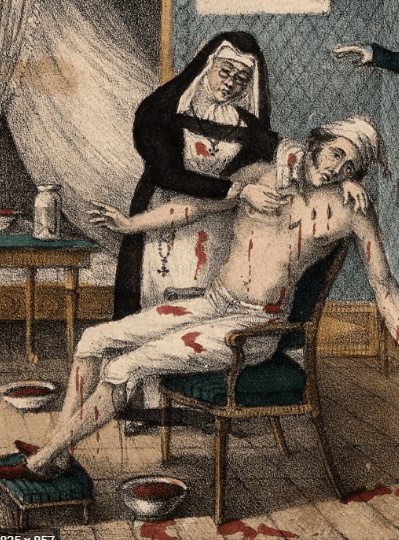Why is inflation so hard to defeat?

I come from Chicago, and so am, by DNA, a Bears fan.

We Bears fans often ask, “Given that they repeatedly have high draft choices, why are their teams so bad, year after year?” (Cleveland Browns fans can empathize.)

The answer can be stated in two words: Bad leadership. And that also answers the title question, “Why is inflation so hard to defeat?” Bad leadership.

Here are quotes from the Committee for a Responsible Federal Budget (CRFB), which usually parrots the propaganda of the very rich:

Inflation is currently surging at the fastest rate in more than four decades, with the Consumer Price Index (CPI) up 8.2 percent over the past year and Personal Consumption Expenditure (PCE) price index up 6.2.

By comparison, the Federal Reserve (“the Fed”) generally targets 2 percent annual PCE inflation.

In general, the federal government has two types of tools available to fight inflation. Monetary policy, conducted by the Federal Reserve, can raise interest rates.

Or fiscal policy, controlled by the Congress and President, can adjust taxes and spending.

Immediately, they limit possible tools to those that impact the “not-rich” and widen the Gap between the rich and the rest. It’s known as “Gap Psychology,” the human desire to widen the income/wealth/power Gap below you and to narrow it above you.

“Raise Interest Rates” Impacts homebuyers who seek mortgages.

Adjust Taxes: “Adjust” is a disingenuous word for “raise.” When taxes are raised, the rule always includes exceptions and loopholes for the rich, not for the rest of us.

Adjust Spending: Here, “adjust” means “cut.” Deceptively, the CRFB uses one word to mean two opposite things.

When federal spending is cut, benefits to the middle and the poor always suffer. The false “need” to cut spending will be reflected in the Big Lie in economics that Social Security and Medicare are “running short of dollars” and that all aids to the poor, students, renters, etc., are “unaffordable.” Utter nonsense.

Specifically, Congress and the President can use their tools to assist the Federal Reserve in its efforts to fight inflation. Using fiscal policy in this situation can:

  • Ensure all federal actions are rowing in the same direction;
  • Reduce recessionary pressures and support stronger economic growth;
  • Diversify and limit the economic pain from inflation-reducing actions; and
  • Reduce the budgetary cost of fighting inflation.

The CRFB wants everyone to “row in the same direction.” Lovely words. But it also wants to “support stronger economic growth” and “limit economic pain” while raising taxes and cutting spending.
What the CRFB means by “rowing in the same direction.”

It is impossible to support economic growth and limit economic pain while raising federal taxes and cutting federal spending. Absolutely, 100% impossible.

Federal Reserve in fighting inflation. Through deficit-reducing tax and spending changes, they can help temper demand, boost supply, and directly or indirectly lower prices in the economy.

Translation of the above sentence: “By taking dollars out of the economy, they can take dollars from consumers, reduce supply, and drive the economy into a recession.

Congress and the President should act soon to pass legislation that helps fight inflation on all of these fronts.  

Key to any legislation will be deficit reduction, which 55 of the nation’s top economists and budget experts recently explained is one tool in helping to ease inflationary pressures.

Translation: “55 of the nation’s top economists say to ease inflation, we must plunge the economy into a recession. (And never mind about stagflation, which we have no idea how to fight.) This is known as “austerity,” which was attempted in the euro nations. [From the Harvard Business Review, September 28, 2018]:

Eurozone governments – especially those in struggling Southern European countries (Spain, Greece, or Portugal) – switched dramatically towards austerity in the years 2010-2014.  

Most experts now agree that these policies had such damaging and persistent negative effects on growth that they were self-defeating.

Governments were reducing spending in order to bring their debt levels under control. But GDP fell so much that . . . debt became even less sustainable than before the austerity measures were implemented.

Consider that euro nations are monetarily non-sovereign, like you and me. Their debt is like my debt and yours. We are not Monetarily Sovereign, so we don’t have the unlimited ability to create dollars.

They had to cut debt because the Monetarily Sovereign EU wouldn’t support them. The Monetarily Sovereign U.S. doesn’t and shouldn’t cut “debt” (which isn’t real debt) or deficits, and there is no reason for the U.S. to undergo the horrors of austerity.

But that is exactly what the “55 top economists” recommend.

At a minimum, Congress and the President should stop adding to the deficits, so that fiscal policy is not worsening inflation.

Translation: “At a minimum, Congress and the President should stop adding dollars to the private sector so that a recession is assured.”

In addition to helping contain inflation, thoughtful deficit reduction can also help to grow the economy, reduce geopolitical risks, improve fairness and efficiency of the budget and tax code, and put the national debt on a more sustainable path.

Translation: “In addition to helping cause a recession, mindless deficit reduction can also help to shrink the economy, exacerbate geopolitical risks, have no effect on the fairness and efficiency of the budget and tax code, and put the nation on a path to a recession or depression.

When federal debt growth (green line) shrinks, we have recessions (vertical gray bars), which are cured by federal debt growth increases.

Inflation in the United States has been elevated for 22 months and shows few signs of abating.

High inflation originated from a mismatch between total demand and supply in the economy – largely as a result of constraints from the COVID-19 pandemic and an aggressive fiscal and monetary policy response. 

Translation: Inflation has been growing because COVID caused reductions in the supply of oil, food, computer chips, shipping, labor, and other goods and services. The resultant scarcities caused prices to rise.

The Federal Reserve has already begun to act, raising interest rates by three percentage points since March of 2022, beginning to shrink its balance sheet, and signaling further tightening – with rates headed toward 4.6 percent by the end of 2023 – until inflation is brought under control.

Translation: The Federal Reserve’s massive interest rate increases have done nothing to increase the supplies of oil, food, etc., so they have done nothing to cure inflation.

Economists believe that monetary policy should play the lead role in stabilizing the economy because of the Federal Reserve’s ability to act quickly and effectively to adjust interest rates, using its technical expertise and political insulation to balance competing priorities.

In this case, the Fed can expeditiously and gradually raise interest rates and shrink its balance sheet – based on real-time data – to encourage savings, discourage large purchases, and reduce wealth-driven consumption.

And as we can see, the Fed’s expeditious and gradual interest rate raise has cured inflation. Oh, it hasn’t because it does nothing to remedy shortages?

Would someone please tell the CRFB and the 55 top economists? And by the way, “Encourage savings, discourage large purchases, and reduce wealth-driven consumption” describes a recession.

Yet even as the Fed is better equipped to bring down inflation, doing so is not without its challenges.

Higher interest rates put upward pressure on the unemployment rate and can also lead to financial instability – especially when rates are increased well above the long-term neutral rate (believed to be 2.5 to 3.0 percent).

Indeed, some recent research suggests the inverse relationship between inflation and unemployment described under the Phillips curve might be particularly strong now, suggesting a high “sacrifice ratio” whereby reductions in inflation require large increases in unemployment.

The CRFB has it all backward. High prices don’t cause unemployment. Unemployment occurs because shortages of goods and services discourage hiring. You don’t hire more people when you can’t produce, ship, or service.

In acting alone to fight inflation, there is a substantial risk and perhaps likelihood the Fed’s actions will spur an economic recession.

Finally, one factual statement from the CRFB. More than a “substantial risk. It borders on certainty.

The Federal Reserve has only a limited set of tools to fight inflation, which work by boosting interest rates.

While generally effective in reducing inflation, higher interest rates can also impose substantial pain on the housing and labor markets, reduce investments that promote long-term growth, and take a long time to affect the economy.

Translation: Replace the word “effective” with “ineffective and economically harmful.” The rest of the sentence is correct.

For these and other reasons, economists and policymakers have long supported supplementing monetary policy with fiscal stimulus to fight recessions.

Elemendorf and Furman, for example, argue policymakers should sometimes use fiscal policy even though monetary policy is superior.

Fiscal stimulus (i.e., federal deficit spending) always (not “sometimes”) is necessary. It should be targeted toward reducing shortages: More federal spending to aid oil exploration and production, to aid and encourage food production, and to encourage hiring.

The first step: The FICA tax should be eliminated, a monumental and useless drag on the economy. The federal government neither needs nor even uses FICA dollars for anything. It destroys them upon receipt.

When FICA dollars are sent to the Treasury, they come from the nation’s M1 money supply measure. But when they reach the Treasury, they cease to be part of any money supply measure. They effectively are destroyed.

There is no measure for the government’s money supply because the government has infinite money.

Specifically, spending increases and tax cuts work to boost demand in the near term, while high levels of projected deficits and debt can boost inflation expectations.

One standard measure of an economy is Gross Domestic Product (GDP). It is a measure of spending. The CRFB admits that federal spending increases will increase GDP.

And what will federal spending decreases do? Right, they will decrease GDP.

“Recession” is a decline in GDP for two or more quarters, and a depression is a decline in GDP for two or more years. Unwittingly, the CRFB and the 55 top economists have admitted recommending a recession or depression as the cure for inflation.

This is especially true if markets believe the government will attempt to inflate away a portion of its debt.

The notion of the federal government inflating away its debt is nonsense on several levels.

I. The federal government’s “debt” is nothing like personal or local government debt. It’s deposits into privately owned T-security accounts, which the government pays off upon maturity simply by returning the dollars.

The government neither uses nor even touches those dollars. You, as a depositor, own them.

The government spends using dollars newly created, ad hoc. The federal government never can run short of its sovereign currency.

II. Inflation does not affect the government’s ability to return the dollars in T-security accounts. Federal interest rate increases affect the number of dollars in those accounts, but the number does not affect the government’s ability to return those dollars.

No matter how large the “debt” (that isn’t a debt), the government just returns the dollars. It’s like a safe deposit box. No matter the value, the contents belong to you, and the Bank simply returns them.

III. The CRFB’s comments demonstrate their confusion between federal (Monetarily Sovereign) debt vs. state government and personal (monetarily non–sovereign) debt.

It’s the classic case of using one word with two unrelated meanings.

Personal debt comes from borrowing, wherein the borrower needs the dollars for some use. Federal “debt” comes from the federal government’s desire to stabilize the dollar by providing a safe haven for unused dollars.

The government neither needs nor uses those dollars. It has the unlimited ability to create dollars for any purpose.

Contrary to popular myth, the U.S. federal government never borrows U.S. dollars. Same reason: It has the infinite ability to create new dollars. Additionally, those T-security accounts help the government control interest rates.

Sadly, the CRFB either doesn’t understand economics or deliberately misleads its readers on behalf of the rich. Their hope might be to discourage the “not-rich” from asking for benefits, thereby increasing the Gap and making the rich comparatively more affluent.

Enacting deficit reduction during a period of high inflation can also help to reassure markets that elected officials are committed to responsible policy and won’t attempt to undermine Federal Reserve tightening in the future should inflation persist.

What can one say about the above nonsense? Deficit reduction (aka subtracting dollars from the economy) during high inflation will assure the markets that elected officials are committed to causing a recession or a depression.

While higher interest rates help to fight inflation, they also increase the risk of a recession by weakening labor markets and threatening financial stability.High interest rates also discourage personal and business investment, which in turn slows long-term income and economic growth.

Right, CRFB, except for the false “help fight inflation” part. But what happened to the CRFB’s “row in the same direction” philosophy?

Following their warning about the risk of recession, the CRFB published many word-salad paragraphs that could be summarized thus: “We should increase deficit spending without increasing deficit spending” and do all that to “stimulate the economy without stimulating the economy.”

Got it?

Of course, they had to finish with the Big Lie in economics that the federal government’s spending is constrained by tax income. Like the Bank in a Monopoly game, the federal government doesn’t need tax dollars. It can create all the new dollars it needs.

Even if all tax collections totaled $0, the federal government could continue spending forever.

Given the risks and threats from deficits and debt, substantial deficit reduction is needed even absent high inflation.

Surging prices makes deficit reduction more necessary and urgent while dramatically reducing any macroeconomic risks associated with near-term deficit reduction.

Wha? Surging prices . . . reduce risks of near-term recession?? Where did that idea come from?
Broke Sam Stock Illustration - Download Image Now - American Culture, Bankruptcy, Cartoon - iStock
The lie they want you to believe.

It’s almost as wrong-headed as their final paragraph:

Rather than continuing to enact policies that increase deficits and worsen inflationary pressures, Congress and the President should act swiftly to enact deficit-reducing legislation that would help the Federal Reserve fight inflation today, while putting the national debt on a more sustainable path for years to come.

So there it is folks. Allowing the world to deposit dollars into T-security accounts is not sustainable because . . . well, no one knows why.

It’s just what the rich want you to believe, so you will be docile and obedient when they tell you they have to cut Social Security, Medicare, ACA, aid to students, assistance to the poor, and, oh yes, raise your taxes.

The rich become more prosperous by widening the Gap between the rich and the poor.

Why is inflation so hard to defeat? We Bear fans understand the concept perfectly. Bad leadership.  

Rodger Malcolm Mitchell

Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

The Sole Purpose of Government Is to Improve and Protect the Lives of the People.

MONETARY SOVEREIGNTY

Free Minds, Free Markets, Free Ignorance.

Reason.com - Free Minds and Free Markets This is the masthead for the online Libertarian magazine, Reason. These folks boast about having “free minds,” which one might assume means they are open to learning and not locked into a rigid belief. Sure, they are. I find it ironic that perhaps the most stone-headed political-economics group in America could claim freedom of mind. These are anarchists in thin disguise who have no idea how federal financing works, and day after day, they publish proofs of their determined ignorance. Here is just one of a seemingly endless supply of misinformation and disinformation from the “free minds.”

Rand Paul Asked Senators To Balance the Budget. Only 28 Agreed. Rising interest rates will only make it harder to balance the budget in future years. Eric Boehm  

Right off the top, we encounter ignorance. Rand Paul is a hopeless purveyor of nonsense, while Boehm and his fellow Libertarians are clueless about the differences between federal financing vs. state & local government financing, business financing, and personal financing. The federal government is the creator of the dollar, which is why knowledgeable people say things like this:

Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency.”

Ben Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”

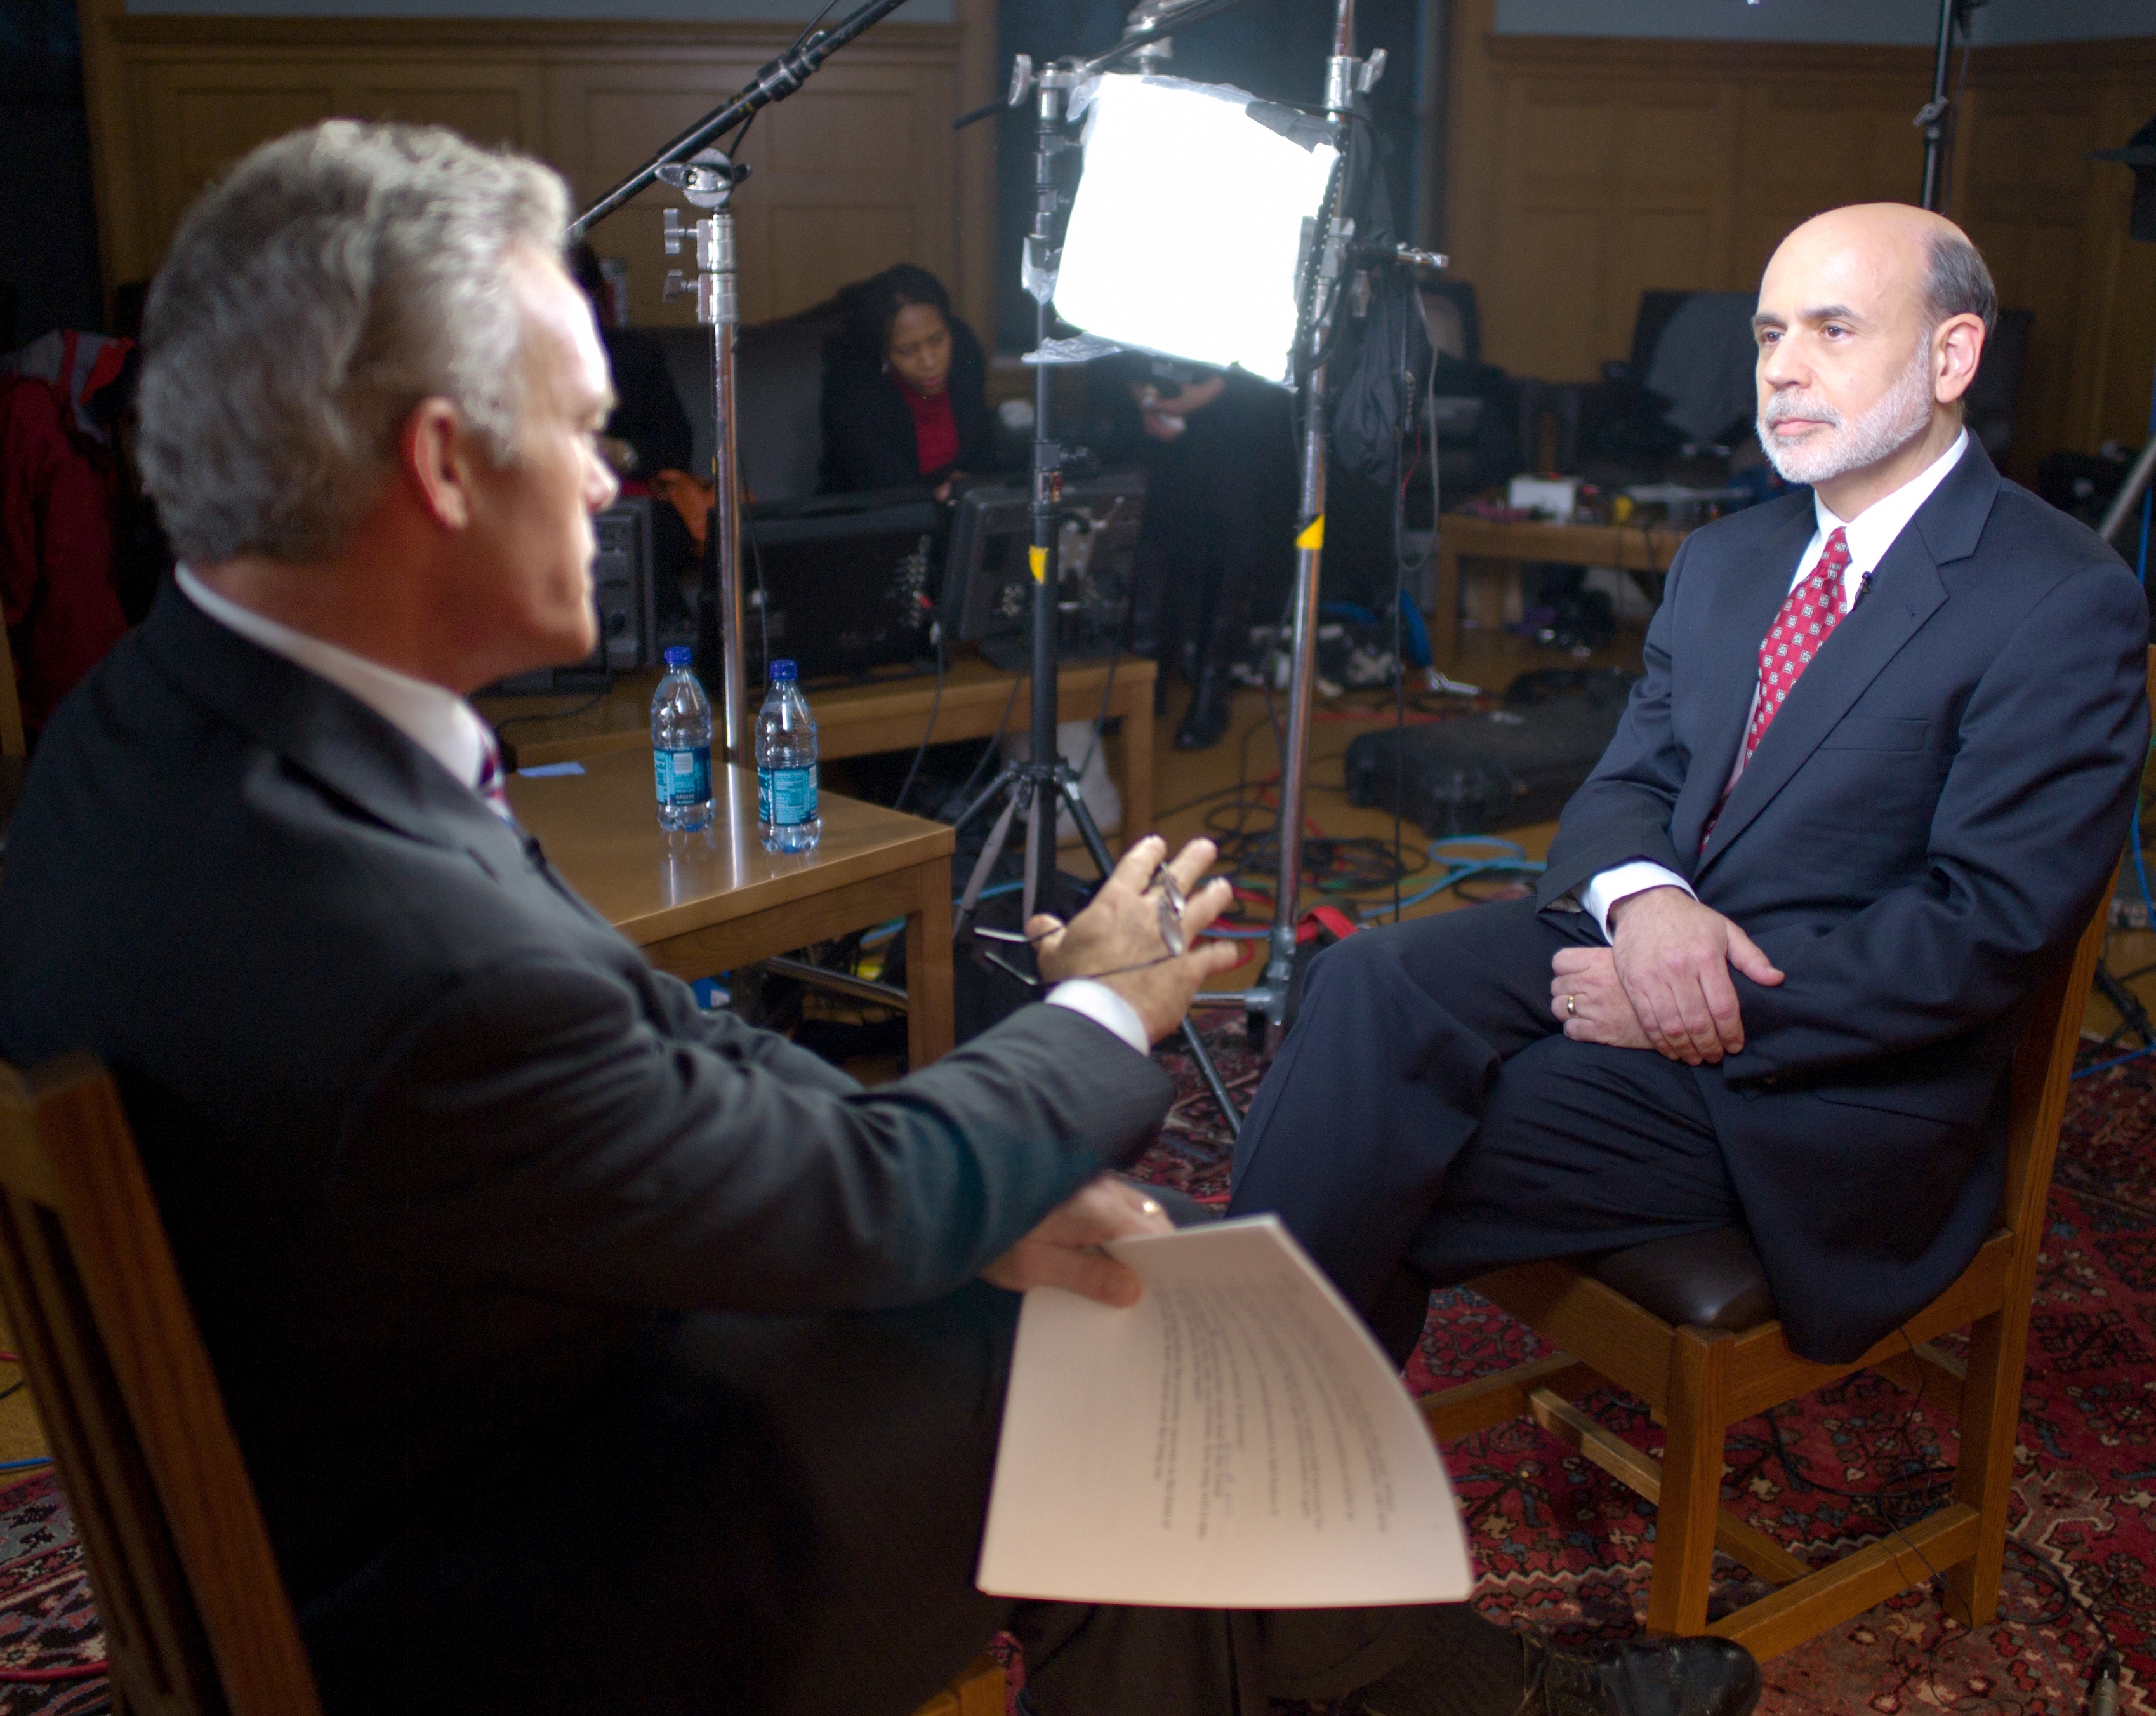
Former Fed Chairman Ben Bernanke when he was on 60 Minutes: Scott Pelley: Is that tax money that the Fed is spending? Ben Bernanke: It’s not tax money… We simply use the computer to mark up the size of the account.

Statement from the St. Louis Fed: “As the sole manufacturer of dollars, whose debt is denominated in dollars, the U.S. government can never become insolvent, i.e., unable to pay its bills. In this sense, the government is not dependent on credit markets to remain operational.”

The federal government “cannot become insolvent,” can “produce as many U.S. dollars as it wishes,” does not spend tax money or any other form of income, and does not borrow (i.e., “depend on credit markets”). In short, the federal government uniquely is Monetarily Sovereign. All the others mentioned above are monetarily non-sovereign.You and I can become insolvent. You and I cannot produce dollars at will. We do rely on income. And we do borrow. Vast difference that Paul, Boehm and the Libertarians don’t seem to get. The Libertarians essentially think the sun and the moon are the same because, hey, they both are in the sky, aren’t they. Boehm’s mind seemingly is closed to the fundamental difference between Monetary Sovereignty and monetary non-sovereignty. So he wants to balance the budget as though the federal government was just like you and me. Here is what happens when the government simply reduces deficit spending growth (not even going so far as to balance the budget; just reduce the growth).
The Red line shows the annual increases and decreases in federal deficit spending. Vertical gray bars are recessions.
We have recessions when the federal deficits increase less than the previous year. Those recessions are cured when federal deficits increase more than the previous year. The graph shows deficits increase almost yearly, but we have recessions when they don’t grow enough. Now let’s take a closer look at what happens during those rare times when the federal government runs a surplus.
In the 3rd quarter of 1955, the government began to run a surplus, which led to a recession in 1957. The recession was cured when we started to run a deficit in 1958.
 
Deficit growth declined until the middle of 1969 we fell into a surplus, which led to a recession. The recession was cured after deficits returned in 1970.
 
Deficit growth declined until the 3rd quarter of 1998 until we fell into a surplus, which led to the recession of 2001. That recession was cured when we climbed back into deficit growth.
Here are more historical data showing what happens when the federal government runs surpluses:

1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807. 1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819. 1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837. 1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857. 1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873. 1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893. 1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929.

Paul Rand, Eric Boehm, all the Libertarians, and many others do not understand a simple mathematical truth: A growing economy requires a growing supply of money. A standard measure of the economy is Gross Domestic Product (GDP) which consists of Federal Spending + Non-federal Spending – Net Imports. GDP can increase only if the net total of those three money measures increases. That’s arithmetic. Further, because Net Exports usually decrease, the burden is on Federal Spending to increase enough to overcome that money loss. Thus, simple arithmetic demonstrates that for real GDP to grow, the money supply must grow and that money supply growth relies on federal deficits to exceed Imports and inflation. That is why a balanced budget or a surplus invariably leads to recessions and depressions. Continuing with the Reason article:

As he pitched his Senate colleagues on a plan to balance the federal budget in 2018, Sen. Rand Paul (R–Ky.) warned that rising inflation would be one of the consequences of a failure to bring deficit spending under control.

Wrong. There is no relationship between deficit spending and inflation.
Changes in federal debt (blue) do not parallel changes in inflation (red).
But, changes in oil prices (green) do parallel inflation (red). Inflation is caused by critical goods and services shortages, generally energy and specifically oil.
The graphs are clear. Oil prices, not federal spending, determine inflation.
Oil price changes are closely related to changes in oil supply, which is determined by changes in oil production. Here is a graph of total world energy production: Here is the data in millions of barrels:
This image has an empty alt attribute; its file name is image-4.png
Oil production in 2020 and 2021 was lower than in 2014, the purpose being to work off inventories that had become too high during the COVID years.
As the world’s economies began to recover from COVID-19’s reduced oil usage, renewed oil production did not keep pace. This lack of oil production, not low-interest rates or “excessive spending,” caused today’s inflation. Today’s critical shortages are food, housing, computer chips, shipping, baby formula,  lumber, labor, and other goods. Today’s shortages are not caused by increased demand. Mothers did not suddenly begin to demand more baby formula. The number of people needing shelter did not mysteriously increase. As with most ailments, you must fix the cause to cure the symptom. Shortages are the cause; inflation is the symptom. To cure inflation, we must cure the shortages. Reduced availability of goods and services primarily was due to  COVID, global warming, and the Russia – Ukraine war. That is what caused the shortages. Starving the economy of money, which Paul, Boehm, and the rest of the Libertarians wish to do, does not reduce shortages of oil and other vital goods. Neither does increasing interest rates. Shortage-caused inflations can be cured only by treating the shortages. This can be accomplished counterintuitively by increased government spending to improve the cost-availability of scarce goods and services.

At the time, Paul was pushing a bill that would have required a spending cut equal to one penny out of every dollar in the federal budget.

The so-called “Penny Plan” would have balanced the federal budget by 2023, Paul claimed at the time, without requiring serious cuts to any specific programs.

Paul exerted senatorial privilege to force a vote on the package; it failed 21–76.

Taking dollars out of the private sector accomplishes only one thing: Recession if we are lucky, depression if we are not. Had Paul succeeded, we would have experienced a deep recession or a depression, together with inflation which would have been exacerbated by the Fed’s interest rate cuts.

That was before the federal government borrowed trillions of dollars in the name of combatting the COVID-19 pandemic.

Here again, Boehm reveals his ignorance of federal finance. The U.S. federal government never borrows dollars. Think, Mr. Boehm: Why would an entity having the unlimited ability to create dollars ever borrow them? It wouldn’t, and it doesn’t. Boehm is confused by the misleading word, “debt.” He assumes that T-bills, notes, and bonds are loans. They are not. Nor are they owed by the federal government. T-bills, notes, and bonds are deposits into privately-owned accounts at the Federal Reserve. If you ever bought a T-bill, you owned such an account, which was similar to a safe-deposit box. You put your dollars into your own account. You did not give them to the government. As with a safe-deposit box, the federal government never used the dollars in your T-security account. To pay you off, the federal government merely returns your dollars to you. No taxes or government dollars are involved. It simply is a money transfer, similar to transferring dollars from your safe-deposit box to your checking account. (Unlike borrowing, the purpose of T-securities is not to provide spending money for the government. T-securities provide a safe, interest-paying parking place for unused dollars. That’s why China et al has them. This helps the Fed stabilize the dollar.)

It was before President Joe Biden’s $1 trillion infrastructure package. It was before four more years of bulging federal budgets authorized by a Congress that’s increasingly blithe about borrowing.

“Bulging,” “blithe,” and “borrowing” are words meant to frighten or anger the innocent, but they only reveal ignorance. The budgets do not “bulge.” Congress is not “blithe.” And the government does not “borrow.” In October 1971, in the greatest act of his administration, Richard Nixon took us off the last gold standard, thus freeing Congress to spend stimulus dollars, which no longer were limited by gold reserves.

With inflation now running seemingly out of control and trillion-dollar deficits being the new norm in Washington, Paul was back on the Senate floor Wednesday to offer another bill to balance the budget in five years.

This time around, however, it would require cutting six cents for every budgetary dollar.

The proposal failed, 29–67.

Thank goodness. Had it succeeded, we would have slipped into a severe depression. We still may if we rely on interest rate increases to cure inflation.

“Washington’s addiction to spending is hurting our economy and depleting our currency. Inflation is stealing every American’s purchasing power and financial security,” Paul said in a statement after the vote.

Paul should have said, “Washington’s spending adds growth dollars to the economy, without which the U.S. would suffer a depression. Spending does not cause inflation. Shortages do. Spending cures inflation when it cures shortages.”

“All this plan does is return to 2019 spending levels. If the federal government spent at 2019 levels this year, we would have a $388 billion surplus.”

That $388 billion federal surplus would have been a $388 billion deficit for the economy. We have seen what results from federal surpluses. No knowledgeable person takes dollars from the economy and gives them to a federal government that has the infinite ability to create dollars. The purpose of federal taxes is not to provide the government with spending money. Unlike state and local taxes, which remain in the economy, federal tax dollars are destroyed upon receipt. They cease to be part of the private sector (aka “the economy”) and disappear into the federal government’s infinite supply of dollars. Add anything to infinity and it remains infinity. The purpose of federal taxes is to help the government control the economy by rewarding what the government wishes to encourage and by penalizing what the government wishes to discourage.

Indeed, about the only thing that’s changed in the four years since Paul offered the Penny Plan is the size of the numbers involved.

America has piled up an incredible $11 trillion of debt since 2018—that’s more than one-third of the nation’s total credit card bill—as annual budget deficits surged even before emergency pandemic borrowing blew them through the roof.

More non-scientific street language from Boehm, who has yet to provide actual data to prove his point. Why? No data exists to demonstrate that deficit spending causes inflation or harms the economy in any way.

President Donald Trump oversaw an expansion of debt-fueled government spending during his term in office, and Biden has followed suit.

In his first year in office, Biden has added $2.4 trillion to the nation’s long-term deficit—despite the White House’s best efforts to hide that fact.

The White House would not hide adding growth dollars to the economy. It wanted to add even more growth dollars, with its “Build Back Better” proposal but was stymied by a GOP that feared BBB would grow the economy, reduce shortages, eliminate inflation, and assure Biden of a second term.

In the face of this unsustainable fiscal situation, an across-the-board cut of six pennies per every dollar to balance the budget seems like a pretty good deal.

“Unsustainable” is the favorite nonsense word of the budget cutters. That and “ticking time bomb” substitute for data. The “debt” has grown from $400 Billion in 1940 to $30 trillion today, and the government still is “sustaining.” No federal check has bounced. And what would have been cut? Social Security, Medicare and other benefits for the middle- and lower-income groups.

And things are rapidly spiraling. The Federal Reserve announced a 0.75 percent interest rate hike on Wednesday, just hours before Paul presented his budget plan on the Senate floor.

Those higher interest rates will rebound into the federal budget in the form of higher interest payments on the national debt.

Under the Congressional Budget Office’s (CBO) latest budgetary baseline, interest payments on the debt are expected to triple between now and 2032.

If federal interest payments triple, the economy will receive triple stimulus dollars. Our Monetarily Sovereign government can afford it and our economy can use it.

If interest rates climb higher than the CBO expects, however, the federal government could be paying trillions more simply to finance government spending that already occurred.

Those trillions that Boehm fears actually will be stimulus dollars pumped into the private sector. Growth for the economy; easily affordable for our Monetarily Sovereign government.

Obviously, that will make any future attempt at balancing the budget an even more difficult task.

That’s good news.

The opportunity to balance the budget by cutting a mere penny out of every dollar of federal spending has come and gone. After Wednesday’s vote, the Six Penny Plan’s days are likely numbered too.

That’s even better news. In Summary, the Pauls and the Boehms of the world do not know (or pretend not to know) the fundamental difference between a money creator and a money user, i.e. the Monetarily Sovereign U. S. government vs. monetarily non-sovereign everyone else who spends and accepts U.S. dollars.
This image has an empty alt attribute; its file name is image-6.png
Taking money from the economy to cure inflation is like applying leeches to cure anemia.
Monetary Sovereignty is the basis for all of economics. Those who don’t understand it simply do not understand economics. Money is the lifeblood of an economy. The budget-cutters remind one of the quack doctors who apply leeches to cure anemia, thus killing the patient. Paul and Boehm wish to apply leeches to the economy, starving it of its money lifeblood. That is what ignorance can do. Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:
  1. Monetary Sovereignty describes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”
Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps: Ten Steps To Prosperity:
  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 
The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY

The Relentless Con Job By The Rich. The Big Lie In Economics

The efforts of the rich to become even richer never end.

The rich incessantly promulgate lies about our economy. More importantly, they bribe the primary influencers — the politicians, the media, and the economists — to spread the Big Lie that federal spending is funded by federal taxes.

File:Scottpelley.jpg - Wikimedia Commons
Bernanke: “It’s not tax money… We simply use the computer to mark up the size of the account.”

In reality, federal spending is funded by ad hoc federal money creation, not taxes.

Unlike state and local government taxes, all federal tax dollars are destroyed upon receipt.

The tax dollars no longer exist in the economy (the private sector), and since the federal government has infinite dollars, the tax dollars no longer exist anywhere.

The Big Lie convinces the populace that the federal government’s ability to provide benefits is financially limited by tax receipts.

(Politicians are bribed via campaign contributions and promises of lucrative jobs. The media are bribed via advertising dollars and actual ownership. Economists are bribed via gifts to universities and lucrative positions on “think tanks.”) 

Whenever you hear about a federal benefit, and someone asks, “Who will pay for it?” you should know you are about to listen to the Big Lie. The answer is: “The federal government will pay for it by creating dollars.”

Quote from former Fed Chairman Ben Bernanke when he was on 60 Minutes:
Scott Pelley: Is that tax money that the Fed is spending?
Bernanke: It’s not tax money… We simply use the computer to mark up the size of the account.

“Social Security and Medicare are about to become insolvent” is an example of the Big Lie, the purpose of which is to distance the rich from the rest of us.

“Rich” is a comparative, not an absolute. If you have a million dollars, you are rich if most others have less than a million. But you are not wealthy if everyone else has ten million.

That leaves you two ways to become richer: Get more for yourself or make the others have less. The rich in America have chosen both courses.

They try to grab more for themselves; their efforts to force you to have less are not as obvious.

The rich receive most of their income from sources other than salaries. Consider FICA. Congress has deemed FICA should be collected only from salaries, not from other forms of income.

Further, Congress has decided FICA is to be collected on salaries less than $142,800. Anything above that is not taxed.

The FICA limit is just one of the thousands of tax breaks the rich have “encouraged” Congress to give them. The purpose: To widen the Gap between them and you. Widening the Gap makes them richer.

U.S. federal finances are unlike state & local government finances, business finances, and euro nation finances.

The Map and the Territory, by Alan Greenspan | Financial Times
Former Fed Chairman Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency.”

The U.S. government is Monetarily Sovereign. It has the unlimited ability to create its own sovereign currency.

It never unintentionally can run short of dollars.

Yet we see organizations funded by the rich claiming that federal spending, which goes to the middle- and lower-income people, is detrimental to the middle- and lower-income people.

They want you to believe you should receive lower benefits and pay more taxes.

If they can cement that belief in your minds, you’ll vote for the very people who take money from your pocket.

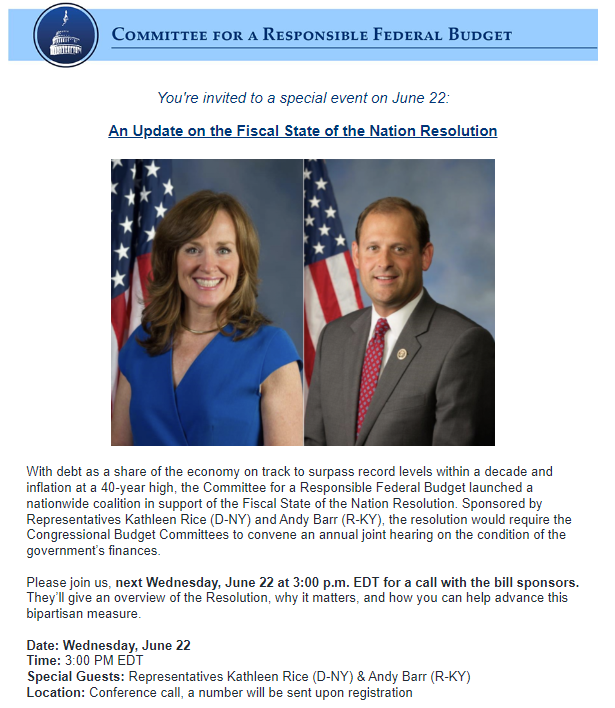
Here is the entirety of a page posted by the Committee For A Responsible Budget, one of the organizations that continually tries to foist on you the false idea that you should have less.

Every single sentence, including the headline, is false and/or an outright lie:

Why High and Rising National Debt is a Problem

FALSE. High and rising National (i.e., federal) Debt is not a problem. It is not even Debt. It is the total of deposits into Treasury security accounts at the Federal Reserve.

These accounts resemble safe-deposit boxes. When you buy a T-bill, T-note, or T-bond, you open an account at the Federal Reserve and deposit your dollars into it.

The federal government never touches those dollars. It has no need to.

The government can pay off the so-called “debt” merely by returning to you the dollars in your account.

This is no burden on the government, taxpayers, or the economy. There is no “Problem.”

High and rising national Debt will threaten economic growth and the standard of living for all Americans. High Debt will slow the growth of the economy and wages.

FALSE. Federal “debt,” i.e., the total of deposits in T-securities, is set by law to equal the cumulative total of federal deficits.

Bernanke sees decent chance for Fed to pull off a 'soft-ish landing' | The  Hill
Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”

Deficits are the difference between the amount of money the government takes out of the economy vs. the amount it puts in (with some going to foreign nations).

Rising national “debt” occurs when the federal government puts more dollars into the economy than it takes out.

There is no mechanism by which adding money to the economy can “slow the growth of the economy and wages.”

On the contrary, when economic growth slows, the government adds more stimulus dollars (increases the “debt”) to prevent or cure a recession.

The “debt” has no direct effect on wages, which are a function of business profits (stimulated by federal deficit spending) and labor supply.

As Debt rises, higher interest payments will crowd out important investments in areas like education, infrastructure, and research that can help grow the economy.

FALSE. Federal Debt does not force higher interest rates. Interest rates are set arbitrarily by the Federal Reserve to control inflation.

The peaks and valleys of changes for Federal deficits (blue) neither correspond to changes in Interest rates (red) nor are they a leading indicator. Note the 12 years 2008 – 2020, when federal deficit spending grew massively while interest rates neared zero.

Federal interest payments do not “crowd out” other federal payments for “education, infrastructure, and research. The federal government has infinite money with which to pay for anything.

During periods of high deficit spending, interest rates have been low.

Getting the Debt under control once the crisis is over will be very beneficial for generations to come, from higher wages to increased investment to lower borrowing costs for families and businesses.

FALSE. This paragraph is just a restatement of the previous section. There is no mechanism by which fewer dollars coming into the economy can cause “higher wages, increased investment, and lower borrowing costs.

The last decade shows the opposite: Higher deficits along with higher wages, increased investment, and low borrowing costs.

The Congressional Budget Office predicts that the economy will grow faster with Debt on a declining path as opposed to a rising one.

FALSE: History shows that declining Debt leads to depressions and recessions.

1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807.
1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819.
1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837.
1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857.
1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873.
1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893.
1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929.
1997-2001: U. S. Federal Debt reduced 15%. Recession began 2001.

The reason is quite simple. Reducing federal Debt requires taking dollars out of the economy. 

Just as adding stimulus dollars to the economy prevents and cures recessions and depressions, taking dollars out of the economy causes recessions and depressions.

The rich do not fear recessions and depressions. They are less harmed than the rest of us. They have more cushion to weather the hard times.

During recessions and depressions, workers become more desperate for jobs, giving the rich the opportunity to cut wages and increase their own relative incomes.

In addition to publishing the completely non-sensical paragraphs just discussed, The rich-run CRFB runs “hearings” on the condition of the government’s finances.”

These hearings contain nothing more than recitations of the Big Lie — false propaganda we have just discussed. The purpose will be to give Congress excuses to:

    • Cut Social Security benefits
    • Cut Medicare benefits
    • Eliminated Obamacare
    • Increase FICA taxes
    • Cut other benefits for the poor and middle-classes
    • Widen the income/wealth/power Gaps between the rich and the rest 

The drumming of lies and misstatements from the rich and toadies for the rich is relentless. So long as it works to indoctrinate the public, it never will end.

The attempts at indoctrination end only when you, the public, demonstrate your understanding of the lies and your willingness to punish the liars.

Fool you once; shame on them. Fool you thousands of times, over and over and over; shame on you.

[No rational person would take dollars from the economy and give them to a federal government that has the infinite ability to create dollars.]

Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:

  1. Monetary Sovereignty describes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps: Ten Steps To Prosperity:

  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY

“Wolf!” “The sky is falling” “Social Security and Medicare will be insolvent.”

Which of the following is a story with a false narrative: “The Boy Who Cried Wolf!” or “Henny Penny announcing, ‘The sky is falling,”or “The CRFB claiming, “Social Security and Medicare will be insolvent”?

Answer: All three are false narratives. The first two are meant to teach children valuable lessons. The third should teach adults a valuable lesson.

That lesson is: Don’t believe the Committee for a Responsible Federal Budget (CRFB) when it howls like a wolf, squawks like a chicken, and pontificates in solemn terms that Social Security and Medicare “trust funds” are running short of dollars.

It’s all lies.

Here is what the CRFB now says:

Trustees: Social Security and Medicare Headed for Insolvency in 13 and 6 Years The Social Security and Medicare Trustees just released their 2022 reports on the financial status of the Social Security and Medicare programs.

The Trustees show that the Social Security and Medicare Hospital Insurance (HI) trust funds rapidly approach insolvency. Their funding imbalances need to be addressed sooner rather than later to prevent across-the-board benefit cuts or abrupt changes to tax or benefit levels.

In effect, the CRFB claims:

1. Social Security and Medicare benefits are paid for by trust funds.

2. These “trust funds” will run short of money.

3. The solution to Medicare or Social Security insolvency requires cutting benefits and/or increasing taxes.

All three are factually FALSE.

1. SOCIAL SECURITY AND MEDICARE BENEFITS ARE PAID FOR BY TRUST FUNDS

Wrong.

To quote from the Peter G. Peterson Foundation website:

Federal trust funds bear little resemblance to their private-sector counterparts, and therefore the name can be misleading.

A private sector “trust fund” implies a secure source of funding.

(A federal trust fund merely tracks inflows and outflows for specific programs. There is no secure source of funding.)

In private-sector trust funds, receipts are deposited, and assets are held and invested by trustees on behalf of the stated beneficiaries.

In a federal trust fund, the receipts — as part of the M2 money supply measure — are destroyed upon receipt. They no longer are part of any money supply measure.

There are no stated beneficiaries, as the criteria for beneficiaries change daily.)

The federal government owns the accounts and can, by changing the law, unilaterally alter the purposes of the accounts and raise or lower collections and expenditures.

The federal government (Congress and the President) can do whatever they wish with the “trust funds”: Add to them, subtract from them, or change them to pay for anything or nothing.

At the click of a computer key or the passage of a law, the balance in any federal “trust fund” could be changed to $100 trillion or $0 or anywhere in between.

Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency.”

If Congress and the President wished, the Medicare “trust fund” could be changed to pay for Las Vegas vacations, jewelry, Congressional vacations, etc. Almost every year, the federal government arbitrarily changes what Medicare will pay for and how much it will pay.

In fact, that is exactly what the CRFB suggests when it writes about “benefit cuts or abrupt changes to tax or benefit levels.”

In a real “trust fund,” the trustees would not have that control.

2. THESE TRUST FUNDS WILL RUN SHORT OF MONEY

Wrong.

The United States government is unlike state and local governments. It also is unlike euro governments, private businesses, you, and me. The U.S. government uniquely is Monetarily Sovereign. It is sovereign over the United States dollar.

In the 1780’s it created the original dollars from thin air and gave them an arbitrary value. Today, the government continues to create dollars from thin air and continues to provide them with an arbitrary value.

Ben Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”

The government never unintentionally can run short of its own sovereign currency, the dollar. Even if the federal government didn’t collect a penny in taxes, it could continue spending forever.

This absolute control over the U.S. dollar means no federal government agency can run out of dollars unless Congress and the President will it.

The only way Medicare or Social Security or any other federal agency can run short of dollars is if Congress and the President want them to run short of dollars.

3. THE SOLUTION TO SOCIAL SECURITY AND MEDICARE INSOLVENCY REQUIRES CUTTING BENEFITS OR INCREASING TAXES

Wrong.

Despite all the pretense about fake “trust funds,” Federal taxes (which include FICA) do not fund Medicare or Social Security. Those FICA dollars deducted from your paycheck (but tellingly, not deducted from other sources of income received by the wealthier among us) — those FICA dollars do not pay for anything. 

They merely become part of the federal government’s infinite supply, and effectively are destroyed. (You mathematicians know that infinity plus any amount still = infinity. Thus, your tax dollars do not increase the federal government’s supply of dollars by even one cent.)

In fact, with regard to Medicare Part B, there is a wholly different pretense.

While Medicare Part A (pays for hospitals and doctors, Part B pays for clinical research, ambulance services, durable medical equipment, and some drugs. And Medicare recipients are charged extra, above FICA, ostensibly to pay for Part B. 

But in reality, those charges, like all dollars coming into the federal government, are destroyed upon receipt.

The solution for Social Security and Medicare insolvencies is simply for the federal government to pay for them, which it could do the same way it pays for everything: By creating new dollars, ad hoc.

So group the warnings about Social Security and Medicare “trust fund” insolvency along with the boy who cried, “wolf” and Henny Penny’s “the sky is falling” as silly, little lies. There are no “trust funds.” Congress and the President have absolute control over all federal agency finances.

All your tax dollars are for naught. The federal government could and should provide free, comprehensive, no-deductible Social Security and Medicare for every man, woman, and child in America.

Continuing with the CRFB’s charade:

The Social Security Trustees estimate the Social Security Old-Age and Survivors Insurance (OASI) trust fund will deplete its reserves by 2034 and the Social Security Disability Insurance (SSDI) trust fund will not become depleted within the 75-year projection window for the first time since the 1983 Trustees’ report.

On a combined theoretical basis, assuming revenue is allocated between the trust funds in the years between OASI and SSDI insolvency, Social Security will become insolvent by 2035. Upon insolvency, all beneficiaries will face a 20 percent across-the-board benefit cut, which will grow to 26 percent by 2096.

The Trustees estimate a 75-year actuarial shortfall of 3.42 percent of taxable payroll for Social Security, which is slightly lower than the 2021 report’s estimate of 3.54 percent of payroll, but higher than any other year prior.

And blah, blah, blah. The CRFB substantiates the old saying, “Figures don’t lie, but liars figure,” by providing statistics to make their lies sound factual. 

Ooh, it must be true. There even is a graph. Except the graph is phony. The “Trust Fund Exhaustion” is based on the lie that Social Security benefits are paid by the fake “trust fund.” It’s not a trust fund and it pays for nothing. It’s just a record of ins and outs.

And here is another graph of lies:

Same story. The “Trust Fund Exhaustion” is based on a lie. The phony “trust fund” pays for nothing.

Why does the CRFB tell such big lies? 

I suppose it’s possible they don’t know they are lying, and that they are providing the misinformation out of economic ignorance.

Actually, I don’t think so. My belief, based on no data, is that they know it’s a lie. If I am correct, why are they lying?

It all comes down to Gap Psychology, the human desire to distance ourselves from lower income/wealth/power people, while coming closer to the higher income/wealth/power people.

Rich is a comparative word, not an absolute. You only can be rich if someone else is poorer. Without the Gaps, no one would be rich. We all would be the same. So, to become richer, you need the Gap below you to widen and/or the Gap above you to narrow.

And that even includes the rich, who want to be richer, which they can accomplish by making the rest of us poorer. 

Because the rich control the politicians, it is no coincidence that FICA is deducted from salaries rather than from the investment income that is the major part of the income received by the rich.

And there even is a cap on the income subject to FICA.

And then there are all the tax loopholes available to the rich — you know, those loopholes that made it possible for billionaire Donald Trump to avoid paying any taxes at all in 8 of the past 10 years. (How does it feel to know you’ve paid more taxes than a billionaire?)

Part of the plan by the rich, to widen the Gap below them, is to make you pay unnecessarily for Social Security and Medicare, and not only to pay more, but to have your benefits cut and taxed.

So the CRFB, as a paid mouthpiece for the rich, does everything it can to “prove” you should pay more taxes and receive less in benefits, thereby widening the Gap between you and the rich.

And they have been quite successful. Now that you have seen their phony statistics, here are some real statistics: Inequality is rising. The rich are growing richer; the poor are becoming poorer.

The Gini coefficient measures inequality, where “0” represents perfect equality (Everyone has the same) and “1” represents perfect inequality (where one person has everything). The higher the line, the more unequal the measure is.

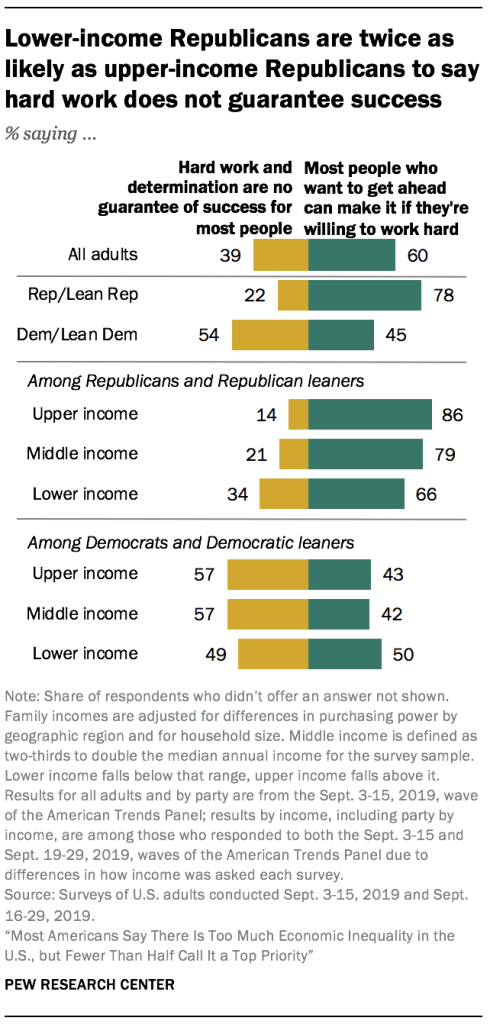
And finally, of the two major political parties, one, the Republicans, tend to believe the poor are poor because they are dumb and lazy, while the rich are rich because they are smart and work hard. Here is one example of that belief:

IN SUMMARY

  1. The U.S. federal government is Monetarily Sovereign. It never unintentionally can run short of its own sovereign currency, the U.S. dollar. Even if $0 federal taxes were collected, the federal government could continue spending forever.
  2. Medicare and Social Security, as agencies of the U.S. government, cannot run short of dollars unless that is what Congress and the President want. The federal government funds all its agencies’ pending by creating new dollars, ad hoc. All tax income is destroyed upon receipt.
  3. The Medicare and Social Security “trust funds” are not trust funds. These fake trust funds do not pay for benefits, but only keep records of dollar inflow and federal spending. As mere record keepers, they neither can be solvent nor become insolvent.
  4. There is no financial reason to cut Medicare or Social Security benefits or to increase taxes, or even to continue collecting taxes. The federal government funds benefits paid by both programs regardless of tax income.
  5. “Rich” is a comparative, not an absolute. According to Gap Psychology, people generally wish to widen the income/wealth/power Gaps below and to narrow those Gaps above. The rich can become richer by acquiring more for themselves and/or by forcing those below to acquire less. 
  6. The rich run America by bribing politicians, the media, and economists. To make themselves richer, the rich widen the Gap below by backing false narratives and laws that reduce federal benefits to the poorer while increasing taxes on the poorer.

Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:

  1. Monetary Sovereignty describes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps: Ten Steps To Prosperity:

  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY