Why cut the state tax deduction?

If you begin with the wrong assumptions, you come to the wrong conclusions.

Here are excerpts from an article in Bloomberg, where the author mistakenly assumes that federal taxes pay for federal spending. 

Image result for burning dollars
Your federal tax dollars are destroyed upon receipt.

While state and local taxes do fund state and local spending, federal taxes do not fund federal spending. Your federal tax dollars are destroyed upon receipt.

Not understanding the difference between federal and state finances, (the federal government uniquely is Monetarily Sovereign), the author offers wrong conclusions:

Get Rid of the State-Tax Deduction Altogether
High-income taxpayers in high-tax states don’t deserve special treatment.By Michael R. Strain, February 28, 2019

(Michael R. Strain is a Bloomberg Opinion columnist. He is director of economic policy studies and resident scholar at the American Enterprise Institute. He is the editor of “The U.S. Labor Market: Questions and Challenges for Public Policy.)

The 2017 tax law capped at $10,000 the amount of state and local tax payments a household can deduct from its federal income taxes. Previously, people could deduct the entire amount they paid in state and local property taxes, and either the state individual income tax or state sales tax.

According to a Treasury Department estimate released Tuesday, this cap will stop 10.9 million tax filers from writing off these payments from their federal income taxes, with the largest bite felt in high-tax states like New York, New Jersey and California.

Though politicians from these states are howling — New York Governor Andrew Cuomo recently met with President Donald Trump to discuss his concerns — limiting this deduction was the right thing to do.

Congress should go all the way and repeal what remains of it.

Importantly, just because 11 million people may lose this popular tax break — which has been in the federal code since the income tax was created a century ago — does not mean that all of them will be paying a larger share of their income in federal taxes.

An analysis by the Tax Policy Center in December 2017 found that 80 percent of households would receive a tax cut in 2018, while only 5 percent will face a tax increase. (As temporary provisions of the 2017 law expire, more households will face a tax increase in future years.)

An initially appealing argument in favor of this deduction is that it reduces an individual’s marginal income tax.

That’s only part of the story. By shrinking the federal income tax base relative to what it would be without the deduction, raising any given amount of revenue requires higher tax rates.

This likely offsets the deduction’s marginal rate reduction.

Mr. Strain reveals his belief that our Monetarily Sovereign government, which creates dollars by spending dollars, and never can run short of dollars,  needs to increase taxes when spending increases. He is wrong.

The federal debt itself demonstrates that federal taxes don’t fund federal spending.

Let me remind you of what two experts in the field have said:

Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency.”

Ben Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”

Could anything be clearer? Nothing “requires higher taxes.”  In fact, nothing requires federal taxes at all.

So why does a government, having the unlimited ability to create its own sovereign currency, levy taxes?

The primary reason is economic control. Things they wish to encourage (i.e. charity, business investment, etc.)  are tax deductible. Things they wish to discourage (i.e. smoking, alcohol, gambling, etc.) are heavily taxed.

And most importantly, the people the politicians wish to reward (i.e. rich donors) are given the lowest tax rates on what matters: Asset growth, long-term capital gains, dividends, and delayed taxes on various sorts of income.

The state and local deduction also encourages taxpayers to itemize their deductions rather than take the standard deduction.

This leads people to use other deductions more as well, amplifying the harm done from much less defensible tax breaks, like the one for mortgage interest payments.

The government made mortgage interest deductible in order to encourage home ownership.

There is no “harm done” by this deduction. On the contrary, the “harm done” is the taxing of mortgage payments. Tax dollars are taken from the private sector and given to the federal government, where they are destroyed.

Again, the U.S. Treasury destroys your hard-earned tax dollars upon receipt, and creates brand new dollars by spending. That is the government’s method for “printing” dollars.

The destruction of dollars impoverishes the economy, just as all federal taxes do.

For the reasons I mentioned above, we should want a broader base and lower rates, not a smaller base and higher rates.

The above sentence makes no economic sense. The federal government could get along quite nicely, thank you, if it collected, and then destroyed, zero taxes.

Meanwhile, the economy, i.e. the private sector, would flourish by the additional money that remained in consumers and businesses pockets.

In addition, the state and local deduction is a subsidy to states with large numbers of high-income individuals.

Because they face higher marginal income tax rates, deductions are relatively more valuable to this group of taxpayers.

The above sentences are mathematically correct but in practice, wrong.

The state and local tax deductions benefit residents, not the state governments, which receive no direct dollars from that tax deduction.

And it is not the rich who benefit most The rich pay for their homes via business expenses and other tax avoidance schemes. It is the middle and upper-middle classes in these states, that pay the penalty.

These are the people who have homes in higher-tax locations, and perhaps summer homes as well, but are not in the hundreds-of-millions or billions category.

Bottom line, everyone, rich and poor in America, is punished when the private sector must send dollars to the federal government. 

Residents of lower-tax states should not be on the hook for spending decisions of governments in higher-tax states.

Of course, higher-income households (many of which are located in higher-income states) do pay relatively more income tax, which is used to finance federal spending programs and transfer payments, some of which benefit citizens in other, lower-income states.

Again, Mr. Strain demonstrates ignorance of federal financial reality.

Residents of one state never are “on the hook” for spending in other states, neither with regard to federal taxes or to taxes in the other states. Residents of a state are “on the hook” for taxes in that state.

And federal income tax is not used to “finance federal spending programs and transfer payments.” The federal government destroys tax dollars, and creates new dollars to finance all spending.

State and local spending finances some public goods, like education. And there is a role for government to subsidize education, because the benefits of an educated citizenry extend beyond the individuals enrolled in school.

It would be better to directly subsidize education than to use a roundabout state and local deduction to achieve that goal.

I agree that the federal government should finance education. See: Ten Steps to Prosperity: Step 4: Free education for everyone and Ten Steps to Prosperity: Step 5: Salary for attending school.

But this has nothing to do with the useless, indeed harmful, tax on mortgage payments and other state taxes.

Importantly, the $10,000 cap mitigates some of these concerns. For example, the cap and the larger standard deduction — another feature of the 2017 tax law — will lead many fewer households to itemize.

It doesn’t eliminate them, however. And the remaining deduction is significant. According to the Joint Committee on Taxation, 16.6 million tax filers will still claim the state and local tax deduction in 2018.

Because of this subsidy, the federal government is estimated to have lost $20 billion in revenue last year.

” . . . will lead many fewer households to itemize, but allow the richest to continue itemizing charitable and business-related deductions.

And read carefully what Mr. Strain is saying.  He thinks of not taking your tax dollars from your pocket as a “subsidy,” as though the government were giving you something rather than you not giving the government something.

Next time you fail to give your neighbor a gift, Mr. Strain suggests you thank them for the “subsidy.”

Congress should get rid of the deduction entirely. To minimize disruption, the deduction should be set on a gradual glide path toward zero over a number of years.

Doing so might mean that high-income people leave high-tax states, although the benefits to them of living in major urban centers makes me suspect that relatively few will do so.

Even if this does happen to a significant degree, it would not be something to bemoan. Households should decide where to live based on their preferences, not on tax policy.

Oh really, Mr. Strain? Is that what households “should” do? I have news for you. Not all of the population increase in Florida is due to the weather. Much of it is due to Florida’s low taxes.

Many thousands of people live in Florida at least six months out of the year, just to take advantage of its low taxes.

And now comes Mr. Strain summarizing his own economic ignorance:

The real change would be in the behavior of states.

Some would still choose to provide more services than others — this key feature of the U.S.’s federalist system would remain.

But they won’t be relying on a subsidy from the federal government — from taxpayers in other states — to pick up part of the tab.

No, Mr. Strain. Taxpayers in other states do not pick up the tab for better schools, better healthcare, better support for the impoverished, etc. that you seem to feel should be cut.

That is the right-wing, anti-poor, pro-rich theme. You should be ashamed.

Here is a good idea for everyone:

To contact the author of this story: Michael R. Strain at mstrain4@bloomberg.net

To contact the editor responsible for this story: Katy Roberts at kroberts29@bloomberg.net

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The most important problems in economics involve the excessive income/wealth/power Gaps between the richer and the poorer.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY
Student debt: The intentional crisis.

While America struggles with the Republicans’ $6 Billion, phony, “Wall crisis,” several real crises remain unattended, one of which is the Student Debt Crisis.

Back in December, 2015, we published, “Student loans and the unforgivable debt.” Today, more than three years later, the student debt has grown massively and remains even less forgivable.

Consider excerpts from the following article:

Student loan balances jump nearly 150 percent in a decade, By Jessica Dickler, CNBC

Over the last decade, college-loan balances in the United States have jumped more than $833 billion to reach an all-time high of $1.4 trillion.

The average outstanding balance is now $34,144, up 62 percent over the last 10 years.

In addition, the percentage of borrowers who owe $50,000 or more has tripled over the same time period.

A college education is now the second-largest expense an individual is likely to make in a lifetime — right after purchasing a home.

Many graduates have expressed buyer’s remorse regarding the cost of their education. To that point, 57 percent said they regret taking out as many loans as they did, and 36 percent said they would not have gone to college if they fully understood the associated costs.

That debt also has long-term consequences. From buying a car or a home to getting married and even having children, many millennials are putting off life’s major milestones because of their record debt.

Here are several observations regarding the above.

  1. The vast majority of American students attend grades K through 12 free, paid for by city and state governments.
  2. City and state governments are monetarily non-sovereign, meaning they do not have the unlimited ability to create money. City and state taxpayers fund city and state government spending, yet taxpayers, realizing the importance of education, willingly pay for K-12 schooling.
  3. By contrast the federal goverment is Monetarily Sovereign; it has the unlimited ability to create U.S. dollars. The federal goverment never can run short of dollars. Federal taxpayers do not fund federal spending. The federal government self-funds its spending by creating new dollars, ad hoc.
  4. In today’s, more sophisticated and competitive world, the education of young people, beyond high school, has become more important to America’s growth and success.
  5. Student debt discourages entrance to college, discourages finishing college, and discourages success after college.
  6. Student debt is unnecessary. Our Monetarily Sovereign federal government has no need to collect dollars from students. Rather than lending dollars to students, the government should give dollars to students, to pay for college. See: Ten Steps to Prosperity: Step 4: Free education for everyone  and Ten Steps to Prosperity: Step 5: Salary for attending school.e

In short, saddling students with federal debt, when the federal government has no need to collect the debt, makes no economic sense, and in fact is harmful to America’s future.

So why do we do it?

First, the American people do not understand the federal government’s Monetary Sovereignty. They wrongly believe that federal taxes pay for federal spending, so they resist efforts to increase federal spending, lest federal taxes increase.

Image result for greenspan
Alan Greenspan: Of course. Central banks can issue currency, a non-interest-bearing claim on the government, effectively without limit. A government cannot become insolvent with respect to obligations in its own currency

The people do not know that though state and local taxes pay for state and local spending, federal taxes pay for nothing, and in fact, are destroyed upon receipt by the U.S. Treasury.

Thus, we have the incredible irony of Americans willing to pay taxes to fund grades K-12, but not to fund grades 13+, which would cost no tax dollars at all.

Second, the rich run America by bribing politicians via political “contributions.”

“Rich” is a comparative term. A person having $100 is rich if everyone else has only $1, but is poor if everyone else has $10,000. So, in order to become richer, one either must increase his own wealth, or decrease everyone else’s.

Image result for bernanke
Ben Bernanke: The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.

(Gap Psychology describes the human desire to widen the Gap below oneself, on any economic or social measure, and to narrow the Gap above.)

Motivated by Gap Psychology, the rich wish to distance themselves from the not-rich.

One of the many ways the rich do that is by indebting the not-rich. Because the rich pay for their children’s college simply by writing checks, while the not-rich pay by borrowing, the student loan debt is a perfect device for widening the Gap between the rich and the rest.

(The rich also widen the Gap by such actions as:

  1. Cutting Social Security benefits on the false claim that Social Security is “insolvent.”
  2. Taxing Social Security benefits
  3. Collecting FICA and limiting collection to salaries below $132K
  4. Requiring everyone to pay for Affordable Care Act (Obamacare), even when well.
  5. Taxing salaries at a higher rate than other forms of income most received by the rich.
  6. Allowing for tax shelters most used by the rich
  7. Requiring Medicare to be incomplete, i.e. not covering coinsurance, deductibles, and copayments.)

Bottom line: Student debt is an unnecessary, harmful program, perpetuated by the rich to widen the Gap between the rich and the rest.

To advance the interests of the United States, the federal government should eliminate student debt and provide a free college education for all who want one.

Rodger Malcolm Mitchell

Monetary Sovereignty

Twitter: @rodgermitchell

Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The single most important problems in economics involve the excessive income/wealth/power Gaps between the have-mores and the have-less.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY

Duck! The sky is falling and the “debt” is rising!

Here we go again: The same old story — the same old lie — we have documented since 1940. Nothing has changed and nothing has been learned.

National debt tops $22 trillion for the first time as experts warn of ripple effects by Michael Collins, USA TODAY Feb. 12, 2019

WASHINGTON – The national debt surpassed $22 trillion for the first time on Tuesday, a milestone that experts warned is further proof the country is on an unsustainable financial path that could jeopardize the economic security of every American.

Yes, way, way back in 1940, the federal budget was a “ticking time-bomb which can eventually destroy the American system,” said Robert M. Hanes, president of the American Bankers Association. Image result for time bomb

Every year since then, the self-proclaimed experts have told you the federal debt either is a “ticking time bomb,” “unsustainable,” “a threat to the economic security of every American,” or some other bit of scare nonsense.

In 1940, the so-called “debt” (It actually is “deposits,” but why be accurate when you want to fool the public?) was only $40 Billion. Today, it is about $17 Trillion, a gigantic 45,000% increase.

(The $22 Trillion figure includes internal debt, money one department of the government owes another department of the government — left pocket owes the right pocket. The debt scare-mongers use the larger number so as to scare you more.)

Despite that massive debt increase in the past 80 years, where is the “threat to economic security?” Why has that “ticking time bomb” not exploded? Eighty years is a long time to keep ticking and nothing happens.

The Treasury Department reported the debt hit $22.012 trillion, a jump of more than $30 billion in just this month.

The national debt has been rising at a faster rate following the passage of President Donald Trump’s $1.5 trillion tax-cut package a little more than a year ago and as the result of congressional efforts to increase spending on domestic and military programs.

The nation has added more than $1 trillion in debt in the last 11 months alone.

“Reaching this unfortunate milestone so rapidly is the latest sign that our fiscal situation is not only unsustainable but accelerating,” said Michael A. Peterson, chief executive officer of the Peter G. Peterson Foundation, a nonpartisan organization working to address the country’s long-term fiscal challenges.

Here is all you need to know about the Peter G. Peterson Foundation, an organization devoted to spreading the “Big Lie,” that the federal government’s finances are like state and local government finances, and the debt is “a ticking time bomb,” etc., etc., etc.

These folks never seem to be embarrassed about being wrong, wrong, and wrong yet again, year after year. They just keep on making those wrong predictions as though reality means nothing.

The “unfortunate milestone” is the kind of milestone banks boast about: An increase in total deposits.

For Americans, the growing debt should be a concern, experts said, because over time it can push up interest rates for consumers and businesses.

The higher rates can ripple through the economy, nudging up rates for mortgages, corporate bonds and other types of consumer and business loans.

The above two paragraphs are so far out of touch with reality, they are laughable.

First, if the growing debt could “push up interest rates,” why hasn’t the 45,000% increase in debt already pushed up interest rates, which today remain quite low?

Second, the Fed controls interest rates by fiat. When the Fed wants low rates, it mandates low rates. When it wants high rates, it mandates high rates.

If it wants to issue T-securities at a certain rate, and the public doesn’t buy them, the Fed simply can buy the T-securities, itself.

Being Monetarily Sovereign, i.e. sovereign over the dollar, the government can do anything it wishes with the dollar.

Third, higher interest rates actually grow the economy by increasing the number of interest dollars the government pumps into the economy.

The most common measure of the economy is Gross Domestic Product. GDP = Federal Spending + Non-federal Spending + Net Exports. Notice the words “Spending”? They include interest.

Fourth, private interest does not inhibit an economy; it merely circulates dollars. The borrower pays interest to the lender. It’s a cost to one, and income for the other. The total of dollars stays essentially the same.

Then, we come to the biggest lie of all:

A big national debt can also make it harder for the government to increase spending to combat the next recession or devote more money to retraining workers and helping the poor, among other programs.

Here, Peterson confuses federal finances with monetarily non-sovereign state and local finances.

The number of dollars deposited into T-security accounts has no effect on the government’s ability to spend. The government doesn’t touch the dollars in T-security accounts.

When the federal government spends, it sends instructions (not dollars) to a supplier’s bank, instructing the bank to increase the balance in the creditor’s checking account.

When the creditor’s bank does as instructed, brand new dollars are created and added to the money supply measure, M1.

Peterson attributed the growing national debt to “a structural mismatch between spending and revenues.”

The biggest drivers are the aging population, high healthcare costs, and growing interest payments, combined with a tax code that fails to generate sufficient revenue, he said.

“Structural mismatch” is Peterson-speak meaning more dollars are spend than are received in taxes.

But this has no effect on the federal government’s ability to spend. Because the federal government creates brand new dollars, every time it pays a bill, it could continue spending forever, even if total tax collections were $0.

In fact, tax dollars are destroyed immediately upon receipt by the U.S. Treasury.

The debt eclipsing $22 trillion “is another sad reminder of the inexcusable tab our nation’s leaders continue to run up and will leave for the next generation,” said Judd Gregg and Edward Rendell, co-chairmen of the nonpartisan Campaign to Fix the Debt, a project of the nonpartisan Committee for a Responsible Federal Budget.

Let us dispense with the “next generation” nonsense. The “next generation” didn’t pay for the $40 Billion debt of 1940. The “next generation” didn’t pay for the $3 Trillion debt of 1992. And today’s generation is not paying for any past debt.Image result for the end is near

Taxpayers do not fund federal debt. The deposits themselves are returned upon maturity, and the interest on those deposits is paid by new dollars created by the federal government.

No tax dollars involved. They are destroyed.

Also, let us dispense with this “nonpartisan” nonsence. These guys are rabidly partisan. The root for the rich and against the poor.

They want taxes on the rich cut, and benefits for the poor cut. How much more partisan can you get.

With deficits rising and gross debt scheduled to jump by more than $1 trillion annually, Congress must take action to put the country on a more sustainable path, Gregg and Rendell said.

“The fiscal recklessness over the past years has been shocking, with few willing to step up with a real plan,” they said. “We need responsible leadership to fix the debt, not a worsening of partisanship.”

And that is exactly what the debt fear-mongers have been saying for the past 80 years.

Pretending federal finances are like state and local government finances, or like personal finances, is designed to fool the public.

Because few people understand the basics of economics, the plot seems to have worked.

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The single most important problems in economics involve the excessive income/wealth/power Gaps between the have-mores and the have-less.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:
1. Eliminate FICA

2. Federally funded medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY
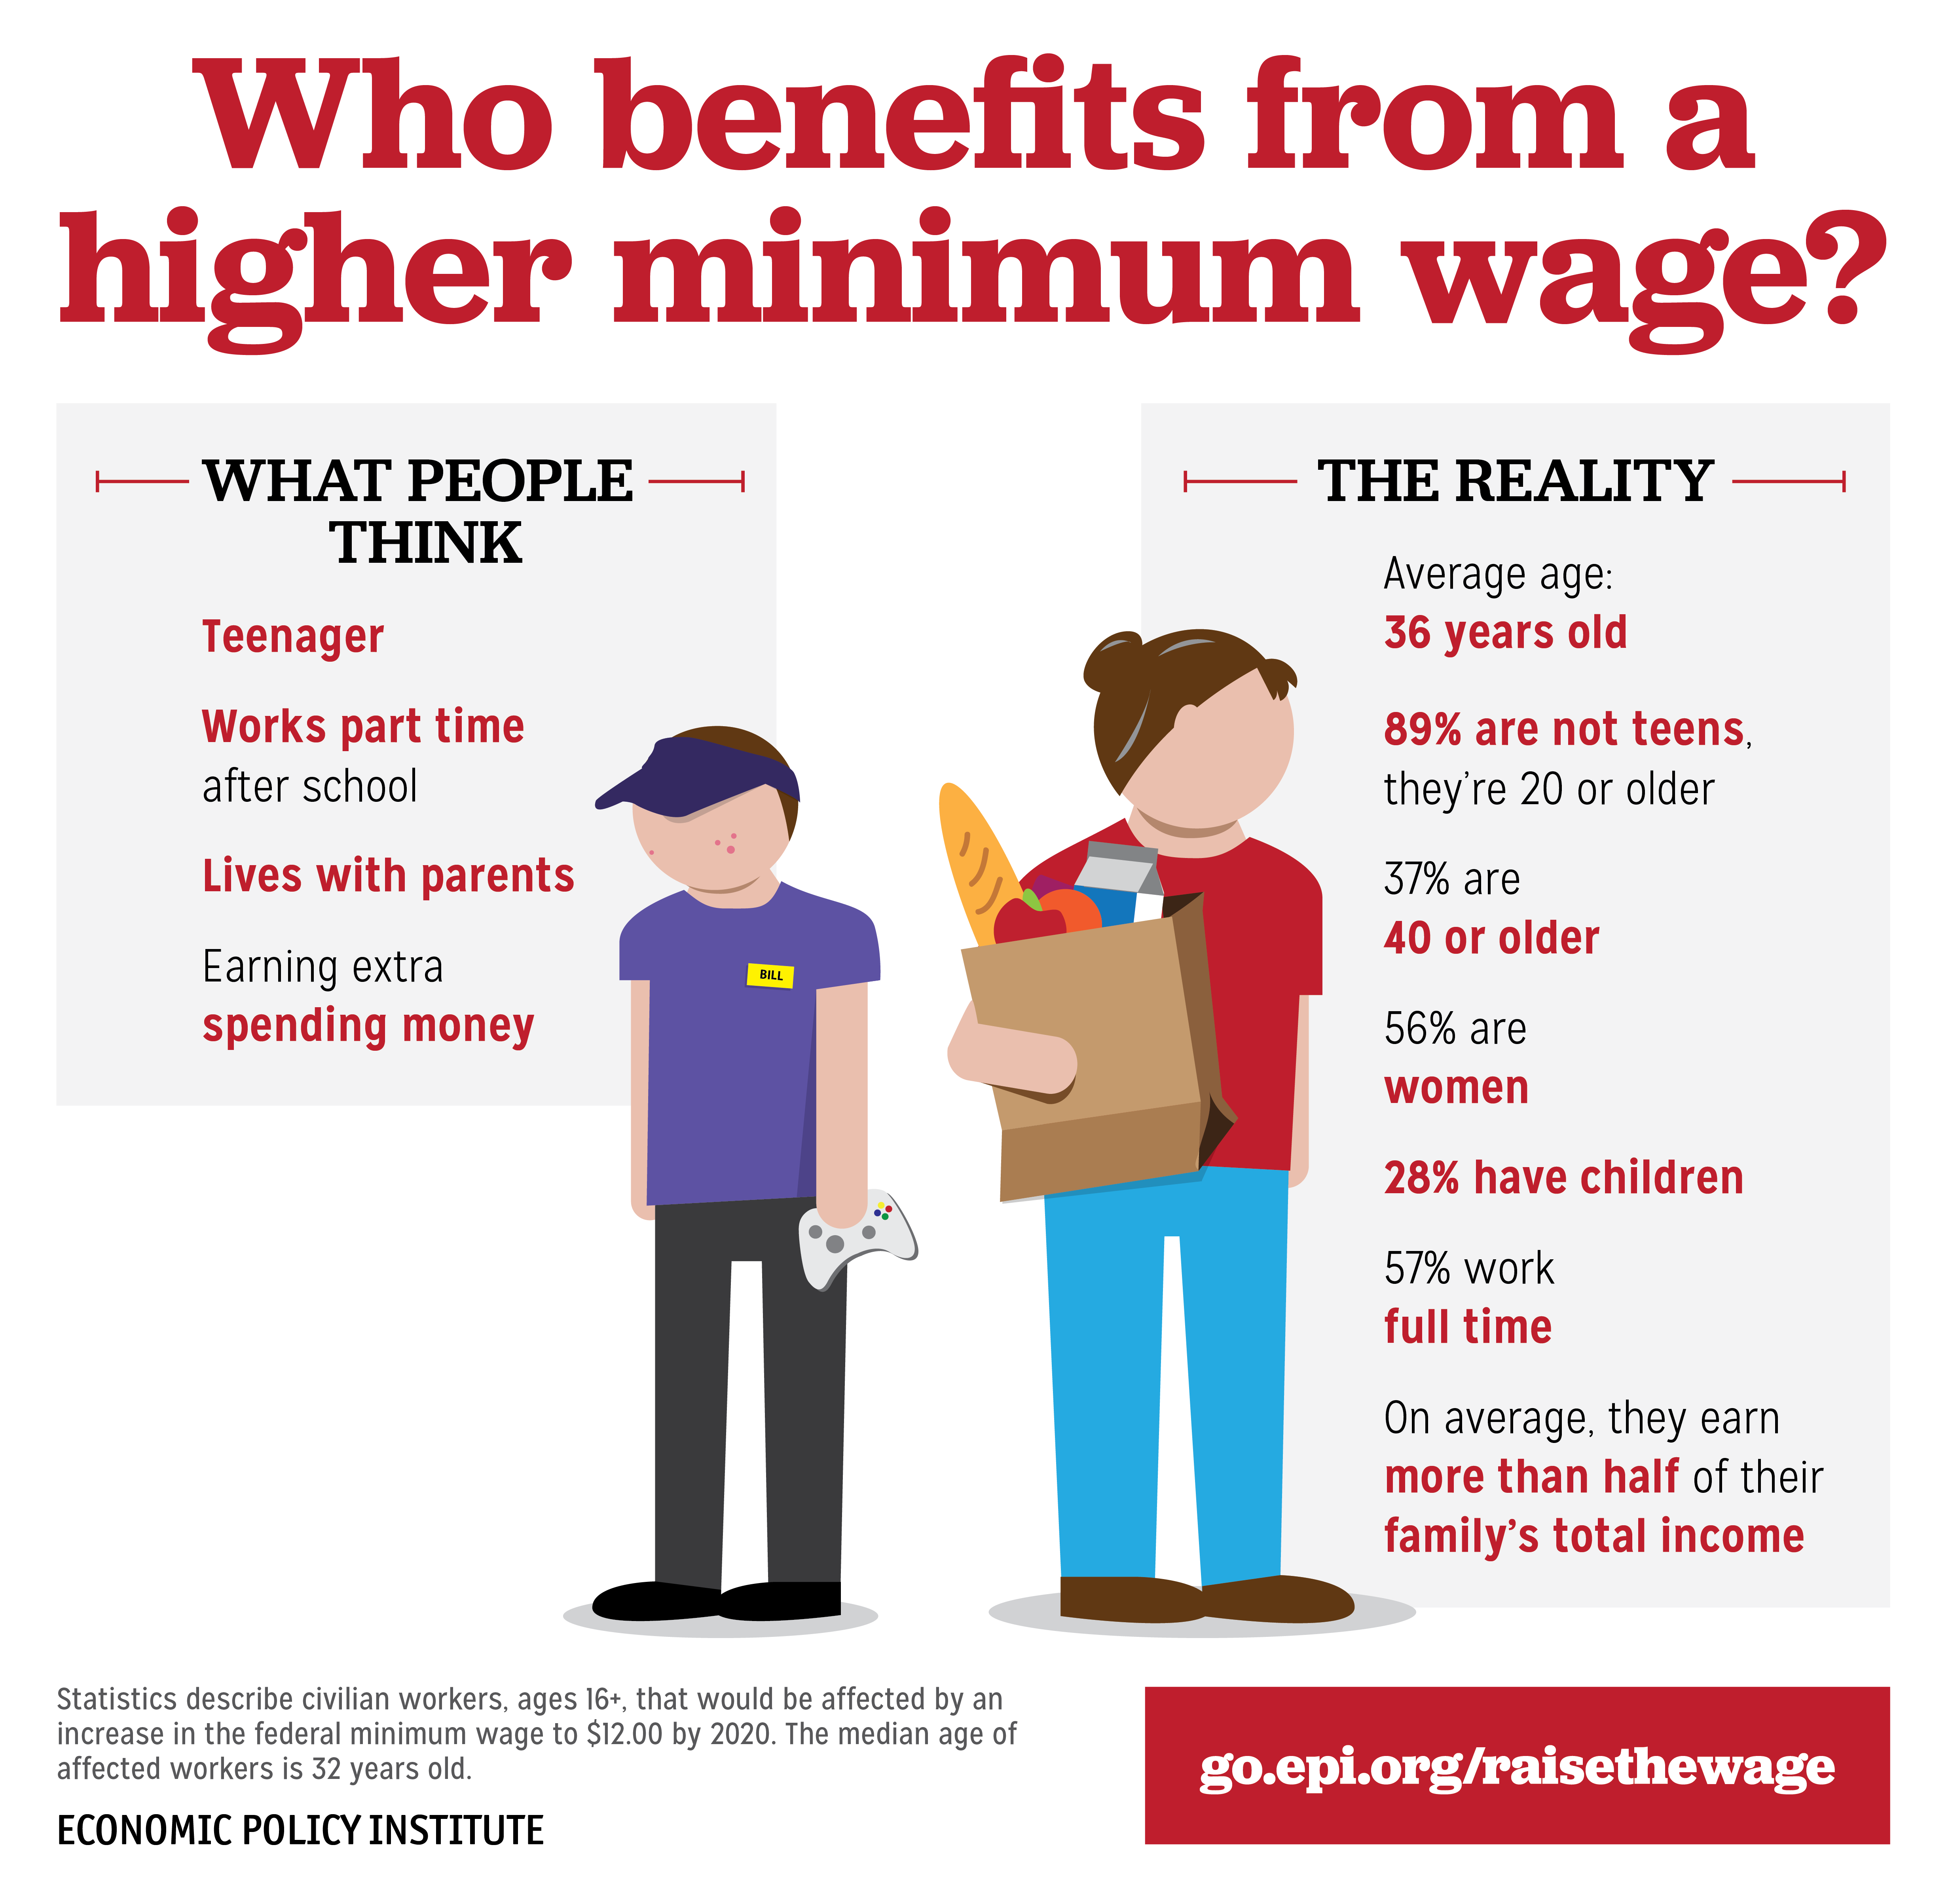
Should the minimum wage be lowered?

The federal minimum wage rate is $7.25 an hour. It applies to hourly employees and has been in place since 2009.

The states also set minimum wage rates that are above or below the federal rate, and several states have no minimum wage rate at all. In those latter states, and in those states with no minimum wage laws, the higher rate is supposed to apply.

Here are a few facts about the minimum wage:

(By Debbie Lord, Cox Media Group National Content Desk)

The Fair Labors Standards Act of 1938 established a federal minimum wage or the minimum amount a person must be paid by the hour. It was created to help stabilize the country following the Great Depression of the 1930s.

A single person under the age of 65 is considered to be living below the poverty level if they are making less than $12,486.

The act applies to around 84 percent of the U.S. labor force or 130 million workers.

The states also can set minimum wages that are above or below the federal rate. In those states the higher rate is applies.

I mention all this because my home state, Illinois, plans to raise its minimum wage to $9.25 per hour next year and to $15 per hour by 2025, and the usual controversy has begun.

Why do we have minimum wage laws?

These laws tacitly acknowledge that at the lower end of the wage scale, employees have much less negotiating power than do businesses.

These laws also acknowledge that many, if not most, businesses will pay workers as little as necessary to attract workers, and this amount frequently leaves workers in poverty.

Minimum wage is an anti-poverty effort, but like virtually all anti-poverty efforts, it is disdained by the conservative side of the political spectrum:

Ten reasons economists object to the minimum wage

Mark J. Perry @Mark_J_Perry

December 8, 2015

1. Proposed minimum wages are almost always arbitrary and never based on sound economic analysis. Why $10.10 an hour and not $9.10? Why $15 an hour and not $16 an hour?

#1 is fundamentally true, though it is a red herring, mostly because such an analysis is impossible. There are far too many too many competing variables.

Some people will benefit; some will be injured, and by varying degrees. Some businesses too, will benefit and some will not. How would the competing benefits and injuries be weighed?

But all of the above is true of most laws. Should the fine for speeding be $50 or $100? Should a jail term for a crime be 1 year or 10 years? How is that determined?

Although America has many thousands of city, county, state, and federal laws, very few are subject to “sound economic analysis,” for the same reasons as our own personal decisions seldom are subject to “sound economic analysis.” Too many competing and non-comparable variables.

2. A uniform federal minimum wage may be sub-optimal for many states, and uniform state minimum wages may be sub-optimal for many cities. A one-size-fits-all approach to the minimum wage is really a “one-size-fits-none.”

#2 also is true of most laws, particularly federal laws. But federal minimum wage law merely is a bottom, from which cities and states may deviate upwards. Image result for minimum wage

In that sense, it is more flexible than are most federal laws.

3. Minimum wage laws require costly taxpayer-funded monitoring and enforcement mechanisms, whereas market wages don’t.

All laws require monitoring of some sort. The objection really is an objection to any minimum wage laws.

Said another way, the author implies that minimum wage should be $0.

This directly contradicts his earlier objections: (#1: “Why $10.10 an hour and not $9.10?”) Why $0? What is his “sound economic analysis” that shows minimum wage should be $0?

And (#2: “A uniform federal minimum wage may be sub-optimal for many states . . .”) A $0 minimum wage surely will be “suboptimal for many states, counties and cities.”  But what prevents powerful employers from paying starvation wages to weak, desperate employees?

4. Minimum wage laws discriminate against unskilled workers in favor of skilled workers, and the greatest amount of discrimination takes place against minority groups, like blacks.

Low pay, including $0 pay, “discriminates against unskilled workers in favor of skilled workers, and the greatest amount of discrimination takes place against minority groups, like blacks.”

Again, this begs the question, what level of pay is acceptable in today’s America, or is the author suggesting we should return to slavery?

5. Adjustments to total compensation following minimum wage laws will disadvantage workers in the form of reduced hours, reduced fringe benefits, and reduced on-the-job training.

“Adjustments to total compensation following minimum wage laws in the form of reduced hours” means the people will work fewer hours for the same pay. Is this a bad thing??

6. Many unskilled workers will be unable to find work and will be denied valuable on-the-job training and the opportunity to acquire -jobexperience and skills.

On-the-job training for minimum wage jobs generally is itself, minimum, and most often is of scant value. Handing off a burger or greeting a customer at the door, does not provide valuable on-the-job training.

Again, the author does not explain what level of pay is necessary to provide that training. Presumably, no level of pay is low enough to satisfy his criteria.

7. Minimum wage laws prevent mutually advantageous, voluntary labor agreements between employers and employees from taking place.

Minimum wage employees do not have the economic power or expertise to negotiate “mutually advantageous, voluntary labor agreements.”

8. To the extent that higher minimum wages result in lower firm profits and higher retail prices, that’s a form of legal plunder by workers from employers and consumers that is objectionable.

The author may not realize it, but his #8 can be rephrased: “To the extent that any wages result in lower firm profits and higher retail prices, that’s a form of legal plunder by workers from employers and consumers that is objectionable.”

Even a 1 cent minimum wage fits that description. Once again, the author naively opts for a $0 minimum wage.

9. Market-determined wages are efficient, whereas government-mandated wages create distortions in the labor markets that prevent labor markets from clearing.

No definitions are given for “efficient,” “distortions,” and “clearing.” Is it “efficient” for a person to work 40 hours a week and still not be able to afford life’s necessities? Are markets distorted when a low-paid person makes one thousandth what a highly paid worker makes?

Similarly, when unions strike for wages and benefits, is that an example of “market-determined” efficiency?

10. Like all government price controls, minimum wage laws are distortionary. If you trust government officials and politicians to legislate and enforce a minimum wage for unskilled workers, you should logically trust those same bureaucrats to set all prices, wages and interest rates in the economy.

Realistically, if you agree that those economy-wide price controls would be undesirable, then you should also agree that the minimum wage law is also undesirable.

Forgetting for a moment that government price controls set maximums, and minimum wage sets minimums, the government already does many things to set prices on things. Medicare, for instance, one of the most popular social benefits in history, already sets maximum prices on thousands of procedures and drugs, by virtue of its compensation schedules.

Many state and local government set maximum prices on electricity, water, parking, and the largest single expense we all pay: Taxes. The notion that governments are incapable of setting a minimum on wages simply does not square with the facts.

Minimum wage laws benefit America, because allowing powerful companies to pay starvation, or even below-starvation, wages is not in the best short-term or long-term interests of America.

Minimum wage (red line) has not kept up with inflation (blue line).

The sole question is not “whether” there should be minimum wage laws, but rather “at what levels” those wages should be.

I suggest that no one ever should be paid at a poverty level.

Though all of America is subject to various levels of minimum wage, the nation’s economic growth has been impressive, while unemployment is low.

This belies the author’s contention that minimum wage laws, in of themselves, are harmful.

Of course, minimum wage laws would be much less needed if the nation adopted the “10 Steps to Prosperity, below.

The Ten Steps would cost businesses and taxpayers nothing, and would not discourage hiring.

Rodger Malcolm Mitchell

Monetary Sovereignty

Twitter: @rodgermitchell

Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The single most important problems in economics involve the excessive income/wealth/power Gaps between the have-mores and the have-less.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY