Why nations pretend not to understand Monetary Sovereignty

Preface: Monetary Sovereignty means just what it says: Being sovereign over your form of money.

The U.S. government is Monetarily Sovereign over its sovereign currency, the U.S. dollar. The federal government created the very first dollars out of thin air.

It continues to create dollars at will. Even without collecting taxes or receiving any other form of income, the federal government can pay any debt denominated in dollars. It never can run short of dollars. It can control the value of the dollar by controlling interest rates.

U.S. cities, counties, and states are monetarily non-sovereign. They have no sovereign currency. Instead, they use the U.S. dollar.

They cannot create dollars at will. They need taxes or other forms of income, in order to pay their debts. They can run short of dollars with which to pay their bills.

England is Monetarily Sovereign over the British pound. Germany is monetarily non-sovereign. It uses the euro, over which it has little control. It can run short of euros and be unable to pay its debts denominated in euros.

Japan and China are Monetarily Sovereign over their currencies. They never can run short. Italy and Greece are monetarily non-sovereign. They use the euro.

For reasons I will explain, Monetarily Sovereign nations pretend they are monetarily non-sovereign.

They pretend to borrow, when they really don’t. They collect taxes, though they have no financial need for income. They strive to export more, though increased importing would be more beneficial.

They allow poverty, though they easily could cure it. And they allow the Gap between the rich and the poor to be excessive, though they easily could cure that, too.

I mention all this because recently I read the following article excerpts:

Quantitative Easing vs. Currency Manipulation
1. In general, countries prefer their currency to be weak because it makes them more competitive on the international trade front.

A lower currency makes a countries exports more attractive because they are cheaper on the international market. For example, a weak U.S. dollar makes U.S. car exports less expensive for offshore buyers.

2. Secondly, by boosting exports, a country can use a lower currency to shrink its trade deficit.

3. Finally, a weaker currency alleviates pressure on a country’s sovereign debt obligations.

After issuing offshore debt, a country will make payments, and as these payments are denominated in the offshore currency, a weak local currency effectively decreases these debt payments.

Consider the Monetarily Sovereign United States. It has the unlimited ability to create U.S. dollars.

Exports are a method by which the U.S.  sends goods and services, created by the natural assets and labor of its citizens, to a foreign nation, in exchange for dollars.

The article says countries wish to make exports more attractive and shrink their trade deficit. But why?

It’s easy to understand why a monetarily non-sovereign nation, like Portugal for instance, would want to acquire money in exchange for natural assets. To Portugal, which uses the euro, money is in limited supply.

Portugal needs income to pay its bills.

To all nations, natural assets are limited; labor is limited. But to the U.S., dollars are unlimited. The U.S. needs no income to pay its bills.

Why should the U.S. exchange its limited assets to gain an asset of which it has an unlimited supply?

A common answer is that U.S. exports help U.S. businesses grow and profit, and with those profits, pay employees. But the answer is illogical.

“Grow and profit” means to acquire dollars, of which the federal government has an unlimited supply.

The easier and more sensible plan would be for the federal government to do what businesses are designed to do, i.e. provide dollars to employees. This would cost the government nothing (remember that unlimited money supply), and more importantly, no scarce natural resources would be expended.

One such method would be to implement the Ten Steps to Prosperity. (See below.)

The article says,

“A weaker currency alleviates pressure on a country’s sovereign debt obligations.

“After issuing offshore debt, a country will make payments, and as these payments are denominated in the offshore currency, a weak local currency effectively decreases these debt payments.”

The whole idea is illogical and factually wrong.

First, federal so-called “debt” actually is nothing more than deposits into Treasury security accounts. When you “lend” to the federal government, you don’t really lend. You make a deposit into your T-bill, T-note, or T-bond account at the Federal Reserve Bank.

Your dollars remain in your account, gathering interest, until your account matures, at which time your dollars are returned to you. Your dollars never leave your account until maturity.

The exchange rate of those dollars is irrelevant. Whether a dollar is worth one pound, two yen, or three partridges in a pear tree makes no difference. To pay off the misnamed “debt.” the government returns whatever is in your account.

The federal government does not use your dollars, but even if it did, giving you your money back would be no burden on a government that has the unlimited ability to create its own sovereign currency.

Third, making a currency weaker is inflationary because imported goods instantly become more expensive. (Fortunately, the U.S. government has the unlimited ability to strengthen the dollar, simply by increasing interest rates.)

This increases the demand for dollars, which makes them more valuable.

Bottom line:

  1. Increasing the level of exports does not benefit a Monetarily Sovereign government
  2. Shrinking the trade deficit similarly does not benefit a Monetarily Sovereign government
  3. Federal “debt” and federal finances are substantially different from personal (monetarily non-sovereign) debt an finances. Unlike you and me, the Monetarily Sovereign federal government needs no income, can produce dollars at will, can control the value of those dollars, and never can run short of dollars.

Why then does the federal government pretend dollars are scarce to it? Why does it pretend that total deposits in T-security accounts are a burden and a threat? Why the claim that a trade surplus is superior to a trade deficit.

United States Balance of Trade
For the past 10 years the U.S. has run persistent trade deficits.

For the past 10 years the U.S. has run persistent trade deficits. During that same period, Gross Domestic Product has risen from $14.5 trillion, to $21.3 trillion, a massive 47% increase.
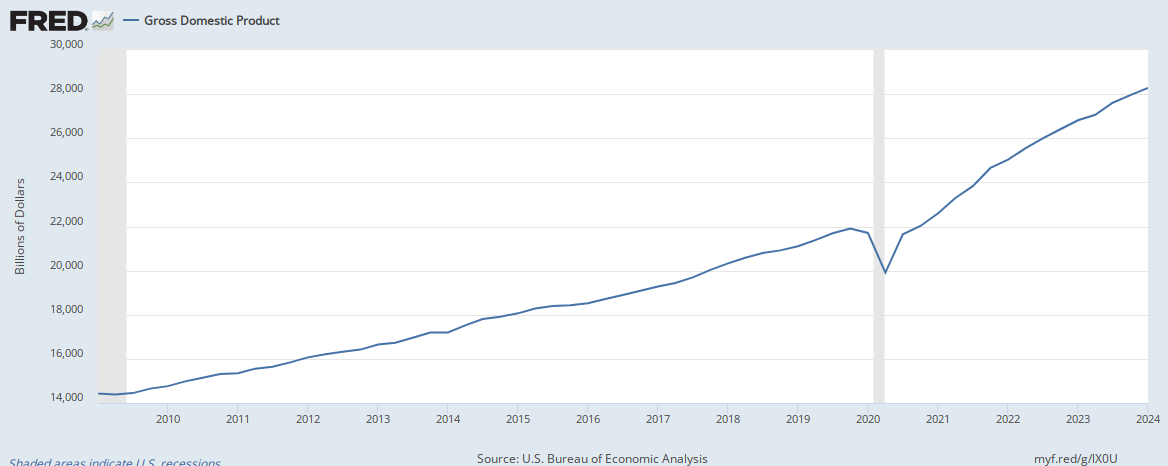
In the past 10 years, GDP has risen from $14.5 trillion, to $21.3 trillion, a massive 47% increase.

Clearly, trade deficits have not prevented GDP growth. The reason is that federal deficit spending has more than made up for the dollar loss trade deficits cause.

And that is the whole point and the reason why trade deficits do not harm a Monetarily Sovereign nation. Any dollar loss easily is overcome by federal deficit spending.

The question then is, “Why do nations pretend not to understand Monetary Sovereignty?” Why everywhere you turn, do your information sources — the politicians, the media, the economists — tell you that the federal deficit and debt are so high as to be “ticking time bombs“?

The answer is this: The rich run America.

“Rich” is a comparative word. The farther distant one is from the poor the richer one is.

Owning a million dollars makes one rich if everyone else owns one dollar. Owning a million dollars does not make one rich if everyone else also owns a million dollars.

Being “rich” depends on the Gap between the rich and the rest.  To be richer, the rich want to widen the Gap between the rich and the rest. That is called, “Gap Psychology.”

So:

–The rich bribe the politicians via campaign contributions and promises of lucrative employment when their political careers end.
–The rich bribe the media via advertising dollars and via ownership.
–The rich bribe the economists via gifts to their universities and employment in “think tanks.”

The rich do not want you to learn that the federal government has the unlimited ability to provide you with free medical care, free schooling, fine housing, food and clothing, and the other benefits that the rich receive.

The rich don’t want you to know you can have all these benefits, without paying a penny in taxes.

If you understood that you could have a much better life, you naturally would want it. But, that would narrow the Gap between the rich and the rest. And narrowing the Gap would make the rich less rich.

So, in addition to trying to gather more for themselves, the rich also want you to have less, thus widening both sides of the Gap.

We’ll finish with a few excerpts from an article in the TILJournal,  a massive exercise in ignorance, demonstrating the point:

The National Debt: America’s Ticking Time Bomb
By D.T. Osborn
Each taxpayer in America owes approximately 250,000 dollars to places including China through its state-controlled institutions of finance. Here comes the worst news of all; 22 trillion is only a small part of the real National Debt.

That’s because the official dollar amount does not include America’s unfunded liabilities. Unfunded liabilities are those items the Federal government must pay for by American law.

By far the largest and most significant of these are Social Security, Medicare, and Medicaid. Together they currently total more than 50 trillion dollars. When added to the Debt, the total becomes slightly more than 73 trillion dollars… for the moment.

The final figure also includes items such as Federal pensions for workers and elected officials and interest paid on the Debt. The grand total of America’s real debt is about 130 trillion dollars!

This means each American taxpayer owes over 1 million dollars of the real debt as it exists today. So, what do you say, fellow taxpayer? Got an extra million to chip in for poor old Uncle Sam? Yeah, me neither.

This is a path which will lead to the eventual bankruptcy of America.e

And that lie, that you owe someone over 1 million dollars, is the ridiculous scare tactic being fed to you and the rest of the American public. It wrongly assumes that federal financing is similar to personal financing.

It isn’t.

Personal financing requires a person must have some form of income — salary, interest, borrowing, inheritance, etc. — in order to acquire the dollars with which to pay his bills. That is known as “monetary non-sovereignty.”

By contrast, the federal government is Monetarily Sovereign. It needs no form of income — not even taxes — because it has the unlimited ability to create its own sovereign currency, the U.S. dollar, to pay an infinite number of bills.

Former Federal Reserve Chairman, Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency.”

Former Federal Reserve Chairman, Ben Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”

St. Louis Federal Reserve: “As the sole manufacturer of dollars, whose debt is denominated in dollars, the U.S. government can never become insolvent, i.e., unable to pay its bills. In this sense, the government is not dependent on credit markets to remain operational.

And here, in one sentence, By author D.T. Osborn expresses the big lie the rich want you to believe:

“Any real solution to stave off national insolvency requires massive changes in how unfunded liabilities are handled.”

The rich want the federal government to cut Social Security, cut Medicare, and cut Medicaid, thus widening the Gap between the rich and the rest.

That is how they make themselves richer.

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The most important problems in economics involve the excessive income/wealth/power Gaps between the richer and the poorer.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded Medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY


Dumb, dumber and dumbest: Cavuto, Bartiromo and Dobbs

When dumb, dumber and dumbest battle, it’s difficult to know which is which. For example:

Fox News Host Neil Cavuto Tells Viewers Trump Is Wrong: ‘China Isn’t Paying These Tariffs. You Are.’

President Trump said, “Remember this, our country is taking in billions and billions of dollars from China. Out of that many billions of dollars, we’re taking a part of it and giving it to the farmers because they’ve been targeted by China. The farmers, they come out totally whole.” 

Neil Cavuto pointed out that, once again, Trump was not telling the truth when it came to who pays for tariffs.

“I don’t know where to begin here,” the Fox News host said. “Just to be clarifying, China isn’t paying these tariffs. You are. You know, indirectly and sometimes directly.”

“It’s passed along to you through American distributors and their counterparts in the United States that buy this stuff from the Chinese and have to pay the surcharges. Not the Chinese government.”

Cavuto said that this latest round of tariffs “will be felt by consumers directly.”

As usual, Trump is lying, stupid, or both. And Cavuto is correct. Tariffs on foreign goods are paid by the purchasers of those goods.

As ignorant as Trump is, it simply is not possible that he doesn’t understand this. The man is surrounded by advisors, and surely there is someone in the White House who has told him that basic fact.

Then again, considering the bigots, liars, incompetents, crooks, and sycophants (BLICS) with whom Trump has surrounded himself, we can’t be sure of anything that goes on in Crazyland.

Trump wins round 1 of the dumb, dumber, dumbest contest by default. Cavuto didn’t even compete.

Now we come to round 2:

Lou Dobbs Lashes Out at Fox Business Host Who Confronts Him About Trump’s Exploding DebtBy Justin Baragona

Cavuto groused that both political parties had abandoned “any hint of fiscal restraint.” Cavuto bashed the Trump administration for having “not done a good job containing” federal spending rates.

“Well, somebody has done a good job and that is President Trump,” Lou Dobbs, a rabidly pro-Trump primetime host, shot back. “And it is this economy.”

Cavuto then directly confronted Dobbs, asking him if he truly believes Trump has done a good job “reining in spending,” prompting Dobbs to dismissively tell his colleague that he has to “work this thing out with the president.”

“Fact, fact, do you think this president has done anything to contain the deficits and the debt that had spiraled, still, from what levels he had from Barack Obama?” Cavuto fired back.

“Uh-huh. I do, indeed,” Dobbs said in response, prompting Cavuto to demand specifics. Dobbs ended up lashing out at Cavuto instead.

Cavuto: “I asked you a question about the debt! Do you worry about that or not? ”

Later on in the segment, following the Dobbs-Cavuto clash, pro-Trump colleague Maria Bartiromo insisted that Trump would absolutely “take a knife to spending” if he gets a second term in office. “Mark my words.”

Now we have a three-way dumb, dumber, dumbest contest.

First, Cavuto talks about “financial restraint” and Trump “not having done a good job containing” federal spending rates. This is dumb.

Federal deficit spending adds dollars to the economy, which are necessary for economic growth. Reductions in deficit growth lead to recessions, and increases in deficit growth cure recessions.

When federal deficit growth (red line) declines, we have recessions (vertical gray bars), which are cured by increased deficit growth.

Further, reductions in debt lead to depressions. Every depression in U.S. history has been caused by debt reductions:

1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807.
1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819.
1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837.
1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857.
1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873.
1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893.
1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929.

The reason is obvious: To reduce the federal debt requires increasing federal taxes and/or reducing federal spending, both of which take dollars out of the private sector (aka “the economy.”)

It is functionally and mathematically impossible to grow an economy (or even to keep it level) by taking dollars out of the private sector.

Dobbs responded to Cavuto’s question by claiming that Trump has done something to contain the deficits and the debt.

This is dumber.

“Containing” deficits and debt always lead to recessions if we are lucky, and depressions if we are not.

Finally, Maria Bartiromo chimed in by saying, “Trump would absolutely take a knife to spending” if he gets a second term in office.

This is dumb for two reasons:

  1. Trump has no reason to cut spending. The Republicans don’t want cuts. The Democrats don’t want cuts. The voting public really doesn’t want cuts (in the programs they like). And Trump loves spending, especially spending money that isn’t his.
  2. If Trump cut spending, the economy would tank, and Trump would see that happening, and he would panic.

So I judge the contest this way:

Neil Cavuto: Dumb
Maria Bartiromo: Dumber
Lou Dobbs: Dumbest

Dobbs wins not only because Cavuto was correct about tariffs, but because of Dobbs’s blind loyalty to a fool, and because Dobbs could not bring himself to answer Cavuto’s simple question.

Bartiromo didn’t say enough to win, but what little she said, earned her 2nd prize.

Of course, in any such contest, Trump always will win hands down. He’s a professional fool among amateurs.

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The most important problems in economics involve the excessive income/wealth/power Gaps between the richer and the poorer.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded Medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY

“There’s No Such Thing as ‘Free Money.'” Yes, there is, Mr. Greenhut.

Economics is a unique science.

It is the only science in which people who have no background, no education, no history, and no knowledge, feel absolutely confident in their opinions about it.

I’m sure they don’t feel confident in arguing about quantum mechanics or about relativity, or about rocket science, but when it comes to economics, everyone is an “expert” — often a laughable expert with a way-too-loud megaphone.

I suggest Steven Greenhut is one such “expert.” Here are excerpts from his recent article:

There’s No Such Thing as ‘Free Money’ or Meaningless Deficits
STEVEN GREENHUT, Reason Magazine

Vice President Dick Cheney famously said that “deficits don’t matter.”

Such conservatives weren’t interested in using federal spending to fight poverty and inequality, but they didn’t want growing deficits to curtail their military efforts in Iraq or quash their desire to step up tax cuts.

Greenhut is 100% correct about the motivations of the conservative right.

Cheney’s ideological heirs now argue that deficits are fine as long as interest rates are low and the Gross Domestic Product keeps growing.

Deficits not only are “fine,” but deficits are absolutely necessary for economic growth, and this has nothing to do with low interest rates.

Federal deficits add dollars to the economy. It is functionally impossible for an economy to grow, without the money supply growing.

In fact, the formula for Gross Domestic Product, our most common measure of economic growth, is a money measure.

GDP = Federal and Non-federal spending + Net Exports

When federal deficit spending doesn’t grow, the economy doesn’t grow. Reduced deficits cause recessions, and increased deficits cure recessions, as the following graph demonstrates:

Recessions (vertical gray bars) begin with reduced deficits; they are cured by increased deficits.

Sorry, but deficits and debt do matter.

There’s no short-term crisis, for sure, but debt “will depress economic growth over time and could potentially lead to a fiscal crisis if borrowers lose faith in the country’s ability to pay,” explained Yuval Rosenberg in The Fiscal Times.

Federal “debt” is nothing more than deposits into Treasury security accounts (T-bills et al).  The government pays back the “debt” every day simply by returning the dollars in those accounts.

And what does this phrase mean, “borrowers lose faith in the country’s ability to pay.”? Makes no sense, unless he means “lenders lose faith . . . ”

Even then, the federal government does not borrow. It accepts deposits into T-security accounts and it never touches those dollars.

The federal government, being Monetarily Sovereign, creates all the dollars it needs, ad hoc, each time it pays a creditor. The government never has any difficulty returning those dollars to the account holders.

See: It is 2019, and the phony federal debt “time bomb” still is ticking. Thursday, Jan 24 2019.

Periodically, I remind you about a disaster that was considered to be so imminent, it repeatedly was referred to as a “ticking time bomb.” I have evidence of the warning as early as 1940, and then every year thereafter.

I’m talking about the federal debt that not only was said to be a “ticking time bomb,” but “unsustainable” and “the time bomb of doom“!

Year after year, that time bomb of doom has kept ticking, and here we are, in 2019, with a  healthy economy, and still that bomb hasn’t exploded. Eighty years of warnings, eighty years of being wrong, eighty years, and people still believe the doomsday sayers.

The phony “time bomb” began to “tick” back in 1940, when the total debt was $40 Billion. Today, 80 years later, it has risen 52,500% (!) to $21 Trillion, and still it ticks.

Go to the above reference, and you’ll see that year, after year, after ridiculous year, “experts” like Greenhut repeatedly referred to the federal debt as a “ticking time bomb.”

Wrong for 80 consecutive years.

Continuing with his article:

Furthermore, he (Rosenberg) notes, debt hampers government’s ability to react to real emergencies “such as recessions, wars or natural disasters.”

As debt soars, federal payments to service the debt will crowd out the government’s core spending responsibilities.

The above is a perfect example of closing one’s eyes and ignoring the reality standing before one.

Here we are, looking at 80 past years of a dramatically increasing debt (deposits), and the federal government’s continual “ability to react to real emergencies “such as recessions, wars or natural disasters.”

Since 1940, America has fought dozens of wars, all over the world, had numerous recessions, and dealt with all manner of natural disasters. And today, the nation is wealthier than ever.

Explain that Messrs. Rosenberg and Greenhut.

In a way, these denials-of-the-obvious remind me of Mohammed Saeed al-Sahhaf  (aka “Baghdad Bob”). He was the Iraqui, who during Desert Storm, kept going on television to deny that American tanks were in Baghdad, while they were visible over his shoulder.

Rosenberg’s and Greenhut’s comments are that ridiculous.

And now for the source of their ignorance: They don’t understand the differences between personal financing and federal financing.

You could borrow an immense amount of money to upgrade the kitchen and take Hawaiian vacations and then claim that it doesn’t matter as long as you can cover the monthly interest payment.

But that’s a road to eventual ruin.

The federal government is Monetarily Sovereign, meaning it is sovereign over the dollar.

At the beginning of this nation’s existence, our new federal government created laws, and those laws gave the government the unlimited ability to create U.S. money.

So the government created millions of U.S. dollars — from thin air.

So long as those laws and others like them, exist, the federal government will continue to have the unlimited ability to create U.S. dollars.

Here’s how they do it:

To pay a creditor, the federal government sends instructions (not dollars) to the creditor’s bank, instructing the bank to increase the balance in the creditor’s checking account.

At the moment the bank obeys those instructions, brand new dollars are created.

So long as the federal government doesn’t run out of instructions, it won’t run out of dollars.

You and I don’t have this ability. Neither do our cities, counties, and states. And neither do France, Germany, and Italy, all of which don’t have a sovereign currency, but rather use the euro.

All are monetarily non-sovereign.

Ask Messrs. Rosenberg and Greenhut what “Monetary Sovereignty” means, and they won’t have a clue, even though it is the basis for modern economics.

Now we get to what Greenhut thinks is absolutely necessary and what he thinks, isn’t:

Some debts can’t be helped—e.g., capital expenses—but look at the nonsense that our massive federal budget is funding.

Easy debt drives easy spending. It enables our government to do things it shouldn’t do, such as wage unnecessary wars and create boondoggles like the Green New Deal or a space force.

Which capital expense “can’t be helped,” Mr. Greenhut? Building a wall on our southern border? Buiding cages to house children we have taken from their parents?

Which wars are “unnecessary” and which are necessary?

And as for the “Green New Deal,” it describes the various efforts to reduce climate change. To you, that’s a boondoggle?

We’ll end with Greenhut’s final bit of nonsense:

Deficit spending creates constant pressure for tax hikes. We shouldn’t spend what we don’t have.

“Constant pressure for tax hikes”???? You mean the recent tax cuts, that came with the billions in increased deficit spending?

Will someone please contact Messrs. Greenhut and Rosenbert with the facts so that they don’t continue to make fools of themselves.

It would be the charitable thing to do.

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The most important problems in economics involve the excessive income/wealth/power Gaps between the richer and the poorer.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded Medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY


Congress re. Medicare and the deficit: The easy we make impossible, but it takes longer

We already have created Medicare for seniors. The hard work was accomplished years ago. And in those years since, we have accumulated excellent knowledge in how to run a Medicare program.

Now, to create Medicare for All, we need only to do three simple things:

I. Eliminate FICA
The U.S. federal government is Monetarily Sovereign. It has the unlimited ability to create its sovereign currency, the U.S. dollar.

Unlike state and local governments, the federal government never can run short of dollars. Even if all federal tax collections fell to $0, the federal government could continue spending and paying its bills, forever.

Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency.”
Ben Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”
St. Louis Federal Reserve: “As the sole manufacturer of dollars, whose debt is denominated in dollars, the U.S. government can never become insolvent, i.e., unable to pay its bills. In this sense, the government is not dependent on credit markets (borrowing) to remain operational.”

Contrary to the popular myth, FICA does not fund Medicare. The dollars collected for FICA (and indeed, all federal tax dollars) are destroyed by the U.S. Treasury upon receipt.

The federal government creates brand new dollars, each time it pays a creditor.

And lest you believe increased deficit spending (necessitated by the elimination of FICA) would cause inflation, history says that is not so.

Federal deficit spending (red) does not cause inflations (blue)

Most inflations and all hyperinflations have been caused by shortages, (usually shortages of food and/or energy), not by excess money. These shortages often are caused by insufficient federal deficit spending.Image result for german money in a wheelbarrow

The “money-in-a-wheelbarrow” meme demonstrates a government’s response to inflation, not the cause of inflation.

1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807.
1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819.
1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837.
1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857.
1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873.
1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893.
1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929.

II. Expand Medicare to include all age groups. This does not require a fundamental change, but rather an expansion of the already existing program, so that it covers everyone.

III. Make it more inclusive by removing deductibles and covering long-term care. The theoretical purpose of deductibles is to dissuade people from over-using Medicare.

But because Medicare costs taxpayers nothing, even possible over-use would pump growth dollars into the economy — a benefit to all Americans.

Further, long-term care eventually is needed by a high percentage of people, but it is unaffordable for many. Having the federal government pay would remove a great burden from most American families.

I was reminded of the above by the following article that appeared in the 8/1/19 Chicago Tribune (excerpts follow).

Many in GOP-led Senate torn over pact to boost debt limit
By Andrew Taylor Associated Press

WASHINGTON — A hard-won, warts-and-all budget pact between House Speaker Nancy Pelosi and President Donald Trump is facing a key vote in the GOP-held Senate, with many conservatives torn between supporting the president and risking their political brand with an unpopular vote to add $2 trillion or more to the government’s credit card.

Credit cards are, for you and me, a method of short-term borrowing. But unlike you and me, and state/local governments,  the federal government does not borrow.

Given its unlimited ability to create dollars, it has no reason to borrow dollars. What often and misleadingly is termed federal “borrowing,” actually is the acceptance of deposits into Treasury-security (T-bill, T-note, T-bond) accounts.

The federal government, being Monetarily Sovereign has no need for the dollars in those accounts, so does not touch them. Rather, the dollars remain in the accounts until maturity, at which time they, together with interest, are returned to the depositor.

The purposes of T-securities are to:

  1. Provide a safe depository for unused dollars, which stabilizes the dollar, and
  2. Assist the Fed in controlling interest rates.

They do not help the federal government pay its bills.

The Trump-supported legislation backed by the Democratic speaker would stave off a government shutdown and protect budget gains for the Pentagon and popular domestic programs.

It’s attached to a must-do measure to lift the so-called debt limit to permit the government to borrow freely to pay its bills.

The so-called debt limit is akin to burning your wallet to prevent you from paying your exisiting creditors. It is not “financial prudence,” as many politicians would have you believe.

The vote, expected Thursday, is a politically tough one for many Republicans.

The tea party-driven House GOP conference broke against it by a 2-1 ratio, but most pragmatists see the measure as preferable to an alternative fall landscape of high-wire deadlines and potential chaos.

The government otherwise would face a potential debt default, an Oct. 1 shutdown deadline, and the return in January of across-the-board spending cuts known as sequestration.

Hmmm . . . The choice is between high-wire deadlines, potential chaos, debt default, an Oct. 1 shutdown, and sequestration,  vs. simply eliminating the useless debt ceiling.

For new arrivals to the Senate, particularly those who ran against a broken Washington culture, the sweeping measure represents a lot of what they ran against: unrestrained borrowing and trillion-dollar deficits, fueled by a bipartisan thirst for new spending.

“Unrestrained borrowing” does not exist, simply because the federal government (unlike state and local governments) does not borrow.Image result for nasa

“Trillion-dollar deficits” add trillions of growth dollars to the economy.

“New spending” is the method by which the federal government benefits Americans via spending for the military, health-care, anti-poverty efforts, science and technology, education,, anti-global warming, medical advances, national parks, disaster recovery, and the myriad other benefits we Americans expect and rely upon.

“This budget process, if we can even call it a process, put taxpayers at the mercy of a House speaker who has no interest in prudent budgeting,” said freshman Sen. Josh Hawley, R-Mo.

State and local taxpayers fund state and local government spending. But, contrary to popular myth, federal taxpayers do not fund federal spending.

To cut federal growth spending is not “prudent.” It demonstrates ignorance of federal financing and national needs.

Rand Paul, R-Ky., said the deal “marks the death of the tea party movement in America.”

Good riddance to the tea party, the party of austerity and hatred of the poor and middle-classes.

The pact is a victory for pragmatists eager to avert chaos caused by a potential government shutdown, a possible debt crisis, or a freeze to agency budgets — including the massive Pentagon budget — at current levels.

The agreement lifts the limit on the government’s $22 trillion debt for two years and averts the risk of the Pentagon and domestic agencies from being hit with $125 billion in automatic spending cuts that are the last gasp of the 2011 Budget Control Act.

Every debt crisis ends the same way: After ignorant statements about faux “prudence,” and ignorantly equating federal finances to personal finances, and falsly claiming that federal taxpayers will foot the bill, Congress and the President agree on a temporary fix.

This assures that, having learned nothing and proved nothing, Congress will expose the public to the same ignorance and chaos a few more months down the line.

And these are the people to whom we trust our futures.

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereigntyFacebook: Rodger Malcolm Mitchell

…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..

The most important problems in economics involve the excessive income/wealth/power Gaps between the richer and the poorer.

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics.

Implementation of The Ten Steps To Prosperity can narrow the Gaps:

Ten Steps To Prosperity:

1. Eliminate FICA

2. Federally funded Medicare — parts a, b & d, plus long-term care — for everyone

3. Provide a monthly economic bonus to every man, woman and child in America (similar to social security for all)

4. Free education (including post-grad) for everyone

5. Salary for attending school

6. Eliminate federal taxes on business

7. Increase the standard income tax deduction, annually. 

8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.

9. Federal ownership of all banks

10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 

The Ten Steps will grow the economy, and narrow the income/wealth/power Gap between the rich and you.

MONETARY SOVEREIGNTY