Is USAFacts honest?

Here is what USAFacts says about itself:

USAFacts is nonpartisan; our data comes exclusively from government sources, and our analysis is reliable and credible by design

Here is what USAFacts says about federal “debt”

The federal government had $38.5 trillion in debt as of 2025. If you can’t wrap your mind around that number (which is understandable), it comes out to about $112,700 per person. When the federal government spends more than it brings in, a budget deficit occurs. The government then borrows money by selling bonds and other securities to cover the deficit. Generally, the federal debt is an accumulation of budget deficits over time. So, how has the debt changed?

Wrong. The federal government never borrows dollars. It has the infinite ability to create dollars. It never can run short of dollars, Even if the government stopped collecting taxes, it could continue to pay its bills, forever.

Who says so?

Alan Greenspan, Former Federal Reserve Chairman: “A government cannot become insolvent with respect to obligations in its own currency. There is nothing to prevent the federal government from creating as much money as it wants and paying it to somebody. The United States can pay any debt it has because we can always print the money to do that.”

Ben Bernanke, Former Federal Reserve Chairman: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost. It’s not tax money… We simply use the computer to mark up the size of the account.”

Beardsley Ruml, former Chairman of the Federal Reserve Bank of New York . “The necessity for a government to tax in order to maintain both its independence and its solvency is true for state and local governments, but it is not true for a national government. All federal taxes must meet the test of public policy and practical effect. The public purpose which is served should never be obscured in a tax program under the mask of raising revenue.”

Federal Reserve Chairman, Jerome Powell: “As a central bank, we have the ability to create money digitally.”

Statement from the St. Louis Fed: “As the sole manufacturer of dollars, whose debt is denominated in dollars, the U.S. government can never become insolvent, i.e., unable to pay its bills. In this sense, the government is not dependent on credit markets (i.e. borrowing) to remain operational.”

Paul O’Neill, “I come to you as a managing trustee of Social Security. Today we have no assets in the trust fund. We have promises of the good faith and credit of the United States government that benefits will flow.”

Paul Krugman, Nobel Prize–winning economist: “The U.S. government is not like a household. It literally prints money, and it can’t run out. The government can always finance its spending by creating money.”

Eric Tymoigne (Economist) “A sovereign government does not need to collect taxes or issue bonds to finance spending. It finances directly through money creation.”

Continuing:

The federal debt grew to $39 trillion by April 2026, 4% higher than April a year prior after adjusting for inflation, and 36% higher than in 2019.

Federal debt per person has increased at an average rate of 5% annually since 2001.

The federal debt isn’t the same as personal debt. Federal debt merely is the total of deposits into Treasury accounts. These accounts are owned by depositors. They are paid off by transferring depositors’ dollars from their T-accounts to their private bank accounts.

This is not a burden on the federal government or on taxpayers.

In short, paying off federal debt is similar to you transferring your money from your checking account to your  bank savings account at the same bank..

Continuing: 

Analyzing debt relative to gross domestic product (GDP) makes it easier to track debt alongside economic and inflationary changes. It can also indicate the nation’s ability to repay its debt. When gross debt reaches 100% of GDP, it indicates that the country owes as much as its economy generates annually.

Totally false. The debt/GDP ratio has absolutely nothing to do with the nation’s ability to pay its debts. Because the federal government has the infinite ability to create dollars, it has the infinite ability to pay its debts.

If the federal government received a legitimate invoice from a creditor for $100 Trillion this morning, it could  pay it this afternoon simply by pressing a few computer keys. No taxpayer dollars would be involved.

Continuing:

In a dataset dating back to 1980, debt first surpassed 100% of the nation’s GDP in the fourth quarter of 2012. (Gross debt includes money the government borrows from itself plus debt held by the public, meaning Federal Reserve, US households and businesses, and foreign entities. Gross debt’s)

The nation’s debt as a percentage of GDP reached a peak of 133% in the second quarter of 2020. As of Q4 2025, the debt-to-GDP ratio was 123%.

The oft-quoted ratio is meaningless for a Monetarily Sovereign nation like the U.S. So-called “debt” is the total of T-security deposits. GDP is total national spending. There is no meaningful relationship between those deposits and national spending.

Continuing:

The government must pay interest on its debts just as people pay interest on credit card bills, for example. Debt interest payments comprised 13.8% of government spending in fiscal year 2025 — nearly $1 trillion. Interest payments change based on the debt’s balance and current interest rates.

Translation: The federal government, having infinite money, added nearly $1 trillion in growth dollars to the economy. Whenever the government fails to add sufficient dollars, we have recessions and depressions:

1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807.
1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819.
1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837.
1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857.
1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873.
1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893.
1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929.
1997-2001: U. S. Federal Debt reduced 15%. Recession began 2001.

As the following graph shows, reduced federal debt growth results in reduced economic growth

Sadly, the USAFacts authors do not understand the differences between federal (Monetarily Sovereign) financing and personal financing.


Rodger Malcolm Mitchell

Monetary Sovereignty

Twitter: @rodgermitchell

Search #monetarysovereignty

Facebook: Rodger Malcolm Mitchell;

MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell;

https://www.academia.edu/

……………………………………………………………………..

A Government’s Sole Purpose is to Improve and Protect The People’s Lives.

MONETARY SOVEREIGNTY
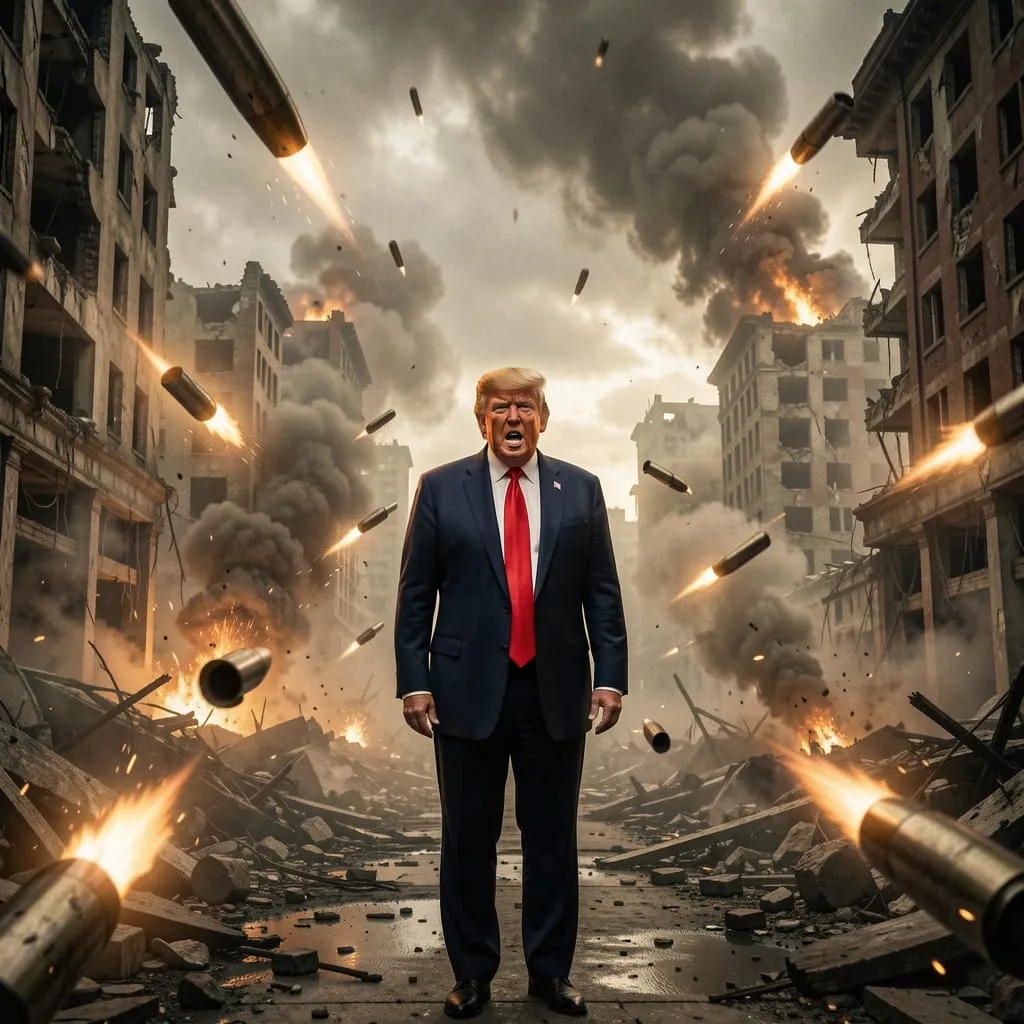
What war?

STATEMENTS FROM OUR DEAR LEADER

There will be no deal with Iran except UNCONDITIONAL SURRENDER!

The U.S. objective is to destroy Iran’s missile capabilities

The objective is annihilating their navy

The objective is ensuring Iran can never obtain a nuclear weapon

A massive Armada is heading to Iran.

Regine change would be the best thing that could happen.

When we are finished, take over your government.

We had no wars under my administration

I never promised no wars

I didn’t guarantee there would be no new wars.

The war is effectively won or nearly over

The war is very complete, pretty much.

A whole civilization will die tonight.

They want to make a deal

We are blasting Iran into oblivion.

Iran has agreed not to have a nuclear weapon.

The war is over.

The fake debt crisis of China

Much has been written about China’s supposedly dangerous debt/GDP ratio, which often is said to exceed 300% (or as “little” as 100%, depending on the source.)

The suggestion is that China is on the brink of bankruptcy, as if a Monetarily Sovereign nation were comparable to a family overwhelmed by credit card debt.

But that comparison is misleading. China’s “debt” consists of a mixture of central-government obligations, local-government financing, state-owned enterprises, banks, developers, and private borrowing.

More importantly, much of it is denominated in China’s own sovereign currency, the yuan. China cannot involuntarily run short of yuan any more than the United States can involuntarily run short of dollars.

The real concern isn’t debt in the usual sense. For a Monetarily Sovereign nation, debt is mostly just an accounting record of past spending compared to taxes collected. Big debt numbers by themselves don’t reveal much about the actual health of the economy.

In fact, debt is a measure of the growth yuan (and dollars) the central government is pumping into the economy. 

This contrasts with monetarily non-sovereign nations like France, Germany, Italy, Greece et al, which, like a family, can be overwhelmed by debt.

If China were to announce tomorrow that it planned to spend trillions of yuan repairing the Great Wall, building lunar bases, or developing massive new energy systems, the debt-to-GDP ratio could climb even higher. Still, those with economic insight would likely see these projects not as signs of crisis, but as affordable demonstrations of ambition and productive mobilization.

The real issue isn’t debt, but how spending is allocated. What counts is not the number of yuan China spends, but how it puts its labor, steel, concrete, energy, engineering skills, networks, and productive capacity to use. These resources are limited; the yuan isn’t.

If resources are directed toward useful infrastructure, advanced technology, transportation, energy production, education, or scientific development, the resulting spending can strengthen future productive capacity. But if resources are persistently directed toward projects that generate little long-term usefulness, the issue becomes one of misallocation rather than insolvency.

China’s famous “ghost cities” illustrate this distinction. Western commentary often portrays them as proof of a debt crisis. Yet many of those projects employed millions of workers, generated income, stimulated factories, and increased economic activity.

From a Monetary Sovereignty standpoint, idle labor is a waste, so putting people to work on less-than-perfect projects can still be better than leaving them unemployed. The real issue is whether those projects will add enough to future human well-being and productivity to justify spending limited resources.

If resources that could have built needed energy systems, transportation networks, or housing are instead diverted to speculative or low-value projects, then China may face a spending or allocation problem. The key phrase is “instead diverted.” 

But that still is not a debt crisis. It would be an asset-allocation problem.

In other words, debt does not consume resources. Spending consumes resources. A Treasury security or government bond sitting on a balance sheet does not eat food, burn fuel, or pour concrete. Real activity does.

The danger arises not because the accounting numbers become large, but because real resources may be directed inefficiently. Even then, the problem is not that China “runs out of money.” The problem would be that China may not be using its labor and productive capacity as effectively as possible.

Ultimately, the obsession with debt/GDP ratios often confuses financial abstractions with physical reality.

Economies are built not from accounting entries but from energy, food, transportation, factories, technology, labor, and organization.

China’s challenge, therefore, is not primarily financial solvency. It is whether its immense productive capacity is being directed toward projects that improve long-term human and economic development rather than merely inflating statistics or speculative construction.

That is a spending allocation problem, not a debt or even a Debt/GDP problem.

Rodger Malcolm Mitchell

Monetary Sovereignty

Twitter: @rodgermitchell

Search #monetarysovereignty

Facebook: Rodger Malcolm Mitchell;

MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell;

https://www.academia.edu/

……………………………………………………………………..

A Government’s Sole Purpose is to Improve and Protect The People’s Lives.

MONETARY SOVEREIGNTY

Science is held hostage by semantics

Economics

Scientists often misuse words with multiple meanings. For instance, economists use terms like “debt,” “deficit,” “borrow,” “trust fund,” “taxes,” and “insolvent.” These words each can mean very different things when applied to a Monetarily Sovereign government (the U.S., Canada, Australia, the UK, etc.) versus a monetarily non-sovereign entity (you, New York, Walmart, France) etc.)

In the case of the U.S. government:

  1. Federal “debt” represents savings and is not a burden on the government.
  2. Federal taxes do not fund federal spending; the government does not spend “taxpayers’ dollars.”
  3. Federal “deficits” are necessary for economic growth and also are not a burden; they add growth dollars to the economy.
  4. The federal government does not “borrow” dollars but has the unlimited ability to create them through legislation and simple computer entries.
  5. A federal “trust fund” is not like a private trust fund, but instead it’s just a line item on a balance sheet, entirely controlled by the federal government.
  6. Neither the federal government, nor its agencies can become “insolvent” with regard to dollars. For example, Medicare cannot run short of dollars unless the government wills it.

Economists often treat inflation as a “too much money” or an “excessive demand” problem, while ignoring the historical reality that shortages in energy, food, housing, and production capacity are the main culprits.

The Federal Reserve’s approach to tackling inflation—raising interest rates—aims to curb demand by making it harder for everyday people to spend. While higher rates can may cut borrowing, they slow economic growth, drive up costs, shift income toward the wealthy, and do nothing to address shortages in oil, food, housing, or infrastructure.

No major inflationary episodes, including the 1970s stagflation, Weimar Germany, Zimbabwe, and Venezuela, were caused by “money printing,” but rather by collapses in productive capacity, food production, energy supply, or other supply chains.

Yet popular wisdom holds that “too much money” is the cause of inflation, and the solution is to reduce the money supply. But because inflation is fundamentally about shortages, suppressing demand rather than expanding production amounts to applying leeches to cure anemia.

More specifically, inflation has been caused by shortages in foundational resources, especially energy. Oil prices and inflation move strikingly together because energy permeates transportation, agriculture, manufacturing, and nearly every economic activity.

Economics is a field in which failed predictions often survive because if a policy fails, economists claim it was not applied strongly enough or that outside variables interfered.

Example: to cure inflation, Ben Bernanke raised interest rates. When that worsened inflation, he raised them again. And again. And again. More leeches; worse anemia. Finally, inflation was cured when more oil began to flow.

Today, the Fed continues the same interest rate tradition.

Then consider tariffs. Under Donald Trump they are an example of policies that supporters defend regardless of contradictory outcomes. The deeper critique is that societies increasingly manipulate financial systems while neglecting real productive capacity.

Just as terms like “federal debt” and “trust fund” confuse, so do “dark energy,” “dark matter,” “wave-particle duality,” and “entanglement” mislead and conceal our ignorance. “Dark energy” is a phrase meaning, essentially, “the unknown thing causing cosmic acceleration.” 

Once science names something, people often assume it has been explained, when in fact the label may merely restate the mystery in an inappropriate way.

The most difficult question in cosmology is not “what?” or “how?” but “why?” Science leans at describing mechanisms and patterns, but every explanation eventually terminates in another “why?”

One thought: perhaps the universe exists the way it does because it could not exist any other way. Entanglement, quantum uncertainty, physical laws, and even infinity itself may not be arbitrary oddities but necessary conditions for a stable, persistent universe.

Reality itself might be a mechanism for exploring “possibility space,” with unstable configurations disappearing while stable patterns persist. Evolution would then not merely occur on Earth or within the universe but characterize the universe itself. Laws, structures, and even physical constants might emerge through a kind of cosmic selection process.

Success = failure × infinity + 1. Nature does not seek perfect solutions, only solutions that survive. Thus, perhaps the universe itself is a giant computational or exploratory process repeatedly asking, “What if?”

Life, intelligence, and consciousness can be seen as the universe’s way to look at itself. Humans ask “why?” because the universe developed beings capable asking that question. This “theo-cosmology,” imagines that if God exists, they didn’t create a finished universe but one that’s constantly searching. In this view, the universe isn’t a solved equation, but an ongoing Darwinian journey of exploration and possibility.

“What/how?” leads to “What if?” which leads to “Why?” which leads to “Then what?” which generates a new “What/how?” This endless cycle contrasts with oblivion, the only true stopping point where no questions, no history, and no persistence remain.

Existence therefore can be framed not as a static noun but as an ongoing process—a continual conversion of possibility into history.

We learn by analogy. metaphor and simile. (A is a B and like a C.”) In each case, a less familiar thing is compared to a more familiar thing to clarify the less familiar thing. The two things are not identical, just comparable. We cannot learn anything if there is nothing familiar to which it is compared.

Because we have no word for exactly what an electron is, we give it the word, “particle,” though current belief is that the electron is nothing at all like a tiny piece of matter.

An atom often is pictured as a miniature solar system, with electrons circling protons. It is not like that. “So,” you might ask, “what does an atom “look like?” That very question begs for an analogy.

So does the question, “What is magnetism made of?” 

We cannot understand how quantum entanglement works because it is not “like” anything we have experienced. And we describe the “wave-particle duality” as something that often “acts like” a wave acts and also “acts like” a particle acts. But “acts like” is not the same as “is.”

Consider pain, “Sharp” pain is not sharp in the way we understand something like a razor being sharp. In fact, being cut by a razor causes a pain that is different from a “sharp” pain. We don’t have a word for that pain.

In a similar vein, we are given the false analogy of “federal debt as being like personal debt,” though the two have virtually nothing in common. 

Just as good analogy supports learning, a false analogy supports ignorance. Believing that federal debt is similar to personal debt, and electrons are similar to particles– that is like choosing the wrong fork in a road. It not only will not take you to your goal, but actually diverts you, taking you farther from your destination.

If I say, “she is the apple of his eye,” I expect you to understand that the word “apple” has different meanings. But President Obama once said, “If a family must live within its means, the federal government should live within its means.” He wanted you to believe falsely, that “means” for the federal government has the same restraints as does “means” for a family.

When you hear worries about the size of the federal “debt,” it can distract you from the fact that a growing federal debt (which is net dollars created by the federal government) boosts the economy, while reducing federal debt leads to recessions and depressions.

History shows that almost every recession has followed the lack of federal deficit growth, and every depression has followed reductions in federal debt.

When faced with the analogy, “A is like B,” we must ask ourselves, “Does that analogy apply in this particular case?” Or is it just a polysemic similarity — one word with different meanings.

The phrase “I am my history” captures a powerful idea: identity is the sum of accumulated experiences. This notion applies not only to individuals but also to civilizations, species, and even the universe. The universe isn’t apart from its past—it is its past.

You are different from me. From our beginnings, we have different histories. You also are different from a tree, the ocean, the Earth, the Sun . . . All have different histories and are defined by those differences — and for many of our differences, we have no words, no analogies, nothing that tells us what a thought looks like or what love tastes like.

The innocent child, who repeatedly asks “why?” eventually destabilizes every explanatory system because every answer generates another deeper question. Science, philosophy, economics, and religion all eventually reach a point where they can only say, “That’s just the way things are.”

The refusal to stop questioning is the essence of intelligence itself. We each have scant control over our histories, along with scant control over the illusion of control.

Begin with understanding that federal debt is completely unlike personal debt. And those who tell you otherwise are simply wrong.

Don’t be held hostage by semantics.


Rodger Malcolm Mitchell

Monetary Sovereignty

Twitter: @rodgermitchell

Search #monetarysovereignty

Facebook: Rodger Malcolm Mitchell;

MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell;

https://www.academia.edu/

……………………………………………………………………..

A Government’s Sole Purpose is to Improve and Protect The People’s Lives.

MONETARY SOVEREIGNTY