–Ben Bernanke and the popular faith

An alternative to popular faith

According to the April 8, 2010 Wall Street Journal, “Federal Reserve Chairman Ben Bernanke said Wednesday that huge U.S. budget deficits threaten the nation’s long-term economic health and should be addressed soon.” That is the popular faith, with “faith” being defined as belief without scientific evidence.

By using the words “addressed” and “soon” Mr. Bernanke is relieved of the responsibility to provide a specific solution or a timetable.

The Journal said, “In remarks to the Dallas Chamber of Commerce, Mr. Bernanke agreed […] that the economy, while improving is still too weak to bear all the new taxes and spending cuts that would come with an aggressive deficit reduction campaign.” The Journal continued, “Cutting the deficit ultimately will mean choosing between cutting (Social Security and Medicare) entitlements, raising taxes or other spending cuts.”

This is exactly correct. Federal deficits never have been shown to cause inflation (See: item #8. )or to have any other negative effect on people or on the economy in general. In fact, substantial evidence indicates that reducing deficits has caused nearly every recession and depression in our history. (See: Click here, items #3 and #4. )

By contrast, increasing taxes or cutting Medicare and Social Security benefits or cutting other expenses (defense, infrastructure, health care, food stamps, education, research, etc.) absolutely will have a negative effect on people and on the economy in general.

So which does a sane person choose, something not proven to have a negative effect or something proven to have a huge negative effect?

Mr. Bernanke worries large deficits cause high interest rates. He subscribes to the popular faith that low rates stimulate the economy, despite there being no historical relationship between interest rates and economic growth (See Item #10 ), as he should have learned from his, and his predecessor’s twenty futile rate cuts leading into the recession.

Quoting the Journal, “[…] higher rates push up borrowing costs for many businesses and consumers,” ignoring the many businesses and consumers who are lenders, and who benefit from higher rates. For every borrower there is a lender. All of you who own savings accounts, NOW accounts, money market accounts, corporate bonds and T-securities profit when rates are higher. It may surprise you to learn higher rates have been economically stimulative, because they’ve forced the government to pay more interest into the economy. Finally, some economic hypotheses indicate low rates were partly at fault for the housing bubble.

In summary, Mr. Bernanke promotes a goal with no proven benefit, provides neither a plan nor a timetable for achieving his goal, admits it would require tax increases and spending cuts, both of which hurt people and the economy, and he discusses a possible problem (high interest rates) history shows is more a benefit than a problem.

At long last, will someone please stand up and say, “The popular faith doesn’t seem to work. May we try something new?”

Rodger Malcolm Mitchell
http://www.rodgermitchell.com

–Federal deficit spending doesn’t cause inflation; oil does

An alternative to popular faith

Ask a debt hawk why he hates federal deficits and he will give you four main reasons:

1. Federal debt must be paid back by taxpayers. (But, because the federal government has the unlimited power to create the money to pay its bills, taxpayers do not fund federal spending.)

2. Federal debt adds to the government’s interest-paying burden. (Again, interest is no burden to a entity having the unlimited ability to create money.)

3. Federal debt uses up lending funds that otherwise would go to private needs. (But, federal spending adds money to the economy, making more, not less, funds available for private lending.)

4. By increasing the money supply, federal deficits reduce the value of money, thereby causing inflation. Readers of this blog have seen the graph (below) which shows no relationship between federal deficits — even large federal deficits — and inflation.

Note how the peaks and valleys of deficit growth do not match the peaks and valleys of inflation growth:

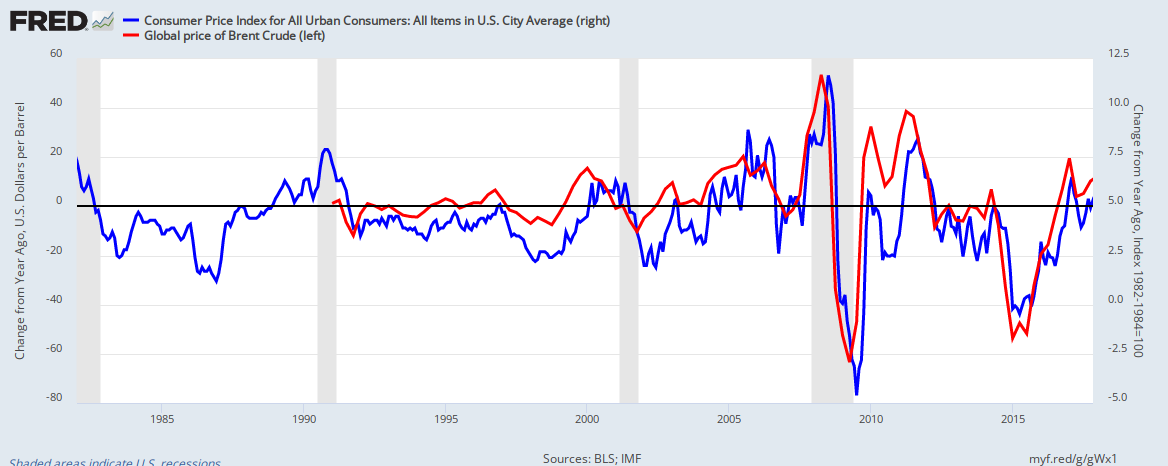
If deficits don’t cause inflation, what does? In a previous post “Is inflation too much money chasing too few goods”, we answered that question (“No.”), and we presented a graph indicating the real cause of inflation may be energy prices, more specifically, oil prices. See below:

The extreme movements of energy prices corresponding with the more modest movement of overall inflation, seem to indicate that energy costs “pull” inflation in either direction.

We can see this parallelism better by magnifing the CPI movement with a different vertical axis:

Monetary Sovereignty

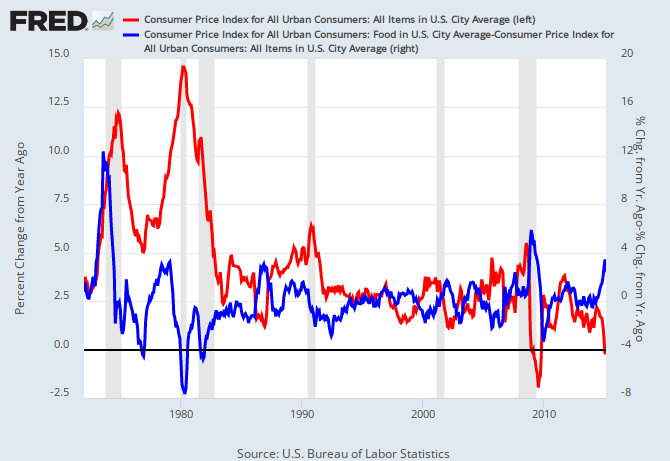
Now here is another graph that may substantiate the hypothesis that energy prices pull CPI:

monetary sovereignty

It compares inflation movements (red line) with the movement of energy prices less the movement of inflation (blue line). Notice how closely the two lines correspond.

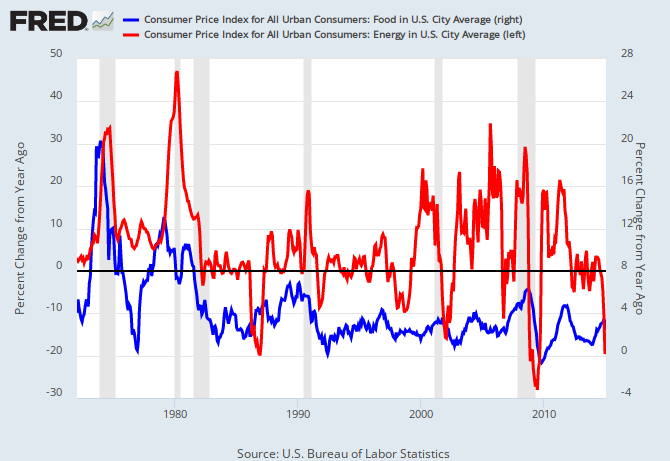
Compare that graph with the graph below. This graph is the same as the one above, except rather than comparing energy price changes with inflation, it compares food price changes. See how there is much less correlation.

monetary sovereignty

Food price changes do not seem to be the key inflation-causing factor. In fact, energy price changes seem to cause food price changes:

monetary sovereignty

Inflations are not caused by too much money. Inflations are caused by shortages.

Energy, and more specifically oil is, aside from food and water, the one universal need. It is the only commodity, the shortage of which, affects the prices of all other goods and services.

Rodger Malcolm Mitchell
http://www.rodgermitchell.com

No nation can tax itself into prosperity. Those who say the stimulus “didn’t work” remind me of the guy whose house is on fire. A neighbor runs with a garden hose and starts spraying, but the fire continues. The neighbor wants to call the fire department, which would bring the big hoses, but the guy says, “Don’t call. As you can see, water doesn’t put out fires.”

–Another attempt to explain the positive effect of deficits

An alternative to popular faith

I’m searching for a way to explain that contrary to intuition and to what the media and politicians say, large federal deficits are good, not bad. Please read this and tell me whether you believe its clear enough for non economists.

The federal government is unique, far different from you, me, businesses and local governments. Its finances, particularly its deficits may seem counter-intuitive. You may have three fundamental questions about federal deficits:

1. Are large deficits unsustainable? Is there a time when the government will not be able to service its debts?

2. Do large deficits have an adverse effect on the economy?

3. Are large deficits beneficial?

Unsustainable: Visualize a scenario where there are zero federal taxes. The federal government has no income, yet sends you, “Mr. Lucky,” a check for $10 trillion dollars. You will deposit the check in your bank.

Will the check bounce? No. Your bank will credit your account for $10 trillion, then send the check to the Treasury, which will credit your bank and debit its own balance sheets for $10 trillion. You now have $10 trillion in your account, allowing you to buy a few thousand Rolls Royces or the State of Montana, whichever you prefer.

The government can debit its balance sheet and credit your bank, endlessly. The balance sheet is just a score sheet with a number. Whether that number is $10 trillion or $100 trillion makes no difference to the score sheet. The only limit is the artificial “debt limit,” on which Congress votes periodically. There is no functional limit on what any balance sheet can read. The government can write a check of any size, despite zero taxes.

Taxes may be levied for several reasons, but supplying the government with spending money is not one of them. The government creates money by spending. It does not use tax money. Therefore, all federal debt is sustainable.

Adverse effect: One possible adverse effect often mentioned is taxes. (“My children and grandchildren will have to pay for today’s deficits.”) But, we just saw that taxes do not pay for deficit spending. We are the children and grandchildren of the Roosevelt and Reagan eras. We never have paid for those monster deficits. The mantra about children and grandchildren is a myth.

A second possible adverse effect is inflation. Contrary to popular faith, inflation is not “too much money chasing too few goods.” That is an obsolete slogan. Today, we live in a world economy. Given sufficient money, there never can be too few goods in the world to sell. Instead, inflation is loss of perceived money value compared to the perceived value of goods and services.

The phrase, “too much money chasing too few goods,” addresses only supply. Inflation however refers to supply and demand, for money and for goods and services. The demand for money can change without a change is supply, and is related to interest rates. The demand for goods and services can change similarly, but generally increases when money supply increases.

Since we went off the gold standard, in 1971, there has been no relationship between deficits and inflation. In fact, the largest deficits have corresponded with the lowest inflation. See the graph, below:

Instead, inflation has corresponded with oil prices. See how inflation and oil prices move in concert, but oil moves much more, indicating oil prices are “pulling” inflation. (See the chart, below) Oil is the one “good” that can be in short supply and affect the prices of all other goods and services.

Oil prices and inflation

Despite the fact that large deficits have not caused inflation, I suspect there may be a point at which truly gigantic money supply growth could lead to inflation. We’re just nowhere near that point, as witness the current deflationary concerns.

At any rate, if inflation ever did crop up, the government would increase interest rates to increase the demand for money.

Beneficial: New York, a large economy, needs more money than does Peoria, a smaller economy. In fact, by definition, large economies need more money than do smaller economies. So for an economy to go from smaller to larger, its money supply must grow.

If you feel economic growth is beneficial, you also must feel money growth is beneficial. Federal deficit spending is the way the government adds money to the economy to make it grow. Federal deficits are beneficial.

–//–

Does this seem like it would be clear to the average person? What are your suggestions?

Rodger Malcolm Mitchell
http://www.rodgermitchell.com

–Prof. Barro and the cost of federal spending

An alternative to popular faith

The 1/22/10 Wall Street Journal published an opinion piece by Professor Robert Barro (Harvard University), who believes, “Much more focus should be on incentives for people and businesses to invest, produce and work. On the tax side, we should avoid programs that throw money at people and emphasize instead reductions in marginal income-tax rates — especially where these rates are already high and fall on capital income. Eliminating the federal corporate income tax would be brilliant. On the spending side, the main point is that we should not be considering massive public-works programs that do not pass muster from the perspective of cost-benefit analysis. Just as in the 1980s, when extreme supply-side views on tax cuts were unjustified, it is wrong now to think that added government spending is free.”

Mostly, I agree — with one huge exception. That last phrase, ” . . . it is wrong now to think that added government spending is free” is itself, wrong.

If federal government spending is not free, it must have a cost. So what is the cost? Not higher taxes, which have no historical relationship to deficit spending. (See item #9 at https://rodgermmitchell.wordpress.com/2009/09/07/introduction/.)
Taxes generally have been based on political, not economic, considerations. From a financial standpoint, taxes no longer (after 1971, the end of the gold standard) affect the federal government’s ability to spend. In fact, all federal taxes could be eliminated tomorrow, and the federal government’s ability to spend would not be reduced by even one penny.

Is the cost of federal government spending increased inflation. No, not that either. There is no historical relationship between federal deficits and inflation. The highest inflation since WWII came with the modest Carter deficits, and was cured during the robust Reagan spending years. A graph of deficit growth vs. inflation shows a zero cause/effect relationship. (See item #8 in https://rodgermmitchell.wordpress.com/2009/09/07/introduction/ )

Well then, does deficit spending cause high interest rates? The graph at https://rodgermmitchell.wordpress.com/2009/11/15/deficits-and-interest-rates-another-myth/ indicates no relationship between high deficits and high interest rates.

Even if deficit spending did cause interest rates to rise, there is no historical relationship between low rates and high GDP growth. See item #10 at https://rodgermmitchell.wordpress.com/2009/09/07/introduction/

In summary, there is no post-1971 cost to federal deficit spending, a strong argument for tax cuts and increased spending and a strong argument against deficit concerns.

Rodger Malcolm Mitchell
http://www.rodgermitchell.com