Monetary Sovereignty and Gap Psychology: Why the Rich Need The Poor
- Why does the richest nation in history repeatedly claim it cannot afford to provide adequate healthcare, retirement income, education, housing, and food for its people?
- Why do politicians warn that Social Security and Medicare are running out of money while the federal government continues to create trillions of dollars for other purposes?
- Why are Americans told that helping the poor requires painful sacrifices, higher taxes, and reductions in other benefits?
- And why do these supposed financial limitations so often fall most heavily on those who have the least?
To answer those questions, we need to understand two fundamental economic concepts: Monetary Sovereignty and Gap Psychology, two pillars of economics.
Monetary Sovereignty explains the federal government’s relationship with money. Gap Psychology explains an important part of humanity’s relationship with power. One concerns what the government can do. The other helps explain why it doesn’t. Together, they explain some of the most persistent contradictions in American economic policy.
The Gap: Why Being Rich Requires Someone Else to be Poorer
Imagine that you have $1 million. Are you rich? That depends.
If everyone else has $100, you are extraordinarily rich. If everyone else has $1 million, you are average. If everyone else has $100 million, you are poor. Your $1 million has not changed. What changed was your position relative to everyone else.
Thus, rich and poor are comparative terms. They describe relationships, not merely quantities. I call that relationship the Gap. It separates people according to income, wealth, power, status, and other measures of superiority.
And Gap Psychology describes the common human desire to widen the Gap below oneself and narrow the Gap above.
Consider a man who can perform only two chin-ups. He wants to be considered strong. He could exercise until he can perform twenty chin-ups, or he could hang a 300-pound weight from everyone else’s ankles. Suddenly, his two chin-ups might make him the strongest man in the room.
He hasn’t improved himself. He has made everyone else comparatively weaker. That is Gap Psychology. You can increase your relative superiority either by raising yourself or by lowering others. And lowering others sometimes is easier.
This principle extends far beyond money.
The Gap is Everywhere
Gap Psychology operates in two directions. We look up at people with more income, wealth, status, or power than we do, and we want to narrow that Gap. But we also look down at those with less, and we resist their narrowing the Gap with us. These two impulses aren’t necessarily equal. We may enjoy gaining on the people above us, but we can feel something more visceral when the people below us gain on us.
Consider a simple inheritance. A parent leaves one child $2 million. She is delighted—until she learns that her sibling received $2,000,010. She hasn’t lost a penny. She still has the same $2 million that delighted her moments earlier. What she has lost is relative position. Ten dollars changed happiness into resentment, not because of its purchasing power but because of its effect on the Gap.
This may connect Gap Psychology to the well-established psychological phenomenon of loss aversion: losses generally affect us more strongly than equivalent gains. A raise is welcome. Try cutting someone’s salary by the same amount and observe the difference.
But Gap Psychology adds another dimension: We can experience a loss without losing anything at all. If someone below us rises toward us, our income and wealth may remain unchanged while our relative position declines.
Suppose Fred earns $60,000 and Sam earns $40,000. Fred has a $20,000 income Gap below him. Now suppose a government program improves Sam’s economic position by $20,000 while costing Fred nothing. Fred still earns $60,000. In absolute terms, he has lost nothing. But his $20,000 Gap has shrunk to $0. If relative position matters to Fred, he has experienced something that feels like a loss.
This helps explain why Gap Psychology is not merely a theory about the rich. Middle-class people, and even those with relatively low incomes, often oppose programs that benefit people poorer than themselves. Their opposition may seem irrational if we assume that everyone seeks only to maximize their own absolute financial well-being. But it becomes more understandable if relative position also has value. A benefit received by someone below me can narrow my Gap even when it costs me nothing.
Thus, the desire to preserve hierarchy can extend throughout the hierarchy. The billionaire wants distance from the millionaire. The millionaire wants distance from the upper-middle class. The upper-middle class wants distance from the middle class. The middle class wants distance from the poor. Even someone near the bottom may place considerable psychological value on knowing that someone else remains below him.
This helps explain the remarkable durability of caste and class systems. A hierarchy need not provide substantial material benefits to everyone who defends it. Each level except the bottom can receive at least one benefit from the arrangement: the status of not being at the bottom. The system can therefore recruit some of its own victims to help preserve it.
And this may explain something particularly important about political efforts to protect the income/wealth/power Gap. The rich need not persuade middle-income people that making billionaires richer will improve their lives. That can be a difficult sale. It may be far easier to persuade them that improving the lives of people below them will diminish what they have earned, reward people who do not deserve it, or unfairly elevate others to their level.
In that sense, Gap Psychology can turn the hierarchy into a self-protecting system. Those at the top have the greatest economic incentive to preserve it, but people throughout the hierarchy can also gain a psychological incentive to protect or even widen the Gap immediately below them.
We aspire to narrow the Gap above us, but we may fight even harder to prevent others from narrowing the Gap below us. And that may be one reason economic hierarchies survive even when most of the people defending them are nowhere near the top.
Consider intelligence. A child who learns to read at age four may be considered exceptionally intelligent. But if every other child learns to read at age three, that same child may be considered slow.
Consider physical ability. A man who runs 100 meters in twelve seconds is fast compared with most people, but slow compared with an Olympic sprinter.
Consider social status. A person may feel important because of a prestigious job, an exclusive club, an expensive automobile, a distinguished family, or membership in a particular organization. Satisfaction often comes not merely from possessing something desirable, but from possessing something others lack.
Exclusivity itself becomes valuable. An exclusive club loses some of its appeal when everyone can join. A luxury brand loses some of its status when everyone can afford it. A title loses some of its distinction when everyone possesses it. The Gap gives these things their comparative value.
People can also gain a sense of superiority through the groups they belong to. Sports provide an example. When the Chicago Bears won the Super Bowl following the 1985 season, their fans celebrated as though they personally had accomplished something extraordinary. I was one of them. I hadn’t blocked a defensive lineman, thrown a pass, or scored a touchdown. Nevertheless, I felt victorious.
Why? Because I identified with the winning group. Their superiority became my superiority. The same psychological mechanism can operate through nationalities, religions, political movements, professions, social classes, and other affiliations.
People seek superiority not only as individuals but also as members of groups. When their group rises, they feel elevated. When a competing group falls, they may experience a similar satisfaction. Gap Psychology helps explain why people sometimes celebrate another group’s misfortune even when that misfortune provides no material benefit to themselves.
From Gap Psychology to Caste and Class
Throughout history, societies have established systems that rank human beings according to ancestry, religion, occupation, race, wealth, and social position.
Caste systems are particularly revealing. Their purpose is not merely to recognize differences among people. They establish differences in status, rights, opportunities, and power. They preserve those differences across generations.
A person born into a dominant caste may possess privileges unavailable to someone born into a subordinate caste, regardless of individual ability. The superiority Gap is inherited.
Religion and group identity also can become vehicles for asserting superiority. Some groups claim special virtue, divine favor, purity, or exclusive access to truth. Such claims can justify treating outsiders as inferior.
Not every religion, club, or social organization behaves this way. But the mechanism recurs: membership in a supposedly superior group provides status, while exclusion helps preserve it.
In her book “Caste: The Origins of Our Discontents”, Isabel Wilkerson examines how hierarchical social systems preserve privilege through inherited status, exclusion, stigma, and institutional power. Gap Psychology provides one possible explanation for the human attraction to such hierarchies.
If my superiority depends on your inferiority, your improvement can feel like my loss. That is the essential psychological problem. And it becomes particularly consequential when applied to economics.
Why the Rich Want to Widen the Gap
The rich possess more than money. They possess economic power. Money can buy goods and services, but wealth also can purchase ownership, influence, access, security, and control over resources.
A wealthy employer may determine whether hundreds or thousands of people have jobs. A wealthy landlord may determine the conditions under which families obtain housing. A wealthy investor may influence which businesses expand and which disappear. A wealthy donor may obtain political access unavailable to ordinary voters.
These forms of power do not depend solely on how many dollars the wealthy possess. They also depend on how economically independent everyone else is.
Imagine two societies. In the first, workers have government-guaranteed healthcare, retirement income, affordable education, and a dependable minimum income.
In the second, workers risk losing healthcare when they lose their jobs. Retirement is uncertain. Education creates debt. Unemployment threatens financial catastrophe.
In which society does an employer possess greater leverage over employees? Clearly, the second. Workers who fear losing essential benefits have fewer practical choices. They may accept lower wages, undesirable working conditions, or mistreatment because leaving their jobs carries unacceptable risks. The employer’s power grows as the worker’s alternatives diminish.
That is the connection between wealth and dependence. The Gap is not merely a difference in dollars. It is a difference in freedom. A wealthy person need not consciously think, “I want workers to remain dependent on me.” But economic incentives can operate without such explicit thoughts.
The result remains. Systems that preserve economic insecurity can preserve the advantages associated with concentrated wealth. And Gap Psychology suggests that preserving relative superiority may itself become a powerful motivation.
Monetary Sovereignty: The other pillar
Now consider an entirely different question. Where does the federal government obtain dollars?
Most Americans have been taught to think of federal finances as though the United States were an enormous household. The federal government collects taxes. It spends the money. If it spends more than it collects, it must borrow the difference. We are told that eventually, the debt grows so large that the government no longer can afford to pay its bills.
This familiar explanation overlooks a fundamental distinction. A household, business, city or state government uses dollars. The United States federal government operates the monetary system that issues dollars. It is Monetarily Sovereign.
The federal government cannot create unlimited doctors, nurses, houses, oil, food, steel, or electricity merely by issuing dollars. Those are real resources. But the monetary system can create the dollars to buy these assets without first obtaining them from taxpayers.
The U.S. Treasury does not have the same financial limitations as a household. Though the federal government can face a shortage of real resources. It never faces an inherent shortage of its own currency. That means federal programs should be evaluated primarily according to their real economic consequences, not on cost.
- Will they require resources that are unavailable at any price?
- Will they increase productive capacity?Will they improve people’s lives?
- Will they cause or relieve inflationary shortages?
Those questions are more meaningful than asking whether the federal government can somehow find enough dollars.
Where the Two Pillars Meet
Now combine Monetary Sovereignty with Gap Psychology. Suppose the federal government possessed the monetary capacity to provide substantially greater economic security to ordinary Americans.
And, suppose those benefits would reduce poverty, improve health, increase educational opportunities, and make workers less dependent on wealthy employers and asset owners. Such policies could narrow the income/wealth/power Gap. That would benefit millions of Americans. But it also could reduce the relative advantages of people whose power depends partly on the economic insecurity of others.
Gap Psychology supplies a possible motive for resisting those policies. Monetary Sovereignty exposes a weakness in the argument that the government simply cannot afford them. Together, the concepts raise an uncomfortable question:
Are Americans being denied benefits because the federal government lacks the monetary capacity to provide them, or because providing them would alter existing relationships of wealth and power?
The answer may differ among particular policies and political actors. But the question deserves far more attention than it receives.
The Remarkable History of FICA
Social Security provides a revealing example. When President Franklin Roosevelt established Social Security, he insisted that the program include payroll contributions. Why?
Was it because the federal government otherwise would lack the dollars needed to pay retirement benefits? No. Roosevelt’s own explanation suggests something quite different.
In a 1941 conversation recorded by Luther Gulick, Roosevelt explained that payroll contributions were intended to give workers a legal, moral, and political claim to their benefits. He described the taxes as intended to protect Social Security against future attempts to abolish it.
Roosevelt understood something important about human psychology. People are more likely to defend benefits they believe they have earned than benefits portrayed as government charity. Payroll contributions helped transform Social Security from a welfare program into a perceived earned right.
And Roosevelt expected that perception to make the program politically secure. He did not present the payroll tax as a necessary source of dollars that the federal government otherwise lacked.
The irony is extraordinary. A tax intended to protect Social Security politically became part of the argument for limiting Social Security financially. Today, Americans repeatedly hear that Social Security benefits cannot be expanded because payroll taxes and trust-fund balances are insufficient.
The program is described as though it were a private pension fund that must accumulate dollars before distributing them. But that is a statutory financing arrangement, not a fundamental limitation on federal monetary capacity.
Congress could authorize benefits through a different financing system. The federal government would not gain any new power to create dollars. It would exercise an existing monetary capacity under different laws.
Roosevelt intended payroll contributions to protect Social Security from political destruction. He apparently did not anticipate how effectively the resulting financing structure could be used to argue against expanding benefits.
The Trust-fund Illusion
The Social Security and Medicare trust funds reinforce the same misunderstanding. The phrase trust fund suggests a protected pool of money, invested independently and held exclusively for future recipients. Private trust funds operate that way.
Federal trust funds are different. They are legal and accounting arrangements through which the government records designated receipts, expenditures, and obligations. Social Security trust funds hold special Treasury securities. Those securities are assets of the trust funds and liabilities of the Treasury. One part of the federal government holds obligations issued by another part.
The arrangements are legally real. Their balances matter under existing statutes, but they do not represent an independent source of monetary power.
When the federal government redeems a trust fund’s Treasury securities, it makes dollar payments through the same monetary system that makes all other federal dollar payments possible. Congress can change the laws governing trust-fund financing. But it cannot change the fact that the federal government issues the currency in which benefits are paid.
Yet the public repeatedly and falsely is told that trust-fund depletion means Social Security is running out of money. The statement confuses two different propositions. The trust fund may exhaust its authority to support scheduled benefits under existing law. But the federal government always can create new dollars.
The distinction matters because the proposed responses often involve benefit reductions, higher payroll taxes, later retirement ages, or combinations of those measures. Those policies have serious consequences.
Reducing benefits increases recipients’ financial insecurity. Increasing payroll taxes reduces workers’ take-home pay. Raising retirement ages can impose particular burdens on people whose health or occupations make continued employment difficult. And because businesses pay 50% of FICA, this not only reduces economic profits but discourages hiring.
Each policy deserves examination according to its actual effects. But no one should justify these policies by pretending the federal government is financially equivalent to a private pension fund.
Healthcare and the Power of Dependence
Consider employer-sponsored healthcare insurance. Millions of Americans receive health coverage through their employers. That arrangement has advantages, including access to group insurance and employer contributions toward premiums. But it also creates dependence.
An employee contemplating a job change must consider not merely salary and working conditions but also the availability, cost, and quality of health coverage. Economists call this phenomenon “job lock.”
Research has found that employer-linked health insurance can discourage workers from changing jobs or asking for higher wages or improved working conditions.
The Affordable Care Act reduced key problems involving preexisting conditions, but concerns remain about provider networks, coverage differences, premiums, and family benefits. The economic implications extend beyond healthcare.
A worker who can leave an employer without risking medical coverage possesses greater bargaining freedom. A worker whose family depends on the employer’s insurance may feel compelled to remain.
Now imagine Medicare For All.
Healthcare coverage would no longer depend on employment. Workers could change jobs, start businesses, retire, or negotiate without the same fear of losing insurance. The federal government could pay for the program in dollars.
Of course, paying medical bills is not the same as producing medical care. A successful expansion would require adequate doctors, nurses, hospitals, clinics, equipment, medications, and other real resources.
Federal spending to expand those resources would be essential. But the monetary question and the production question are separate. The federal government need not run short of dollars. The healthcare system can run short of healthcare.
That is a real problem requiring a real solution. Declaring Medicare for All unaffordable because the government lacks dollars does not solve it. And the dependence created by employer-sponsored insurance has consequences for the Gap.
Universal Medicare coverage could reduce one important source of employer leverage over workers. That makes healthcare policy a question of economic power as well as medical care.
Social Security For All, Education, and Poverty
The same reasoning extends to other public benefits.
Consider Social Security for All: a federal income floor sufficient to prevent destitution. Such a program would not make everyone wealthy, but it could reduce the desperation that forces people to accept almost any available wage or working condition.
Consider free public college and vocational education, which could provide skills, knowledge, and opportunities. When access depends heavily on family wealth or the willingness to take on debt, existing economic advantages can reproduce across generations. A student from a wealthy family may start adulthood with an education and no debt. A student from a poorer family may have similar abilities but face substantial financial obligations.
The Gap can widen before either student earns a paycheck.
Consider food assistance. A person who lacks adequate food has less freedom to make long-term decisions about education, employment, health, and family life. Reducing hunger can improve both individual well-being and productive capacity.
These programs have different costs, resource requirements, and economic effects. They should not be treated as interchangeable, but they share an important characteristic. They can reduce the degree to which survival and opportunity depend on private wealth. That is why Gap Psychology is so important.
The Tax Code: Another Window Into the Gap
The federal tax code further illustrates how financial policies maintain these hierarchies. While labor income is typically taxed at the highest marginal rates as it is earned, capital gains often enjoy preferential tax treatment and the ability to defer taxation indefinitely. Through deductions, exclusions, and loopholes, the tax system often consolidates wealth at the top, reinforcing the economic divide that Gap Psychology seeks to preserve.
These rules are not distributed equally across economic circumstances. People whose income comes primarily from wages face a different tax environment from people whose wealth comes largely from appreciating assets.
Raising the top ordinary income-tax rate therefore does not necessarily reach all the mechanisms through which enormous fortunes accumulate, nor does it automatically eliminate the political and economic advantages associated with concentrated ownership.
In short, the tax code does more than collect revenue. It influences who accumulates wealth, who retains it, and widens the income/wealth/power Gap. Further, people with substantial wealth have more resources to influence the laws that govern it.
That creates a reinforcing cycle. Wealth provides influence, which helps preserve favorable economic arrangements. Those arrangements preserve or increase wealth, which provides still more influence.
The Question of Motive.
If the federal government possesses the monetary capacity to provide greater benefits, why does the claim that it cannot afford them remain so influential? There are several possible explanations. Some people sincerely misunderstand how the federal government manages money. They apply household financial rules to the federal government because those rules are familiar.
Others understand that federal finance differs from household finance but believe that taxes, borrowing restrictions, and spending limits provide useful safeguards against inflation or excessive political spending.
Still others may find that claims of financial scarcity support policies favorable to their economic interests.
These explanations can coexist. But Gap Psychology preserves relative superiority. People may not acknowledge that motivation, even to themselves. They may describe their preferences in terms of fiscal responsibility, self-reliance, efficiency, fairness, or opposition to government dependency.
Some of those concerns may be sincere; some may be rationalizations, and some may conceal deliberate efforts to preserve economic advantages. But the distributional consequences of policies can be examined by:
-
- Who gains or loses?
- Whose economic independence increases or decreases?
- Whose relative power grows or shrinks?
Those questions reveal dimensions of economic policy that conventional discussions of deficits and debt often overlook the difference between wanting more and wanting relatively more. Conventional economics often assumes people seek to increase their material well-being, but Gap Psychology adds another consideration. People also seek to improve their position relative to others.
Imagine a wealthy person choosing between two outcomes. Under the first, his wealth increases by 20%, while everyone else’s wealth increases by 40%. Under the second, his wealth increases by 10%, while everyone else’s wealth stays the same.
The first outcome makes him absolutely richer. The second may make him relatively richer. If he values absolute wealth most, he may prefer the first, but if he values relative superiority most, he may prefer the second. That distinction matters enormously.
It suggests that opposition to broadly beneficial policies often stems not from fear that the wealthy will become poorer, but from the realization that such policies would accelerate everyone else’s advancement. Consequently, a policy can increase national prosperity while simultaneously narrowing the social and economic gap—an outcome many find unacceptable because it diminishes their relative standing.
For people who value relative superiority, that narrowing itself may feel threatening. The desire to widen the Gap therefore can conflict with the desire to maximize total prosperity. When those who benefit from a wide Gap have disproportionate political influence, that conflict can prevent affordable programs that benefit the poor.
What About Inflation?
Inflation is the widespread increase in prices. If there is a shortage of bananas, the cost of bananas will rise, but that is not inflation. If food is scarce, the cost of food will rise, and that could be inflation. If there is a shortage of food and oil, the cost of everything will rise, and that absolutely is inflation.
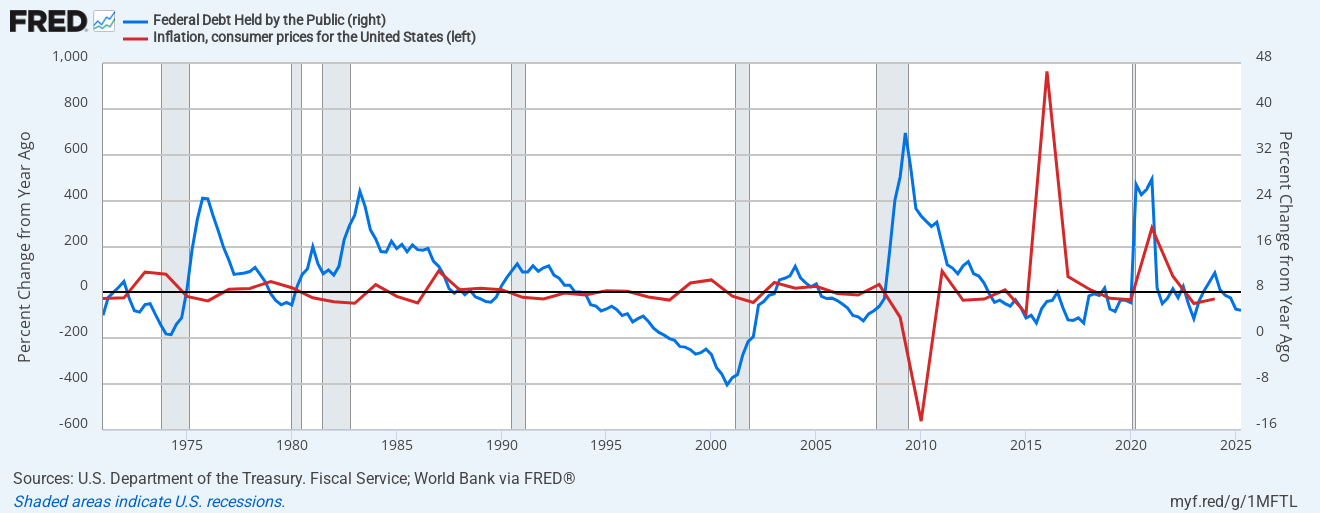
Many people believe, and many economics texts teach, that federal spending increases demand, and that increase causes inflation. The evidence does not support this. See: The inflation myths debunked. It’s never “money-printing.” It’s always shortages.
The article lists historical inflations and their causes. It shows that no major historical inflations have been caused primarily by a government spending “too much.” Further, the article shows that recessions are caused by a government spending too little.
To prevent and cure inflations, it is not necessary to instigate recessions. Instead, the government should prevent and cure shortages of critical goods and services, most often oil, food and labor. Rather than trying to prevent inflation via a blanket restriction of federal deficit spending, a Monetarily Sovereign government should:
-
- Identify the shortages
- Increase the supply of scarce goods and services.
- Invest in productive capacity.
- Remove unnecessary barriers to production.Train additional workers.
- Develop technology.
- Expand infrastructure.
The conventional response to inflation often emphasizes reducing demand by raising interest rates, increasing taxes, or cutting spending. Those policies can reduce inflationary pressure by making purchases more expensive (ironically) and reducing people’s ability to buy. They do not eliminate the underlying shortages.
The current “plan” (if one can call it a plan) is to reduce demand for scarce medical care rather than to produce more medical care. Forcing the sick to go untreated is not a viable anti-inflation program.
There is a difference between making housing unaffordable and building more housing. Making energy unaffordable for some is different from increasing the amount of energy available.
If the problem is a shortage, the lasting solution is to relieve the shortage. Federal spending can reduce inflationary pressure by increasing the supply of what is scarce.
Therefore, the question should not be merely how much the government spends. It should be what the spending accomplishes.
The Purpose of Government
The purpose of government is to protect and improve the lives of the governed.
We do not suggest punishing wealthy people for being wealthy, nor must everyone have the same income, property, or status. People differ in ability, ambition, preferences, circumstances, and accomplishments. Differences in income and wealth will exist.
The question is whether those differences should determine access to the necessities of life and the degree of freedom people possess. Should a person be forced to remain in an undesirable job because leaving would endanger the family’s healthcare? Should an elderly person face poverty because a federal accounting arrangement has reached a statutory limit? Should a capable student be denied education because the family lacks money? Should children go hungry in a nation with the productive capacity to feed them?
Monetary Sovereignty tells us that the availability of federal dollars should not be an obstacle. Gap Psychology suggests why reducing those hardships may encounter resistance from people and institutions whose relative advantages depend partly on their continuation.
The two theories therefore illuminate different sides of the same problem. One explains the monetary possibilities. The other examines the human incentives that can prevent those possibilities from being realized.
The Ultimate Gap
The most important Gap is not the difference between two bank accounts. It is the difference between two people’s freedom. One person can leave an unpleasant job without worrying about food, housing, or medical care. Another cannot.
One can pursue education without incurring unaffordable debt. Another cannot. One can survive a financial emergency without losing a home. Another cannot. One can influence public policy through wealth and connections. Another struggles merely to be heard.
These differences are economic, but they also are differences in power. And power can perpetuate itself. People with power can influence the rules under which others acquire power. People without power may lack the resources to change those rules. The Gap therefore can become self-reinforcing.
That is why reducing poverty is not enough. A society can become wealthier while its economic hierarchy becomes more extreme. The poor can gain dollars while losing relative influence. The middle class can earn higher salaries while becoming more dependent on employers, lenders, insurers, and asset owners.
Prosperity and Economic Independence are Not Identical.
A society should be judged not merely by how much wealth it produces but also by how that wealth affects people’s lives and freedoms. Monetary Sovereignty and Gap Psychology approach economics from opposite directions. Monetary Sovereignty begins with the nature of money. Gap Psychology begins with the nature of human comparisons.
Monetary Sovereignty asks what a currency-issuing government can accomplish. Gap Psychology asks how the desire for relative superiority influences people’s decisions.
Together, they help explain why policies that could improve millions of lives may face determined resistance. The familiar claim is that America cannot afford to provide greater economic security to its people. But the more revealing question may be, Who benefits when:
- Americans believe that claim?
- retirement remains uncertain?
- healthcare depends on employment?
- education requires debt?
- workers fear unemployment more than employers fear losing workers?
- people accept economic insecurity as unavoidable?
And who loses power when those insecurities disappear?
These questions don’t require us to assume every wealthy person is selfish, every politician dishonest, or every economist ignorant. They require us to recognize that economic policies influence relative power—and that relative power can influence economic policies.
For too long, Americans have been trapped in a manufactured debate over whether the federal government can “afford” to improve their lives. This framing ignores the reality of our Monetary Sovereignty and obscures the incentives driven by Gap Psychology.
The federal government possesses extraordinary monetary capacity, and our nation holds vast productive potential. Neither guarantees perfect policy, but together they make it essential to ask why so many Americans remain economically insecure.
The answer is not found in national affordability, but in the incentives of powerful interests to maintain the status quo. Monetary Sovereignty shows that federal financial scarcity is a choice, not a constraint; Gap Psychology explains why prosperity’s benefits are intentionally kept unequally distributed.
Together, these concepts lead us to a fundamental question: If our government has the inherent capacity to free its citizens from economic dependence, why do we continue to accept false narratives of financial limitation as a justification for preserving that very dependence?
The greatest obstacle to narrowing the Gap is not a shortage of dollars, but rather the value some people place on keeping the Gap wide.
Rodger Malcolm Mitchell