Fed Chair Jerome Powell, maybe pigs will fly

Federal Reserve chair vows to curb inflation with hikes that risk economic pain | The Japan Times Powell: I know that inflation hurts, but I’m going to try to reduce inflation without causing a recession. Sad family - Frog Financial Management Alice: Our landlord said he has to raise our rent because his costs have increased. I can’t afford that. What can you do about it? P: I’m going to raise interest rates. Alice: But that will increase my landlord’s costs. Won’t that make the situation worse? P: Raising interest rates is what I always do to fight inflation. It may not really work, but the politicians think it does, so it’s what I do A: There’s a food shortage, so our food costs have gone up. I can’t afford to feed my children. What can you do about that? P: I’m going to raise interest rates. A: But that won’t help the food shortage. It only will make it harder for farmers to borrow., which will increase farmers’ costs? How will that lower food prices? P: It won’t, but I also plan to sell off my T-bonds. A: I don’t know much about T-bonds, but won’t that take money out of the economy? How does taking money out of the economy help the food shortage? P: Beats me. A. And the price of gas has gone up due to a shortage of oil. What are you doing about that? P: I’m going to raise interest rates and sell off my T-bonds. A: How does raising interest rates and selling off bonds increase gas supply? P: It doesn’t, but it’s what I do. I think it’s supposed to cool the economy, which by definition, is a recession. A: You want to cause a recession — a reduction in trade and industrial activity? Federal Reserve chair vows to curb inflation with hikes that risk economic pain | The Japan Times P: Yes, but please don’t call it a recession. Let’s call it “a cooling process.” A: I’m unemployed. I easily could get a job, but when I pay FICA taxes and income taxes, and my employer pays his share of FICA and our healthcare insurance policy, my net take-home pay won’t cover inflation. What are you doing about that? P: I’m going to raise interest rates and sell off my T-bonds. Sad family - Frog Financial Management A: Will that increase my net take-home pay? P: Of course not. I can’t eliminate FICA, provide Medicare for All, or increase the Standard Deduction, all of which would increase your net pay. I also can’t stop taxing Social Security benefits and IRA distributions to provide you with more long term net pay. But, raising interest rates and selling off my bonds is what I do. It doesn’t work, but it makes me look prudent. A: I understand there’s a shortage of computer chips, which causes a shortage of everything that uses computer chips, and those shortages cause the prices of almost everything electric to increase. What can you do about that? P: The usual. I’m going to raise interest rates and sell off my T-bonds. A: Again, how will that cure the shortage of computer chips? P: It won’t. It only will make borrowing more expensive, and there’ll be less money in the economy, so people like you will have less money to spend. Fundamentally, I’m going to impoverish you to fight the shortage of goods and services that is causing inflation. A. That’s crazy. Why make borrowing more expensive, which is recessive, and take money out of the economy, which also is recessive? Recession isn’t the opposite of inflation. Deflation is the opposite of inflation. Your policies could cause stagflation, which is even worse. The only way to reduce prices without a recession is to cure the causes of inflation: Shortages of key goods and services. P: Sure, you know that, but the public doesn’t. They think I know what I’m doing. A: While we’re talking about inflation, and everything being more expensive, the cost of medical insurance has gone up. There’s a shortage of doctors, nurses, and hospital beds, along with a shortage of medical equipment. What can you do about all those shortages that are causing medical inflation? P:  Don’t you get it? I can’t cure shortages of anything — not shortages of food, nor oil, nor houses, nor computer chips, nor shipping, nor doctors, nor nurses, nor hospital beds — nothing. I have no control over the shortages that are causing inflation. All I can do is cause a shortage of money, and that, together with all those other shortages will cause the economy to cool, in other words, a . . . . A: Recession. P: Or maybe, that stagflation thing. In short, I actually will cause a recession to cure inflation, but I won’t call it a recession. Let’s call it “prudent management.” A: So if you can’t cure the inflation without causing a recession or, God forbid, a depression, who can? Federal Reserve chair vows to curb inflation with hikes that risk economic pain | The Japan Times P: Congress and the President have the power to cure the shortages that cause inflation, and not cause a recession or depression. To cure the shortages of food, Congress can pay farmers to grow. Previously we’ve paid them not to grow, so prices would be higher. Now we can reverse that. A: And oil shortages, computer chip shortages, shipping shortages, and labor shortages? P: Yes, I’ll let you in on a little secret. Congress and the President could pay to solve all those shortages, which would bring down prices. They have the power. All I can do is fiddle with interest rates. Sad family - Frog Financial Management A: So why . . . ? P: Today’s Congress is hopeless. The Republicans don’t care about the economy. All they want to do is win elections. So they act outraged about everything, but they don’t have actual plans to do anything about the economy. Let’s face it, white supremacists, bigots, anti-vaxers, anti-gay, anti-immigrant, anti-Mulsim, and anti-black dummies storming Congress are not the kind of people likely to have created coherent plans to improve the economy. The Dems want to grow the economy, but they think federal spending to cure shortages would cause, not cure, inflation. Frankly, I don’t understand how curing the shortages of food, oil, computer chips, labor, etc., etc., etc,. could cause inflation, but the Dems are terrorized by the word “debt.” A: But isn’t debt bad? P: Nah, debt is bad only if you can’t afford to pay for it. But the federal government never can run short of its own sovereign currency, the U.S. dollar. It can pay off any size of debt instantly, without levying a penny in taxes. A: So why don’t you just tell the American people all this? Why do you pretend you can cure inflation without causing a recession or depression when you know you can’t. P: There’s an old story that comes to mind:

The King sentenced a man to death. The man pleaded, “If you spare me, I promise that in one year, I will teach this pig to fly.”

The King laughed and said, “I will give you one year. If the pig doesn’t fly, I will kill you myself.”

When the man’s friends asked him how he could make such a ridiculous promise, the man replied, “Much can happen in a year. The pig might die; the King might die, or I might die.

“Or who knows, I might teach the pig to fly.”

So much could happen in a year. We could go to war with Russia or China, and everyone would forget about inflation. A meteor could fall on Washington. COVID could act up again. The Supreme Court could outlaw gays. Many things could divert our concerns from inflation. And maybe pigs will fly. In any event, Powell’s claims have bought him some lucrative time as Chair of the Fed (over $200K per year, plus many great benefits), and who knows, inflation might just go away, and he’d get accolades, whether or not we had a recession. It worked for Paul Volcker. Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:
  1. Monetary Sovereignty describes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”
Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps: Ten Steps To Prosperity:
  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 
The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY

A quick quiz to see whether you are smarter than Fed Chairman Jerome Powell

Here is a quick quiz. Learn whether you are smarter than Federal Reserve Chairman Jerome Powell. BACKGROUND: We currently suffer from inflation, “a general increase in prices.”  The Fed’s task is to bring inflation down while not causing a recession, i.e. “an economic decline during which trade and industrial activity are reduced.” Prices have increased for food, oil, cars and motorcycles, shipping,  labor, and household goods that use paper or cotton, such as diapers, incontinence supplies, sanitary napkins and tampons, and toilet paper, and labor. THE QUIZ: A. There is a shortage of food. The price of food has gone up. The solution should be either to:
  1. Force people to eat less, or to
  2. Help farmers grow more.
B. There is a shortage of oil. The price of oil has gone up. The solution should be either to:
  1. Force people to drive less and to heat their homes less, or to
  2. Help refineries produce more oil and help increase the availability of renewable energy.
C. There is a shortage of cars and motorcycles. The price of cars and motorcycles has gone up. The solution should be to:
  1. Force people to buy fewer cars and motorcycles, or to
  2. Help car manufacturers produce more cars and motorcycles.
D. There is a shortage of shipping ability (the “supply chain”). The price of shipping has gone up. The solution should be to:
  1. Force manufacturers and sellers to ship less, or to
  2. Help manufacturers and sellers to ship more.
E. There is a shortage of lumber. The price of lumber has gone up. The solution should be to:
  1. Force builders to build fewer homes and buildings, or to
  2. Help lumber growers grow more and/or help builders find substitutes for lumber.
F. There is a shortage of computer chips. The price of everything that uses computer chips has gone up. The solution should be to:
  1. Force manufacturers use fewer chips, or to
  2. Help computer chip manufacturers produce more chips
G. There is a shortage of household goods needing raw paper or cotton: diapers, incontinence supplies, sanitary napkins and tampons, and toilet paper. The solution should be to:
  1. Make people use fewer diapers, fewer incontinence supplies, fewer sanitary napkins and tampons, and less toilet paper, or to
  2. Help manufacturers produce more diapers, incontinence supplies, sanitary napkins and tampons, and more toilet paper.
H. There is a shortage of labor. The price of labor has gone up. The solution should be to:
  1. Force labor to accept lower wages, or to
  2. Help employers pay higher wages so more people will want to work.
THE ANSWERS: If you think that in all cases, answer #2 is the correct way to cure inflation without causing a recession, you are correct. Congratulations, you are smarter than Fed Chairman Jerome Powell. Incredibly, Powell thinks the answers all should be #1. He says the economy is “overheated” (whatever that means), and the solution to inflation without a recession is to “cool” the economy (whatever that means). So he raises interest rates and takes dollars from the economy. By his actions, he is trying to force people to eat less, drive less, heat their homes less, ship less, build and buy fewer homes and buildings, buy less of everything that uses computer chips, use fewer tampons and less toilet paper, and work for lower wages,. And these are the so-called “solutions” from Chairman Powell and his acolytes. Really? Yes, really, That is exactly what “cooling the economy” means. We know that Chairman Powell has dozens (hundreds?) of economists working for him, and we assume at least some of those economists see their own data, which we will share with you here:
This image has an empty alt attribute; its file name is image-1.png
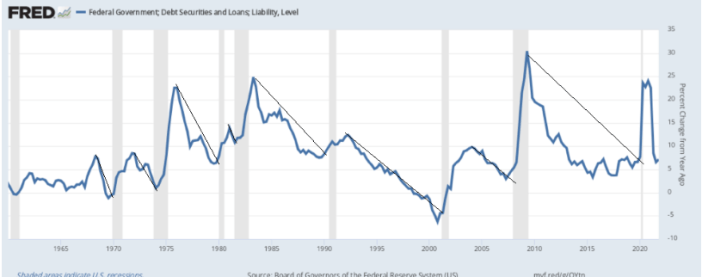
Federal deficit spending growth (blue line) and recessions (vertical gray bars)
Every recession begins after a period of reduced federal deficit spending growth. Every recession is cured by a period of increased federal deficit spending growth. Chairman Powell wishes to reduce federal deficit spending growth. What does history say about that? If Chairman Powell truly wants to prevent a recession, he should recommend that Congress and the President spend to help cure the abovementioned shortages. The very last thing Powell ever should do is make curing the shortages more difficult. All of the #2 answers require increased deficit spending by the federal government For some unknown reason, Chairman Powell seems to believe that federal deficit spending causes inflation. We have no idea how he developed that belief since it is exactly opposite to his own statistics: Here is the Federal Reserve graph comparing deficit spending with inflation:
Federal deficit spending (blue line) vs inflation (red line).
If federal deficit spending (blue line) caused inflation (red line), we would expect the blue and red lines to be essentially parallel. But that is nothing like what Chairman Powell’s own data show us. According to the Fed’s data, federal deficit spending and inflation mostly move in opposite directions. Surely, nothing says that federal deficit spending causes inflation or “overheats” the economy. The notion that “too much” federal deficit spending causes inflation is a myth, an illusion caused by the reaction of some governments to inflation.

Example: The notorious Zimbabwe hyperinflation was created when the government took farmland from farmers and gave it to people who didn’t know how to farm. The predictable result: A food shortage. The price of food skyrocketed.

Rather than spend to help farm owners grow more food, the government simply printed currency in higher denominations. This did nothing to cure the food shortage and its resultant inflation, but it created the illusion that currency printing caused the inflation.

All hyperinflations in history have followed the same scenario: Shortages cause higher prices; the government prints currency rather than curing the shortages.

Deficit spending to increase supplies of goods and services, instead of merely printing currency, is the way to cure inflation without causing a recession. Deficit spending prevents recessions and grows the economy, which is exactly what it did during the COVID crisis. Were it not for federal deficit spending, we would have had a COVID depression in 2020 and 2021. Today, the federal government should increase deficit spending to prevent recession, while using those additional dollars to encourage more farming, oil and gas drilling and refining, renewable energy production, sales of cars and motorcycles, home building, lumber growing and harvesting, and lumber-substitute development, computer chip manufacturing, and more people to join the workforce. The latter can be accomplished by ending the FICA tax and raising the minimum standard deduction. Additionally, the federal government should fund Medicare for All, which would reduce employment costs for employees and employers. Further, because the U.S. federal government is Monetarily Sovereign, deficit spending is not “paid for” by federal taxes. The U.S. federal government pays for all its spending by creating new dollars, ad hoc. Even if the federal government collected $0 in taxes, it could continue to deficit spend, forever. (A little secret: The federal government destroys all the tax dollars it receives, creating new dollars as needed.) The purpose of federal taxing is not to provide the government with the dollars it spends, but rather to control the economy by taxing what the government wishes to discourage, and by giving tax breaks to what it wishes to encourage. In the unlikely event that America can escape inflation without suffering a recession, it will not be because of what Chairman Powell is doing. It will be despite what Chairman Powell is doing. Fasten your seat belts. Powell doesn’t know what he is doing.

[No rational person would take dollars from the economy and give them to a federal government that has the infinite ability to create dollars.]

Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

………………………………………………………………………

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:
  1. Monetary Sovereignty describes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”
Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps: Ten Steps To Prosperity:
  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 
The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY

How we should prevent inflation, recession, and depression, all at once and forever.

For over a decade, we have experienced powerful economic growth and low inflation, for which the Congress and Presidents Trump’s and Biden’s administrations have taken credit.

Now, COVID has changed everything. Growth has leveled off and inflation has soared.

Economic growth is shown as the Dow Jones Composite Average (blue). Inflation is shown as the Consumer Price Index for All Urban Consumers (red).

So, the bad news has everyone wrongly looking to the Federal Reserve for a solution and to blame.

Solving, for instance, a medical problem, requires dealing with the symptoms or the causes. Dealing with symptoms works when the symptoms are relatively mild, but when symptoms are severe, one must determine the causes, and address them.

The symptom of a mild ache temporarily can be addressed with asperin. But if the pain is severe, and the cause is a broken leg, aspirin may not be the best solution.

In that vein, I submit that slow growth and inflation are not problems in themselves, but rather are symptoms of more serious underlying problems that beg for solutions.

Unfortunately, Congress has stepped back and claimed that the problems must be interest rates that are too low, and money creation that is too high, and therefore the Fed is officially tasked with curing what ails us.

The Fed has two big jobs and is failing at one of them
Neil Irwin

The Federal Reserve has been assigned a task by Congress that is easy to describe, yet fiendishly difficult to achieve. It’s known as the dual mandate: to achieve both price stability and maximum employment.

“Price instability” (in this case, inflation) is a symptom. Inflation is caused by shortages of key goods and services, which are not controlled by the Fed.

“Maximum employment” (a proxy for economic health) also is not under the Fed’s control.

The Fed’s tools are interest rates and to a slight degree, money supply. Neither tool cures shortages. While money supply does affect economic health, the Fed has much less control over money supply than does Congress.

In short, Congress and the President have total control over the Fed’s dual mandate, control the Fed does not have.

Nevertheless, the politicians find the Fed a convenient whipping boy for any financial problems, while claiming credit for any financial successes.

The Fed goes along with the ruse, perhaps because it enjoys the appearance of power the dual mandate provides.

The formal, legal language of the mandate comes from the Federal Reserve Reform Act of 1977, which says the central bank must steer credit and money supply “to promote effectively the goals of maximum employment, stable prices, and moderate long-term interest rates.“

The part about “moderate long-term interest rates” hasn’t been a problem in recent decades, which leaves open the question of what counts as “maximum employment” and “stable prices.” The Fed has a great deal of leeway to interpret those goals.

How it works: The central bank now formally defines price stability as an inflation of 2% per year, as measured by the core personal consumption expenditures price index.

This is the part where the Fed is failing. Inflation was up 5.4% over the 12 months ended in February, far overshooting the central bank’s target, though by less of a margin than the more widely covered Consumer Price Index.

The definition of “maximum employment” is more squishy. Median official Fed estimates show the longer-run unemployment rate is 4%, though policymakers also emphasize a lot of uncertainty around how low unemployment can go without sparking excessive inflation.

Though “policymakers” (Congress and the President) recognize that low unemployment, i.e., a shortage of labor, is one of the shortages that lead to inflation, they still insist that the Fed use its interest rate and money-creation tools, rather than curing the shortage.

Our Monetarily Sovereign federal government has neither the need for, nor the use of tax dollars. It creates all the dollars it uses, ad hoc, by paying bills.

So, for example, eliminating the useless and regressive FICA tax would relieve employers of a significant employment cost while allowing for substantial salary increases at no cost.

Additionally, if the federal government offered Medicare for All, with no deductibles, employers would be relieved of that cost, too, further allowing them to raise salaries at no cost while attracting more employees.

Putting more dollars into employees’ pockets, at no cost to employers, is one good way to encourage more people to go to work, i.e reduce the labor shortage that is one cause of today’s inflation.

The view at the Fed at the moment is that the job market is too hot — “tight to an unhealthy level,” as Chair Jerome Powell put it in his news conference last month.

Between the lines: Powell and his colleagues are hoping the labor market is so robust they can slow demand just enough that labor shortages and inflationary pressures abate — but employers keep hiring, and the jobless rate doesn’t rise much.

“Slow demand” is another term for “start a recession.” It’s based on the belief that the opposite of “inflation” is “recession,” which is just plain ignorant economics.

The opposite of inflation is deflation, which is accomplished by moving away from shortages toward surpluses.

Slowing demand, which the Fed wants to instigate by cutting the money supply, always leads to recessions if we are lucky and depressions if we are not.

This image has an empty alt attribute; its file name is image-1.png
Every recession (vertical gray bar) is preceded by reductions (diagonal lines) in federal deficit spending growth (blue line).

Fed President Mary Daly said in a recent speech. “It was critical to assist the economy in recovering the job losses that occurred early in the pandemic, and it is now critical to stem what has been a longer-than-expected run of high inflation.”

Ms. Daly may claim that the Fed assisted the economy to recover from job losses, and now is in a position to stem inflation.

That is like the child sitting in the back seat of a car with his toy steering wheel, and claiming that he is driving the car.

In reality, the economy recovered from job losses because the President and Congress pumped in trillions of stimulus dollars.

The inflation can be stemmed, without starting a recession, only by relieving the COVID-based shortages of oil, food, computer chips, lumber, labor, and many imported goods.

The shortage of oil can be addressed by federal funding for drilling, drilling materials, labor, solar energy, geothermal energy, wind energy, electric cars, etc.

What’s next: Over the coming months, with supply chains stabilizing, fiscal stimulus fading, and the Fed doing its job of slowing demand, there is good chance inflation will start to come down.

Since when is “slowing demand” (i.e. causing slower economic growth) the Fed’s job? Why is economic growth the devil, when inflation is the real devil? The two are completely different, as we can, and often have had one without the other.

When we have economic growth without inflation, that is termed “a healthy economy.” When we have inflation without economic growth, that is termed “stagflation,” which easily transitions to full blown recession and depression.

Thus, there is a strong chance that the Fed’s “job of slowing demand” will cause a recession.

The question is whether it comes down quickly enough and decisively enough to give the Fed comfort that it doesn’t need to cause an outright crash in the job market to speed things along.

It’s astounding that the Fed’s solution to inflation could cause a “crash in the job market,” (mass unemployment). Is this the best that all those highly paid economists can do?

The solution to inflation is to cure the causes of inflation, i.e. shortages, not to wreck the economy by cutting demand.

The bottom line: The Fed has two jobs, and is currently coming up short at one of them. It is unclear whether it can fix one side without messing up the other.

The real bottom line: This is what the Fed really was designed to do:

    1. Supervise and regulate banks and other important financial institutions to ensure the safety and soundness of the nation’s banking and financial system and to protect the credit rights of consumers.
    2. Maintain the stability of the financial system and contain the systemic risk that may arise in financial markets.
    3. Provide certain financial services to the U.S. government, U.S. financial institutions, and foreign official institutions, and play a major role in operating and overseeing the nation’s payments systems.Only later did Congress and the President sneak in a fourth responsibility:
    4. Conduct the nation’s monetary policy by influencing money and credit conditions in the economy in pursuit of full employment and stable prices.

Essentially, the Fed was designed to do one job: Control the banking/financial system. Congress and the President are responsible for the economy.

Foisting the inflation, deflation, recession, depression, employment, unemployment, and economic growth jobs on the Fed was an admission by Congress and the President that they are not competent to do exactly what they were elected to do: Improve the lives of the governed.

It’s an admission that our recalcitrant, fractious political system cannot cope with the major problems of the day, and that some politically insulated agency must carry the water when our elected officials are more interested in winning elections than in doing their jobs.

SUMMARY

Today, our economic problems center on inflation and slow growth.

But inflation is a symptom; shortages are the cause. Slow growth is a symptom; lack of money is the cause.

The Fed’s primary tools are limited to interest-rate and a minimal money-supply control, both of which are designed to treat the symptoms, not the shortages.

Sadly, the Fed wrongly believes economic growth causes inflation, so it will use its limited tools to force reduced economic growth, and most likely, recession, while the basic causes of inflation will remain.

So, because of economic ignorance, we will endure stagflation.

Spending to cure the shortages would cure both the inflation and the slow growth, but Congress and the President, which solely have the curative power, have abdicated their responsibility.

So, as always, we will bounce from boom to bust in a neverending cycle of incompetence, while the people suffer.

==============================================================

MORE ABOUT SHORTAGES

Historic fertilizer shortages threaten world’s food security
Elizabeth Elkin and Samuel Gebre, Bloomberg News
For the first time ever, farmers the world over — all at the same time — are testing the limits of how little chemical fertilizer they can apply without devastating their yields come harvest time. Early predictions are bleak. 

In Brazil, the world’s biggest soybean producer, a 20% cut in potash use could bring a 14% drop in yields, according to industry consultancy MB Agro.

In Costa Rica, a coffee cooperative representing 1,200 small producers sees output falling as much as 15% next year if the farmers miss even one-third of normal application.

In West Africa, falling fertilizer use will shrink this year’s rice and corn harvest by a third, according to the International Fertilizer Development Center, a food security non-profit group.

Soaring prices for synthetic nutrients will result in lower crop yields and higher grocery-store prices for everything from milk to beef to packaged foods for months or even years to come across the developed world.

More fertilizer use brings more food production.
But as costs for synthetic nutrients have skyrocketed — in North America, one gauge of prices is nearly triple where it was at the start of the pandemic — farmers have had to start paring back use, sometimes dramatically.

—//—

Gulf of Mexico drilling makes too-little, too-late comeback
Paul Takahashi, Bloomberg News
A new wave of oil platforms is sweeping into the U.S. Gulf of Mexico as crude prices are riding historic levels and demand for barrels is higher than ever.

But don’t count on the new production to close the oil-supply gap that has plagued the world’s economies since the pandemic. Even with the new platforms coming online, gulf oil production won’t grow substantially in the coming years as mature fields decline, according to analysts.

—//—

Can’t find chicken wings, diapers, or a new car? Here’s a list of all the shortages hitting the reopening economy.
Juliana Kaplan and Grace Kay May 25, 2021, 9:54 AM

Computer chips, used and rental cars, gas and oil, plastics, palm oil, truckers, rideshare drivers, homes, vacation houses, lumber, toilet paper. tampons, furniture, chicken, bacon, hot dogs, imported foods like cheese, coffee, olive oil, chlorine, corn, oxygen, labor

And none of these inflation-causing shortages, which affect virtually everything you buy, will be cured by the Fed.

Rodger Malcolm Mitchell
Monetary Sovereignty
Twitter: @rodgermitchell
Search #monetarysovereignty
Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:

  1. Monetary Sovereigntydescribes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”

Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps:

Ten Steps To Prosperity:

  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9%

The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY

Why we will have a recession this year

We are on track to sliding into a recession if we are lucky, or into a depression if we are not. It all is due to a massive misunderstanding about the role of the Federal Reserve, Congress, and the President with respect to inflation.

The Fed blame game Neil Irwin, AXIOS

It is the high season for being mad at the Federal Reserve.

Critics accuse them of being feckless as inflation pressures built last year, and as a result, the United States is facing prolonged high inflation, a painful recession to rein it in — or both.

Why it matters: In reality, the Fed didn’t create the current inflationary surge by itself— but it was too complacent as prices spiked last year.

Fact: Not only did the Fed not create the current inflationary surge by itself, but as we shall see, the Fed wasn’t at all responsible for today’s inflation.

Now the economic future depends on its ability to make up for lost time, and navigate a tightrope-thin path to bringing inflation down without tanking the economy.

Fact: It is not up to the Fed to bring inflation down. It doesn’t have the tools.

The Fed always takes heat for its decisions. That is to be expected when a handful of technocrats make decisions, behind closed doors, that shape a $24 trillion economy.

As you will see, the fault for inflation lies not with the Fed, but with a bunch of politicians — Congress and the President — and circumstances.

What is notable is how the most mainstream of economic commentators are piling on. The Economist’s recent cover called it “The Fed that Failed.”

Bloomberg published an essay headlined “The Fed Has Made a U.S. Recession Inevitable” — written by the former president of the New York Fed.

Blaming the Fed for inflation is like blaming the phone company for 911 calls. There is no cause/effect between the problem and a tangentially related agency.

Flashback: Last year, even as inflation started to surge, the Fed kept its aggressive monetary stimulus — interest rates near zero and buying billions of dollars in bonds — in place, only ending it last month.

This infers the commonly believed myth that low interest rates and increased money supply cause inflation.
From 1960 through 2009, interest rates were relatively high (compared to current rates) and inflation also was relatively high.
.
Beginning in 2009, interest rates had been low as had been inflation
In reviewing the above two graphs, it is difficult to infer that high interest rates prevent inflation and low interest rates cause inflation. In fact, one more easily could infer that inflation causes high rates simply because the Fed believes in raising rates when inflation threatens. We have what amounts to a self-fulfilling prophecy by the Fed. And also:
Changes in the M2 money supply do not parallel changes in inflation.
From the above graph, one would have difficulty inferring that “excessive” money creation causes inflation. So if low interest rates and “excessive” federal money creation don’t cause inflation, what does?

Insiders at the central bank don’t really dispute that they should have begun withdrawing that stimulus earlier.

The Fed was lulled by the fact that the initial surge of inflation last spring was concentrated in a handful of categories, then by a temporary softening in inflation last summer.

Those “insiders” should dispute the notion that should have begun withdrawing stimulus (taking dollars from the economy) earlier. Had they done what they now believe they should have done, we would be in the midst of a recession, or more likely, a depression.

“We don’t have the luxury of 20/20 hindsight in actually implementing real-time decisions in the world,” Chair Jerome Powell said at a news conference last month.

Had they known how persistent inflation would be, Powell added, “then in hindsight, yes, it would have been appropriate to move earlier.”

Wrong. They do have the benefit of 20/20 hindsight, because this hindsight now shows no cause/effect relationship between interest rate increases and inflation decreases, nor does it reveal a cause/effect between money creation and inflation.

At the same time, it’s not clear that inflation right now would be radically different in an alternate universe where they had moved to tighten money earlier.

Right. It’s “not clear” because tightening money would not have reduced inflation, but would have destroyed the economy. To control inflation, one must control the true cause of inflation, and the true cause of inflation is not low interest or high money supply.

“It is unlikely that the Fed could have lowered the inflation rate in 2021 because the fiscal support was so massive and its tools work with a lag,” Jason Furman, the Harvard economist and former White House economist, tells Axios.

Wrong., “Fiscal support” and “lag” are not the issues.

But by not acting sooner, the Fed has increased the risk that inflation will remain high through 2022, and beyond, he said: “If it had been more aggressive last year, we would be seeing the effects more this year.”

If the Fed had been more aggressive last year (in cutting the money supply while raising interest rates), we would have seen the effects last year: Recession and or depression. Consider this admission from the article’s author, Neil Irwin:

Countries with central banks that did tighten faster are also experiencing high inflation. (In New Zealand, which raised rates back in October, it’s 6.9%.)

Wait! What? If countries that did tighten faster also are experiencing high inflation, why doesn’t that give the Fed, Congress, the President, the economists, the media, and Mr. Irwin a clue?

Moreover, there is a risk that if they had moved more aggressively last year, it would have slowed the rapid recovery without improving the inflation results very much, given the unusual mix of factors around the supply chain disruptions that are driving higher prices.

Right. There is a mix of factors driving higher prices, and those factors all can be summarized in one word: Shortages. And there you have it. Inflations — all inflations — are caused by shortages of key goods and services. Not by too much money, not by too-low interest rates: All inflations are caused by shortages, and all inflations are cured by curing the shortages. And often, these shortages can be cured by additional, not by less, money creation.

Today’s inflation is caused by shortages of food, energy (mostly oil but also other forms of energy), shipping, computer chips, labor, and all the thousands of related products.

Food prices have risen because food is in short supply. Food is in short supply, not because the government added dollars to the economy, and not because people suddenly are eating more, but because of COVID and weather, and related shortages of labor, equipment, fertilizer, and other farming needs. One does not cure a food shortage by starving the populace. One cures a food shortage by growing more food. Energy is in short supply because the energy suppliers can’t obtain sufficient materials and labor to extract the oil, gas, and coal we need. This is related to COVID and lately, the Russia/Ukraine war. One does not cure an energy shortage by forcing the nation to use less energy. One cures an energy shortage by creating more oil, gas, wind, geothermal, and solar energy. Everything in our economy is inter-related. We are now short of homes, not because more people suddenly want homes, but because builders, who are short of labor and materials, can’t build fast enough. So home prices are soaring. The cure for a shortage of homes: Fund the building of homes via appropriate tax cuts for all the home-building-related industries. The list goes on and on, with the main culprits always being the same: Shortages, due not to increased demand but to decreased supply. The cure for a shortage: Increase the supply.

“I guess, with perfect hindsight, perhaps we would’ve moved to a contractionary policy stance to try to offset some of the supply chain issues and to offset the strong demand from the fiscal stimulus,” Minneapolis Fed President Neel Kashkari tells Axios.

“Offsetting supply issues” with a contractionary policy stance (i.e. creating a recession) is like starving the people as a cure for a food shortage.

But, he added, “I’m a little bit cautious about saying, ‘Boy, we should have just tightened earlier,’ because if the inflation’s being driven by … supply-side factors, it’s not clear what the benefit of that would’ve been.”

It should be clear that there would have been no benefit at all — just punishment of the private sector.

Yes, but: The real risk is that by waiting as long as it did to pivot to tighter money, the Fed will have to move so quickly to catch up that it triggers a breakdown, as the economy struggles to adapt to a world of less abundant cash.

When the Fed moves with maximum speed, consumers and businesses have less time to adjust to higher rates on all sorts of debt.

Time is not the issue. If cash is less abundant, the economy cannot adapt, slowly or quickly. When federal deficit spending does not increase sufficiently, we have recessions. Period. Starving the economy of money is the issue. Fast starvation or slow starvation, both ultimately produce starvation.
When federal debt growth (purple line) declines we have recessions (vertical gray bars), which are cured by increased federal debt growth.

At its meeting that concludes this coming Wednesday, the Fed is likely to begin its catch-up process in earnest by raising short-term interest rates half a percentage point and commencing with shrinking its balance sheet by up to $95 billion a month.

To “shrink its balance sheet,” the Fed must pull money from the economy. That’s $95 billion removed from the private sector (i.e. the economy) every month. That absolutely, positively will have a depressive effect on economic growth. 

The shift toward tighter money has rapidly spread out across lending markets. The average rate on a 30-year fixed-rate mortgage has soared from 3.11% at the end of last year to 5.10% now.

And still, we have inflation because the problem is not low interest rates. The problem is shortages. Cure the shortages and you cure inflation. This is a situation where the government should throw money at the problem. Give the oil companies money on the condition they use it to raise salaries (to attract more people) and to purchase equipment.
Inflation (red line) parallels oil prices (blue line). Increase the supply of oil and you decrease the price of oil, which will decrease inflation.
Give farmers higher supplements and tax breaks for growing, and cut supplements for not growing. Similarly fund the building trades, purchase computer chips using the government’s unlimited funds, aid the shipping industries, all with direct supplements and tax breaks. Meanwhile, eliminate the FICA tax to encourage management to hire, and and lower income taxes to encourage more people to come back to work. Also, provide Medicare for All, taking that financial burden off corporations, to encourage hiring.

The bottom line: The Fed spent last year driving their metaphorical car at full speed, not realizing that they were entering a dangerous, curvy stretch of road. The road would still be dangerous no matter what.

The mistake was not slowing down sooner — making for a high risk of crashing. And we’re all in the car.

No, the mistake was driving their metaphorical car in the wrong direction. They already have the map in hand. They merely have to use it, and not stubbornly drive faster toward the east, when the goal is west. Another metaphor: Trying to cure inflation by cutting the money supply is like trying to cure anemia by applying leeches. IN SUMMARY Inflation is a supply problem; inflation is not a demand problem. Today’s inflation is caused by shortages of food, energy (mostly oil but also other forms of energy), shipping, computer chips, labor, and all the thousands of related products. To cure inflation one must cure the shortages by increasing the supply. There is no other rational solution. Attempting to cure inflation by cutting demand will result in recession or depression. There is no other outcome.  The U.S. government is Monetarily Sovereign, meaning it has all the tools it needs in order to increase the supply of scarce goods and services. Congress and the President control the U.S. government, so they, not the Fed, are responsible for preventing, causing, and/or curing inflations, recessions, and depressions.

……………………………………………………………………..

[No rational person would take dollars from the economy and give them to a federal government that has the infinite ability to create dollars.] Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell

……………………………………………………………………..

THE SOLE PURPOSE OF GOVERNMENT IS TO IMPROVE AND PROTECT THE LIVES OF THE PEOPLE.

The most important problems in economics involve:
  1. Monetary Sovereignty describes money creation and destruction.
  2. Gap Psychology describes the common desire to distance oneself from those “below” in any socio-economic ranking, and to come nearer those “above.” The socio-economic distance is referred to as “The Gap.”
Wide Gaps negatively affect poverty, health and longevity, education, housing, law and crime, war, leadership, ownership, bigotry, supply and demand, taxation, GDP, international relations, scientific advancement, the environment, human motivation and well-being, and virtually every other issue in economics. Implementation of Monetary Sovereignty and The Ten Steps To Prosperity can grow the economy and narrow the Gaps: Ten Steps To Prosperity:
  1. Eliminate FICA
  2. Federally funded Medicare — parts A, B & D, plus long-term care — for everyone
  3. Social Security for all
  4. Free education (including post-grad) for everyone
  5. Salary for attending school
  6. Eliminate federal taxes on business
  7. Increase the standard income tax deduction, annually. 
  8. Tax the very rich (the “.1%”) more, with higher progressive tax rates on all forms of income.
  9. Federal ownership of all banks
  10. Increase federal spending on the myriad initiatives that benefit America’s 99.9% 
The Ten Steps will grow the economy and narrow the income/wealth/power Gap between the rich and the rest.

MONETARY SOVEREIGNTY