Inflation is not an increase in one commodity’s price. It is a general increase in prices. Inflations tend to begin quickly and end slowly.
Fiscal policy is enacted by the legislative branch of government and deals with tax policy and government spending.
Monetary policy is enacted by a government’s central bank and deals with changes in the money supply by adjusting interest rates, reserve requirements, and open market operations.
Monetary policy involves changing interest rates and influencing the money supply.
Fiscal policy involves changing tax rates and levels of government spending to influence aggregate demand in the economy.
Congress and the President have given the Federal Reserve a mandate for maximum employment and price stability.
Given the Fed’s limited control over consumer and business pricing, this is akin to giving the shortstop a mandate for the team to win the World Series.
Any single business will raise its prices based on several factors, which include:
Increased costs
Reduced competition
Product improvements
New markets open up
Fed Chair Jerome Powell
The Federal Reserve, being a monetary organization, views inflation as being a monetary problem. So, it attempts to fight inflation with a monetary solution: Increased interest rates.
The Fed’s hypothesis is that increasing interest rates will discourage buyers, thus reducing demand. The demand reduction supposedly forces businesses to reduce prices to capture the remaining customers.
This, in turn, forces a reduction in business profits available to spend on employment, marketing, production, and research/development.
The formula for Gross Domestic Product (GDP), one of the most important measures of our economy is:
GDP = Federal Spending + Non-federal Spending – Net Imports
The United States is a huge consumer of goods and services so it tends to import more than it exports.
Thus, for real (inflation-adjusted) GDP to grow, either Federal Spending or Non-federal Spending must grow enough to overcome inflation and Net Imports.
However, if the Fed’s interest rate increases are successful in reducing demand, two things will happen:
Non-federal Spending will decline and
Business costs will rise
The first will cause a recession unless Federal Spending increases enough to overcome inflation and the dollar losses from Net Imports.
The second will exacerbate inflation.
However, the consensus among economic pundits — including the Fed — is that increased Federal Spending causes inflation.
No matter what the Fed’s interest rate hikes do — raise business costs or cut consumer spending — the result will be inflation and/or recession.
Only if the Fed’s rate cuts don’t work will we be spared inflation and/or recession — unless Congress and the President keep pumping growth dollars into the economy.
To cure inflation, without recession, the economy needs more growth dollars that address the true cause of inflation: Shortages of critical goods and services.The Fed’s website says, “The Federal Reserve The Federal Open Market Committee (FOMC) judges that an annual increase in inflation of 2 percent in the price index for personal consumption expenditures (PCE), produced by the Department of Commerce, is most consistent over the longer run with the Federal Reserve’s mandate.”
Two inflation measures, the Consumer Price Index (CPE-red), and Personal Consumption Expenditures (PCE-blue) track similarly. It’s not clear why the blue line is more “consistent with the Federal Reserve’s mandate.”
Another strange comment from the Fed: “Although food and energy make up an important part of the budget for most households–and policymakers ultimately seek to stabilize overall consumer prices–core inflation measures that leave out items with volatile prices can be useful in assessing inflation trends.”
Really? Look at this graph and see if you can see why so-called “core inflation” is useful.
The red line is Personal Consumption Expenditures. The blue line is “Core” Personal Consumption Expenditures.
Does anyone believe the Fed’s predictions are so precise that the blue line is more “useful in assessing inflation trends”? I mention this only to demonstrate how the Fed’s historical beliefs sometimes ignore facts.
No matter which measure the Fed leans toward, one thing is clear: To succeed, the Fed must fail.
Its interest rate increases must fail to increase business costs (or prices will increase).
Its interest rate increases must fail to reduce Non-federal Spending (or GDP will decrease).
Its cajoling of Congress to reduce Federal Spending must fail to cause a recessionary reduction in GDP
In short, the Fed must fail in everything it does, and if it fails, and the recession ends despite what the Fed does, Chairman Powell will boast that he took the economy to a “soft landing.”
Powell is the player who after he strikes out, the catcher drops the ball, and the winning run scores. So he brags about his winning the game.
The facts:
The best way to cure a problem is to cure the cause of the problem.
The cure for shortages is Federal Spending to encourage the production of, and/or access to, the scarcities that cause inflation.
Federal deficit Spending adds growth dollars to GDP, thereby curing inflation while preventing recession.
Oil shortages are the most common cause of inflation. Oil supply changes quickly. OPEC can affect supply in a day, Oil demand changes slowly. Oil prices (green) parallel inflation (purple), which generally comes on quickly, but can leave slowly if oil shortages are not cured. Oil prices affect the prices of nearly every other product.
No “soft landing” was necessary. No “landing” at all was needed. Congress and the President control the fiscal policy that controls supply.
The economy does not need or want increased interest rates. The federal government should:
Increase Federal Spending to support oil drilling and refining. and increase support for research, development, production, and distribution of such renewables as wind, solar, geothermal, tidal, and nuclear fusion (not fission).
Increase Federal support for businesses raising wages by making hiring cheaper. Federal funding of all health care insurance by instituting comprehensive, no-deductible Medicare for every adult and child in America. This would relieve businesses of the payroll cost and reduce the expense of illness-related absences.
Reduce payroll costs by eliminating FICA and funding more generous Social Security benefits for every American. This also would reduce the payroll cost of employer-funded retirement plans.
Stop fobbing off the responsibility for inflation on the Fed. Instead, take responsibility for preventing/curing the shortages that cause inflation.
Stop pretending that the federal government “can’t afford” to pay for benefits or that the federal deficits and debt are dangers to our Monetarily Sovereign economy.
Federal deficit spending is necessary to prevent/cure inflations and for economic growth. The Fed’s interest rate increases must fail to succeed.
Rodger Malcolm Mitchell
Monetary SovereigntyTwitter: @rodgermitchellSearch #monetarysovereigntyFacebook: Rodger Malcolm Mitchell;MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell
……………………………………………………………………..
The Sole Purpose of Government Is to Improve and Protect the Lives of the People.
The Federal Reserve Chairman, Jerome Powell, is valiantly battling against stubborn inflation.
He raised interest rates and continues to keep them high, but no matter what he does, inflation continues to mock him.
We took this much blood out of him, but he still has anemia, so we’ll continue to draw blood until his anemia is cured.
In a related story, medical doctor Dr. Jerome Powell has been valiantly battling a patient’s anemia by applying leeches.
But, for some unknown reason, the anemia is not responding to the blood draw, so Dr. Powell will continue to apply more and more leeches.
Doctors and economists the world over wonder why drawing blood doesn’t cure anemia and increasing costs by raising interest rates doesn’t cure inflation.
Americans are falling behind on their credit card bills.
Nearly one in five credit card users have maxed out on their borrowing, according to the Federal Reserve Bank of New York.
People under 30 and those who live in low-income neighborhoods are more likely to be at or close to their credit limit.
Don’t those people realize that Jerome Powell is trying to help them pay off their loans by increasing interest rates?
The debt is a sign borrowers are feeling the strain of rising prices and high interest rates.
“Most investors now think it’s going to be September before the Federal Reserve is ready to start cutting interest rates,” NPR’s Scott Horsley tells Up First.
Yes, another couple of months of drawing blood from the patient should cure his anemia, and another couple of months of increasing prices by raising interest rates should cure inflation.
Though inflation has come down from what it was several years ago, prices are still climbing faster than most would like.
Used car salesman Jerome Powell: “We charge you the highest interest rates to make your car more affordable.”
Perhaps increasing the cost of borrowing (which virtually every corporation, farmer, home buyer, car buyer, and appliance buyer does) will cure inflation.
More than half of all credit card users pay their whole balance every month, so they’re not affected by high interest rates.
But the other half pay interest on their purchases, so they are affected.
But don’t worry, Chairman Powell assures us that raising interest rates reduces the cost of everything (with the exception of everything you buy).
Because of this, there’s no incentive to stop spending, which makes it hard to get inflation under control.
Now, if everyone simply would stop spending, the resultant recession and depression might cure inflation.
Then again, there is a thing called “stagflation,” which is a combination of inflation and economic stagnation, so maybe the recession thing isn’t such a good idea.
Oh, someone mentioned that high oil prices cause inflation and that interest rate increases exacerbate inflation.
Ah, but those people were just using facts, not rumors and beliefs, so who could trust them?
Rodger Malcolm Mitchell
Monetary SovereigntyTwitter: @rodgermitchellSearch #monetarysovereigntyFacebook: Rodger Malcolm Mitchell
……………………………………………………………………..
The Sole Purpose of Government Is to Improve and Protect the Lives of the People.
Author: Martin Hutchinson is a financial journalist based in Vienna, VA, for BreakingViews.com and others with a weekly column, “The Bear’s Lair.”
If you are a hammer, every problem is a nail, and if you are a banker, every problem is a monetary problem.
In a series of papers and speeches in the early millennium years ( 2011, Causes, Consequences, and Our Economic Future),Federal Reserve Governor Ben Bernanke outlinedwhat the Fed might do when faced with near-zero interest rates.
A distinguished historian of the Great Depression, Dr. Bernanke’s main concern was to ensure that ‘it’ never happened again, and the critical element of his program was to avert a repeat of the damaging deflation of the early 1930s.
We’ll interrupt Martin Hutchinson’s paper by reminding you that almost every recession and depression in U.S. history has been associated with reduced federal deficit spending.
These recessions and depressions were cured by increased federal deficit spending.
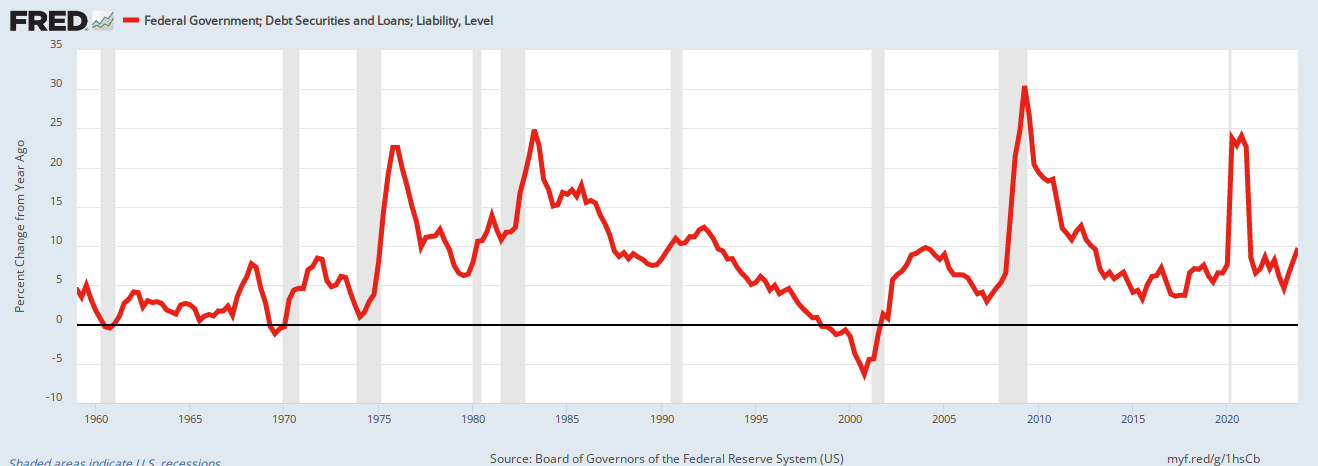
Recessions (vertical gray bars” result from federal deficit reductions (red line). Recessions are cured by increased federal deficit spending.
We have depressions when the federal government takes dollars from the economy (i.e., runs a surplus).
Fact: U.S. depressions tend to come on the heels of federal surpluses.
1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807. 1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819. 1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837. 1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857. 1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873. 1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893. 1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929. 1997-2001: U. S. Federal Debt reduced 15%. Recession began 2001.
The way to keep recessions and depressions from happening again is continually to increase federal deficit spending on domestic goods and services, which grows the economy.
GDP = Federal Spending + Nonfederal Spending + Net Exports
The policies themselves boil down to the Fed throwing everything it has into a desperate battle to avert falling prices – an attack on deflation.
With the specter of looming deflation, they also suggest that this is not a time to worry about inflation. To quote one eminent authority, using another evocative analogy, “Fear of inflation, when viewed in the context of a possible global depression, is like worrying about getting the measles when one is in danger of getting the plague.”
New conventional wisdom has thus evolved, which maintains that the current major threat is deflation rather than inflation and insists that this threat must be countered by all possible means.
Keep in mind that the paper was written in 2011.
On the contrary, we would argue that this view and its associated policies are fundamentally misconceived; they are also irresponsible and potentially highly dangerous.
First, they miss the main point as a response to the crisis (and to avert worse to come). Resolving the crisis does not require ‘stimulus’ – fiscal or monetary; nor does it require bailouts or near-zero interest rates.
Instead, the crisis can only be resolved by an appropriately radical restructuring of the balance sheets of the major financial institutions.
There it is, the hammer/nail analogy. The author believes deflation is caused by something lacking in major financial institutions’ balance sheets.
Think about it. Deflation is falling prices. What makes prices fall? It’s not “major financial institution balance sheets.” It’s reduced overall demand for goods and services.
And what reduces the overall demand for goods and services? Lack of money.
Deflation is the opposite of inflation, and what causes inflation? What causes the price of anything to rise? Supply that is less than demand for that thing.
What causes all prices to rise. More less supply than demand for critical products, notably oil and/or food.
Oil prices (red) are a good barometer for excess demand over oil supply. Because oil is the single most price-influential product in the economy, affecting almost every product and service, oil shortages cause overall inflation.
Increases in oil prices are driven by oil scarcity, which parallels inflation.
If you want to know inflation, don’t refer to “major financial institution balance sheets.” Refer to oil prices. (Oil prices, and to a lesser degree, food prices = inflation.) Notice anything missing from that equation?
Interest rates.
The Fed raised interest rates to fight inflation. The theory is that raising interest rates “cools” the economy by — by doing what? By making things more expensive.
Houses, cars, transportation- every industry- sees increased costs from higher interest rates, which are passed on to consumers.
Strangely, the Fed (and most economists, politicians, and the media) believe that making things more expensive by raising interest rates is an excellent way to fight inflation. Does that make any sense?
In essence, the Fed tries to cure anemia by applying leeches.
Yes, raising interest rates increases the exchange value of the U.S. dollar because people need dollars to purchase U.S. bonds, notes, and bills. So, as interest rates rise, the demand for dollars increases.
But that primarily affects imports and exports — making imports cheaper.
Raising interest rates makes the dollar more valuable in international trade, thus making imports cheaper when paid for in dollars.
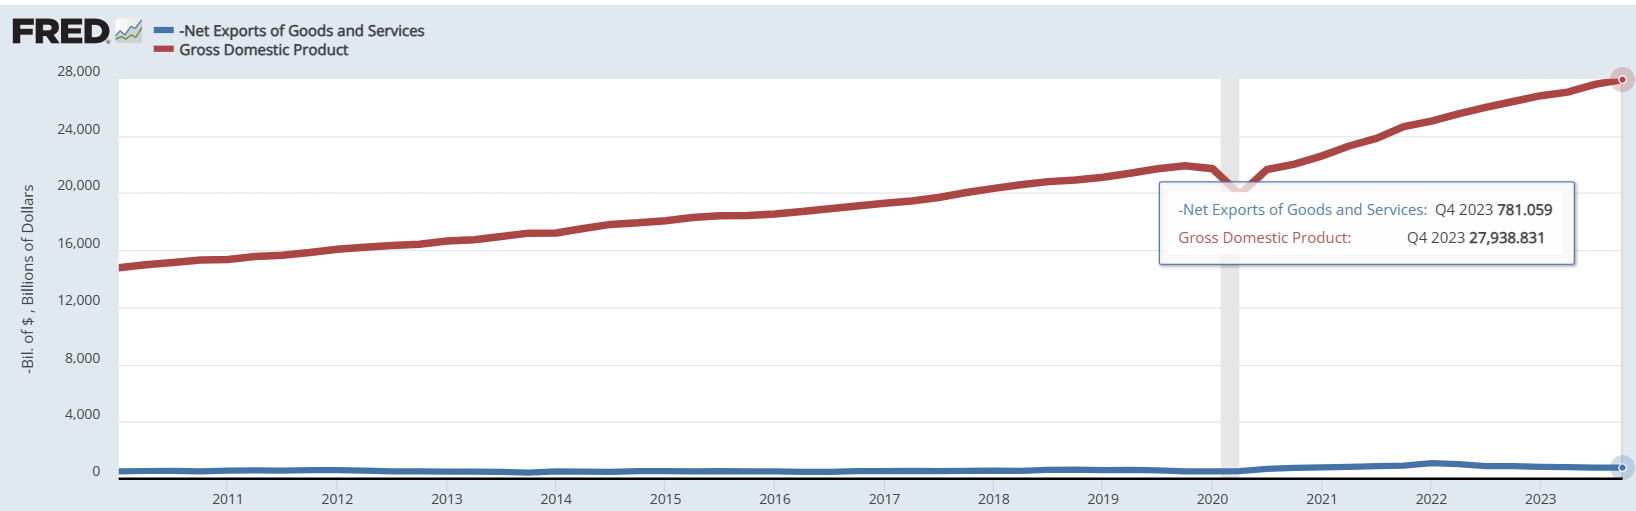
However, net imports (blue line, calculated as the inverse of net exports) are only a tiny fraction of our economy (GDP – red line).
Thus, on balance, raising interest rates increases prices. The Fed does exactly the wrong thing in its fight against inflation.
Not only is there an obvious and present danger of returning inflation, but there is also a genuine danger that the Federal Reserve will become insolvent and victim of its own policy failures.
It is impossible for any agency of the U.S. federal government, including the Federal Reserve, to become insolvent unless, for some reason, that is what Congress and the President want.
Quote from former Fed Chairman Ben Bernanke when he was on 60 Minutes: Scott Pelley: Is that tax money that the Fed is spending? Ben Bernanke: It’s not tax money… We simply use the computer to mark up the size of the account.
These words should be embedded into the brains of every economist, politician, and media writer: “WE SIMPLY USE THE COMPUTER TO MARK UP THE SIZE OF THE ACCOUNT.”
That is how the federal government creates dollars, which is why the federal government has the infinite ability to create dollars to pay its obligations.
There is no limit on the computer. Send the federal government with a $100 invoice or a $100 trillion invoice, and both could be paid instantly, simply by “using the computer to mark up the account.”
The failure to understand this fact has caused most of the world’s financial problems: Hunger, homelessness, lack of health care, lack of education, poor infrastructure, and delays in scientific innovation. The list goes on and on.
There are so many things the federal government could but doesn’t pay for because of the mistaken belief in unaffordability.
(Since 2006, we have had) an ‘accommodating’ monetary policy and this interpretation has been confirmed by strongly negative interest rates since the summer of 2008.
In the short term, this monetary growth will likely have a limited impact on inflation while the economy remains in deep recession with substantial under-utilization of resources.
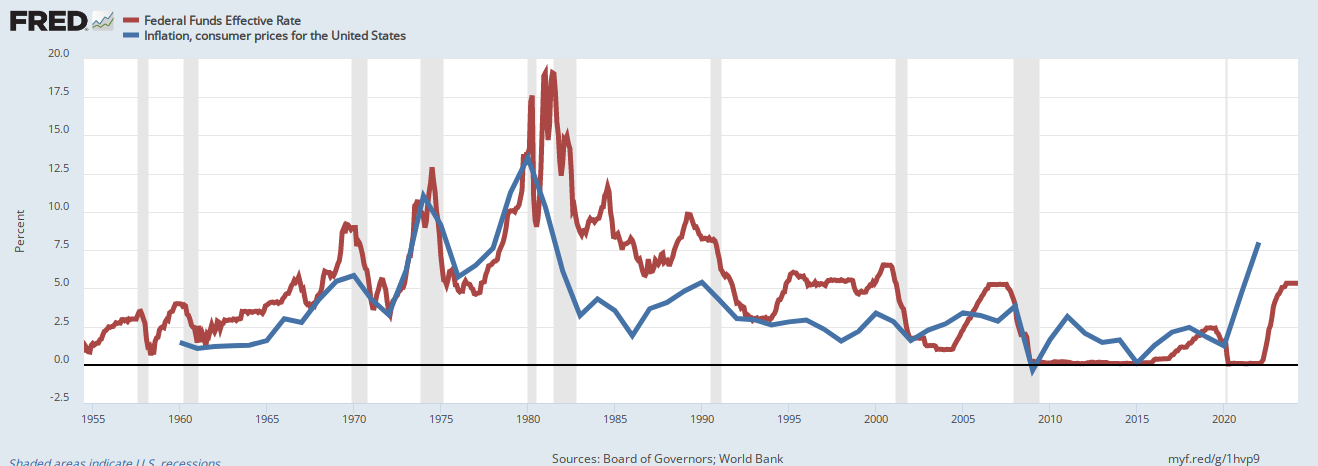
The graph shows how the Fed responds to inflation (blue) by raising interest rates (red). It also shows that low rates don’t cause inflation.
Near zero (negative real) interest rates continued well after the “deep recession,” and there was still no inflation. The reason can be seen in the oil/inflation graph above.
However, once credit markets begin to ease and confidence returns, monetary velocity will return to normal levels, possibly quite rapidly. We should expect inflation to rise again and perhaps proliferate when this happens.
We didn’t have high inflation because oil was not in short supply. We had inflation only when COVID made oil (and scores of other products and services) scarce.
As always, the bankers view inflation as a monetary problem and wish to apply monetary solutions. But inflation is a goods and services supply problem which requires a goods and services supply solution.
In 1979, there will come a point where the existing policies will be seen to have failed, and the Fed will reluctantly reverse policy – presumably under a new Chairman. The Fed will then sharply raise interest rates and force monetary growth down, and the economy will undergo another painful recession.
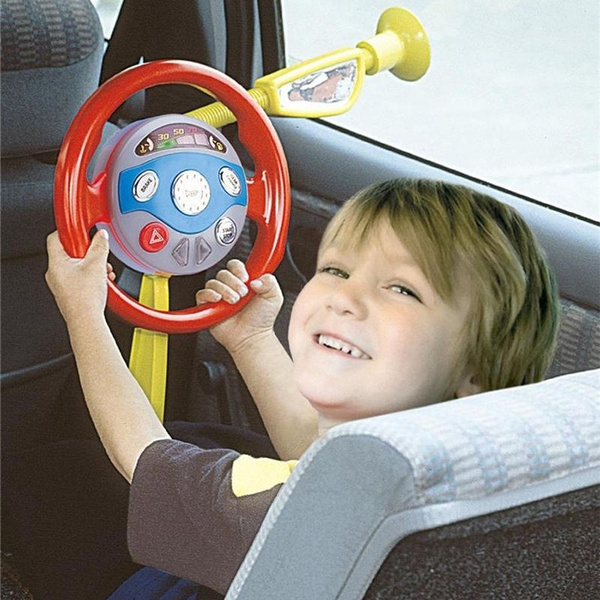
Fed Chairman Jerome Powell thinks he is driving the anti-inflation car, but the real driver is oil supplies, ruled by Congress and the President.
The Fed’s monetary bent makes for the belief that recessionary action is needed to prevent/cure inflation.
We then get into a careful balancing act in which the Fed tries to set “just enough” recessionary interest rates to cure inflation but not enough to cause a recession.
The scenario reminds one of a child sitting in the back seat of a car, thinking he is steering the vehicle.
The Fed (child) thinks it’s “steering the car,” while in the front seat, the real steering is being done by the (parent) President and Congress.
Increased federal spending to cure oil shortages and other goods and services shortages would cure inflation while preventing recession.
Ultimately, the “child” happily believes he has steered safely, while the “parent” smiles and tells the child what a wonderful job he did.
If the Fed then sticks with such a policy – as it did under Volcker – then it will gradually but painfully grind inflationary forces out of the system; if it gives up, as earlier in the 1970s, then inflation will return again, only to need further harsh monetary medicine further down the road. Welcome back, stagflation.
We didn’t have the predicted stagflation because oil supplies increased, reducing inflation. Meanwhile, the government spent enough to prevent stagnation, though declining deficits ultimately led to the 1990 recession.
Long before all that, higher interest rates would follow naturally from higher inflation expectations and the massive borrowing requirements of the US federal government.
The U.S. federal government does not borrow dollars. Not now. Not ever. Why would it, given its infinite ability to “use the computer to mark up the account,” as Bernanke said.
Former Fed Chair Alan Greenspan: “A government cannot become insolvent with respect to obligations in its own currency. There is nothing to prevent the federal government from creating as much money as it wants and paying it to somebody. The United States can pay any debt it has because we can always print the money to do that.”
The author thinks Treasury bonds, notes, and bills are “borrowing” because those terms describe private sector borrowing.
But Treasury bonds, notes, and bills are accounts owned by depositors, not by the government. The accounts resemble safe deposit boxes, the contents of which are owned by account holders, not by the bank.
Upon maturity, the contents of T-security accounts simply are returned to the owners, having never been touched by the federal government. No government money is involved.
The purpose of T-securities is not to provide spending funds to the government. The government has infinite spending funds. Instead, the purposes are:
To provide a safe storage place for unused dollars. This stabilizes the dollar.
To help the Fed control interest rates.
The dollar’s value is determined by relative inflation rates: if the US inflates more than its trading partners – as seems likely – then the dollar must eventually fall.
The Fed’s manipulation of interest rates determines the dollar’s exchange value. The Fed decides what the rate will be. Raising rates increases demand for the dollar, which increases its value.
As described earlier, this exacerbates inflation by raising the price of goods.
The fundamental determinant of inflation is the supply of crucial goods and services, predominantly oil and food.
But there are also substantial speculative dollar holdings. As of May 2009, approximately $3.3 trillion of the $ 6.9 trillion of Treasury securities outstanding were held by foreigners, of which $ 2.3 trillion were held by foreign central banks.
As the dollar falls, foreign holders of Treasuries are likely to begin selling. These holdings represent a dangerous overhang, the unraveling of which could cause a sharp decline in the dollar’s value once foreign exchange markets start to correct themselves; thus, the ingredients are already in place for a major dollar crisis.
If every single holder of Treasury bonds, notes, and bills sold their holdings, the bonds, notes, and bills would continue to exist, only in different hands.
The Fed could continue to control interest rates by fiat or open market purchases (aka “quantitative easing”). There would be no crisis.
It’s like asking what would happen if every safe deposit box holder sold the contents of his box. The answer: A lot of new people would own those contents.
The bleak prognosis just described amounts to a return to the miseries of stagflation.
This happens when the Fed tries to cure inflation by raising interest rates. The higher interest rates exacerbate inflation and stagnate the economy.
In principle, of course, such an outcome can be averted (or at least ameliorated) if the Fed moves quickly to claw back the growth in the base before its inflationary potential is fully unleashed.
Still, in practice, this would be very difficult to do.
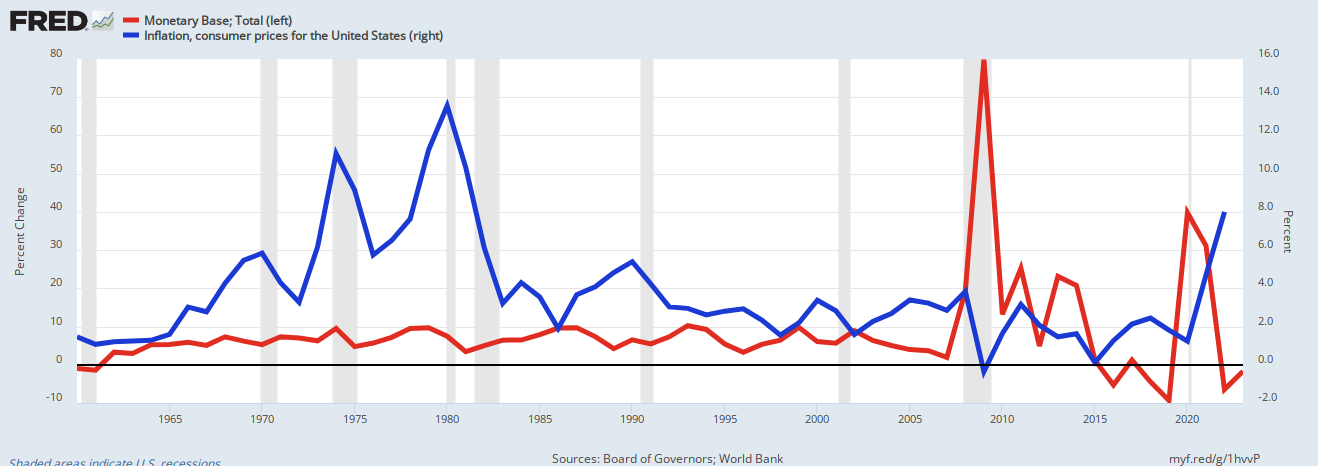
Here, the author claims that growth in the monetary base causes inflation. See the following graph:
Growth in the monetary base (red) does not cause inflation (blue).
As usual, the bankers erroneously believe that inflation is a money supply problem when, in fact, it is a goods/services supply problem.
Traditionally, almost the only assets held by the Fed were US Treasury securities: loans to commercial banks were negligible, and the Fed did not lend at all to other institutions. All this has now completely changed.
The Fed’s equity cushion is now down to just 1.9% of its assets from 3.9% a year before.
The Fed’s equity cushion — the amount of losses the Fed could absorb without defaulting on debts — is infinite. Not 1.9%, not 3.8%, but infinite.
Ben Bernanke: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishes at essentially no cost.”
The Fed’s leverage ratio has gone up from just under 25 to about over 50 as the quality of its assets has markedly deteriorated.
As Lawrence H. White put it in a recent paper, “The Fed now looks increasingly like a very highly leveraged hedge fund” (White, 2008, p. 11).
The risk to the Fed is zero.Unlike a hedge fund, the Fed has infinite dollars. It can always “use the computer to mark up the size of the account.”
Amazingly, the author and others of similar ilk simply do not understand the basics of Monetary Sovereignty. The Fed cannot become insolvent.
The only alternative would be sterilizing the monetary base growth through (increased) reserve requirements.
This would, however, choke off the lending that the entire bank recapitalization exercise is intended to revitalize, and, as with selling off the recent Fed acquisitions, this would seriously counter the current stimulus measures.
Such a measure also has ominous historical overtones: the doubling of reserve requirements by the Fed in 1936-37 is commonly held to have been the principal factor behind the 1937-38 recession, itself deeper than any since World War II.
It is virtually inconceivable that the Bernanke Fed would risk a repeat of that debacle. Thus, sterilization would appear, to all intents and purposes, to be out of the question.
Aside from being totally unnecessary, this “sterilization” suggestion leads to another question: Why do banks have reserve requirements.Answer: To protect depositors from bank failures.
And that leads to the real question. Why do we have private banking? The federal government spends so much time, effort, and money to regulate the banks and to protect the public, that all banks are at least partially run by the regulators.
Suppose the Fed starts to print money to cover its losses. In that case, there is a real danger of a vicious cycle taking off in which monetizing the Fed’s losses leads to higher inflation, higher interest rates, more losses, and even more significant inflation.
That would be true if inflation were a money supply problem. But as we have seen, inflation is a goods/service supply problem, not a money supply problem.
Recent US experience is also consistent with the last false deflation scare when then-Governor Bernanke persuaded Alan Greenspan in 2002 that the US was (then also) in imminent danger of deflation.
The Fed responded by pulling interest rates down to about 1% and holding them at that level for a year.
The resulting expansionary monetary policy then fed an unprecedented roller coaster of a boom-bust cycle that ended in the collapse of stock and property markets, the specter of renewed inflation, the destruction of much of the financial system, and a sharp economic downturn.
I believe the author is talking about the 2008 recession, which was not caused by low-interest rates but rather by real estate speculation involving mortgage-backed securities and bad loans. The Fed failed to stop banks and other lenders from giving mortgages to people with bad credit risk.
Low-interest rates were not at fault. On the contrary, when the Fed raised rates, mortgage payments rose beyond borrowers’ ability to pay, so they defaulted. The rising rates precipitated the crash of real estate mortgages and other loans.
Does the Fed draw the lesson that aggressive monetary policy is ultimately destabilizing? Not at all. Instead, it embarks on an even more activist monetary policy that lays the seeds of an even bigger boom-bust cycle.
By “aggressive monetary policy,” the author means lowering interest rates. Also called “expansionary monetary policy.”
The Fed is thus repeating the same mistakes it made in the mid-90s and then again in the early years of the new millennium – but on a grander scale.
And, in the meantime, there is also that little matter of inflation in the pipeline to worry about …
The Fed’s mistakes are based on erroneous beliefs. The facts are:
Our Monetarily Sovereignfederal government and its agencies have unlimited spending money.
Treasury bonds, notes, and bills (i.e., federal “debt”) are not federal borrowing, The accounts remain the property of the depositors.
The Fed does not control inflation by raising interest rates. Higher rates exacerbate inflation.
Federal deficit spending does not cause inflation. Inflations are caused by critical goods and services shortages, usually oil and/or food. Federal deficit spending cures inflations when the spending cures the shortages that caused the inflation.
Ongoing economic growth requires ongoing increases in federal deficit spending.
Decreases in federal deficit spending lead to inflations and depressions.
Ongoing federal deficit spending is infinitely sustainable.
Economic growth is controlled by Congress and the President via federal spending, primarily via spending to eliminate shortages of critical goods and services. Raising interest rates is recessionary and does not control inflation.
Infinity is a big number. It’s so big you can’t even visualize it, much less count it.
The federal government has more dollars than there are atoms in the universe.
Infinity is bigger than all the atoms in all the molecules in all the dust grains in the entire universe, which is estimated to be 10^82 — that’s 1 with 82 zeros behind it — way bigger.
It’s bigger than a googol, which is 10^100, which is one followed by one hundred zeros. Infinity is bigger than a centillion, which is one followed by six hundred zeros, and bigger even than a googolplex, ten^googol.
I mention these staggering numbers, all of which are far smaller than infinity, to give you an idea of the U.S. federal government’s capability, which is this: The U.S. government can create infinite U.S. dollars any time it chooses, merely by deciding to do so.
Ben Bernanke, former Federal Reserve Chairman: “The U.S. government has a technology, called a printing press (or, today, its electronic equivalent), that allows it to produce as many U.S. dollars as it wishesat essentially no cost.”
Scott Pelley (60 Minutes): Is that tax money that the Fed is spending?Ben Bernanke: It’s not tax money… We simply use the computer to mark up the size of the account.
Statement from the St. Louis Fed:“As the sole manufacturer of dollars, whose debt is denominated in dollars, the U.S. government can never become insolvent, i.e., unable to pay its bills. In this sense, the government is not dependent on credit markets to remain operational.”
Given that infinite capability, the U.S. government cannot run short of dollars, no matter how many it spends, how little it taxes, or how big its deficits are.
Even if the federal government levied zero taxes, it could continue spending forever (the same as infinity, but on a time scale).
And what is true for the U.S. government also is true for any agency of the U.S. government.
The Army, Navy, Marines, Air Force, Space Force, the Senate, the House, the White House, the Supreme Court, Medicare, Social Security, and all the other 1000+ agencies of the federal government — none of them can run short of dollars unless that is the desire of the President and Congress.
So why do we concern ourselves with meaningless concepts such as federal deficits, debt, and borrowing when determining how much to spend on various projects? Why do we talk about “affordability” and “sustainability”?
Everything is affordable and sustainable for an entity with access to infinite (more than a googolplex) dollars, and there never is a reason to borrow.
With affordability, sustainability, and borrowing off the table, what criteria should the government use to plan expenditures?
Need and effectare the only criteria that have a purpose.
Take any federal agency, for instance, the House of Representatives: How much money does the House need to run most efficiently, and what are the overall effects of giving them that money?
Or think about America’s healthcare. How much money would a comprehensive, no-deductible Medicare plan covering every man, woman, and child in America need, and what would be the overall effect of providing that money?
The U.S. government can “afford” and “sustain” any numbers you can mention without either borrowing or taxing. Just press those computer keys Ben Bernanke mentioned.
Social Security for All: How much money is neededto eliminate poverty, hunger, homelessness, and most crime in America? Develop a number and press those computer keys.
Or education: How much money is needed to provide everyone with the education they desire, whether it be high school, college, advanced degree, or research facility?
There are no financial limitations. So, what are the limitations? Planning, know-how, and labor.
We need to know howto spend those unlimited dollars to achieve our goals, and we need enough educated labor to make it all happen.
Despite the bleating and moaning about deficits and debt, money truly is no object. We can do it all, and now, with AI (Artificial Intelligence), our capabilities have expanded massively. We really can create a paradise on earth.
Of course, when all objections have been satisfied, we come to the last refuge of the debt worriers: Inflation.
They tell you that if the government spends “too much,” we’ll have inflation.
That is what many people have been taught to believe, despite one small fact: Historically, there is no relationship between federal spending and inflation.In the massive inflation years of the late 1970s, federal spending ranged between $300 Billion and $700 Billion annually.
In the massive inflation years of the late 1970s, federal spending ranged between $300 Billion and $700 Billion annually.
In the 1980s, while inflation dropped to 2% and below, federal spending kept rising, reaching a high of $6 Trillion annually, still with low inflation.
Then suddenly came the COVID shortages, and just as suddenly, inflation rose to 8%+.
Now, as federal spending continues at massive levels and shortages decline, inflation, too is coming down.
The reason: Inflation, far from being a result of federal spending, is the result of national shortages, most often shortages of oil and/or food.
The famous Zimbabwe inflation was caused by a food shortage. The government took farmland from farmers and gave it to non-farmers. Government spending was an inept follow-up to the already existing inflation. Had the government spent to aid production and acquisition of food, there would have been no inflation.
Argentina: Food, clothing, and, surprisingly, energy shortages caused by the Russia/Ukraine war.
America: COVID-caused shortages of oil, food, shipping, computer parts, metals, lumber, labor, and other essentials. Before COVID, inflation was near zero despite massive federal spending for many years.
Then came COVID, and its shortages caused inflation to hit double digits.
SUMMARY
Congress, the media, and even economists worry about government spending when they should worry about private sector needs. That is the fundamental purpose of government — to provide the private sector with what the private sector needs.
Worrying about spending is a reasonable approach for households, businesses, and local governments, all monetarily non-sovereign. They do not have the infinite ability to create dollars. They can, and often do, run short of money. They require taxes and borrowing to remain solvent.
By contrast, this approach is wrongheaded for our Monetarily Sovereign federal government, which can create money and needs neither taxes nor borrowing to remain solvent.
As I write this, the federal government is about to shut down over worries, not about economic needs but about federal spending, the exact opposite of what the government should consider.
The Republicans have forgotten about needs. The Democrats consider needs but are hypnotized by the false analogies with household finances.
The situation today resembles a billionaire refusing a life-saving cancer medicine because it costs $1 per year. Nonsensical.
I look forward to the day when people understand that federal money is an unlimited resource. If used correctly, it will solve most problems facing this nation and create a paradise on earth.
Rodger Malcolm Mitchell
Monetary SovereigntyTwitter: @rodgermitchellSearch #monetarysovereigntyFacebook: Rodger Malcolm Mitchell
……………………………………………………………………..
The Sole Purpose of Government Is to Improve and Protect the Lives of the People.
 Another strange comment from the Fed: “Although food and energy make up an important part of the budget for most households–and policymakers ultimately seek to stabilize overall consumer prices–core inflation measures that leave out items with volatile prices can be useful in assessing inflation trends.”
Really? Look at this graph and see if you can see why so-called “core inflation” is useful.