What are the purposes of the student loan program?

What are the purposes of the student loan program?
A street made out of dollars leads to a school
The road to school is paved with dollars.

1. It provides financial assistance to students who may not be able to pay for their education upfront. 2. Educated individuals tend to have higher earning potential and contribute more to the economy. 3. Education provides individuals with critical thinking, problem-solving, and communication skills that are valuable in both personal and professional life. 4. Education can be a pathway out of poverty for many individuals, providing them with the tools and opportunities to improve their socioeconomic status. 5. Student loans provide a significant source of revenue for educational institutions, helping them maintain and improve their programs and facilities.

Federal student loans account for about 92% of the total outstanding student loan debt in the United States, while private student loans account for approximately 8%. Federal loan rates range from 6.5% to 9%, and private loan rates range from 3.5% to 17%. Approximately 40% of the loans provided by the government to help students pay for their education are delinquent or in default. The federal government collected approximately $4.92 trillion in tax revenue for the most recent fiscal year (FY 2024). According to the Federal Reserve, the student loan debt balance in the U.S. has increased by 66% over the past decade and now totals more than $1.74 trillion.
Washington Post, January 18, 2025, By Danielle Douglas-Gabriel In his last week in office, President Joe Biden capped a tumultuous effort to deliver widespread student loan forgiveness by canceling another $600 million in education debt for longtime borrowers and those defrauded by their colleges. With Biden’s final round of student debt relief, he has approved a total of $189 billion in loan cancellation for 5.3 million borrowers — more than any other president. Yet higher education experts are split on whether his mission to ease the debt burden for millions of Americans did more harm than good. Many of Biden’s sweeping debt relief policies have either been struck down by the courts or tied up in litigation that has left the student loan repayment system in disarray.
Ironically, the lawsuits and court cases depend on Republican obstruction, the party of the wealthy. Millions of people who would have benefited from debt relief voted for Trump. Now, more than ever, the wealthy have control over America. They always wish to be more prosperous, which requires widening the income/wealth/power Gap between the rich and the rest. The children of the rich do not need to borrow for college, but the children of the rest do. Therefore, forcing the rest to be indebted widens the Gap, making the rich richer. It’s the same motivation for why the rich complain about the cost of Medicare and Social Security but never about the costs of special tax breaks available only to the rich.
college graduates are higher than the poor
College graduates see a successful future
The “federal spending causes inflation” trope is how the rich justify voting against spending that benefits the not-rich.
Still, the president’s relentless pursuit of debt forgiveness, primarily through long-existing federal programs, has helped millions of people. “Four years ago, President Biden made a promise to fix a broken student loan system. We rolled up our sleeves and, together, we fixed existing programs that had failed to deliver the relief they promised,” Education Secretary Miguel Cardona said Thursday. The Education Department announced three separate rounds of student loan forgiveness in Biden’s last week in office. On Monday, the department canceled loans for 150,000 borrowers mostly through a 1994 statute called “borrower defense to repayment,” which lets the agency cancel federal student loans when colleges violate students’ rights and state law. A majority of those cancellations were for students who attended defunct schools owned by the Center for Excellence in Higher Education, including Stevens-Henager College, Independence University and California College San Diego. “My Administration has taken historic action to reduce the burden of student debt, hold bad actors accountable, and fight on behalf of students across the country,” Biden said Monday. “For the first time in the history of the student loan system, we saw the federal loan program deliver on its promise to more than 5 million student loan borrowers,” said Persis Yu, deputy executive director at the Student Borrower Protection Center (SBPC), an advocacy group. Conservatives have also succeeded in stalling Biden’s Saving on a Valuable Education (Save) repayment plan, which ties monthly student loan payments to earnings and family size, and offers a shorter path to loan forgiveness.  A court injunction has halted Save and the Education Department has suspended payments for the 8 million people enrolled in the plan but denied them credit toward loan forgiveness during the forbearance period. While President-elect Donald Trump is likely to end the program, it is unclear what his administration will do with all of those borrowers.  Republicans have become hardened against what many have called a fiscally irresponsible giveaway to college graduates at the expense of taxpayers.
To the Trump right-wing, “fiscally irresponsible” means anything that benefits the middle and the poor. It does not include tax breaks for the rich. Think of :
  • Private foundations or charitable trusts
  • Real estate depreciation deductions, tax-deferred exchanges (like 1031 exchanges)
  • Family limited partnerships (FLPs)
  • Offshore accounts and trusts
  • Business owners can deduct expenses, including travel, entertainment, and even personal use of company assets.
  • Grantor-retained annuity trusts (GRATs) and dynasty trusts
  • Carried interest
  • Deferred compensation plans
  • Foreign tax credits
  • Opportunity zone investments
  • Grantor trusts
  • Conservation easements
  • Like-kind Exchanges (Section 1031)
a doctor overworked overburdened drowning in patients
The future of the poorly educated.
Have you taken advantage of any of the above? They all reduce federal taxes, thus taking dollars from the federal government. If they were used by middle—and lower-income taxpayers, the rich would complain that they are “fiscally irresponsible giveaways” or that programs (like Medicare and Social Security) are running short of money. But you will hear no complaints from the rich about the abovementioned tax breaks. The rich complain only when the rest of us receive something from the government.
House Education and the Workforce Committee Chairman Tim Walberg (R-Michigan) accused the Biden administration of giving “handouts with zero accountability.”
“Handouts with zero accountability” is how Donald Trump paid virtually no taxes during the years he made billions.
“Instead, the administration should have been working to address the fact that student loan debt is too high, completion rates are too low, and far too many students are left worse off after paying for college than if they had never enrolled in the first place,” Walberg said Monday. “
Which is precisely what Biden’s loan forgiveness does.
It is shameful that, in its final days, the Biden-Harris administration is doubling down on efforts to push as much forgiveness as possible through the door, once again ignoring the rule of law.”
Neither Walbert nor the rest of the Republican Party has solutions for reducing excessive student loan debt, low completion rates, and the financial strains students face after college. In fact, as the techies say about flawed programs, “Those aren’t bugs; they’re features.”
Congressional Republicans are likely to push wholesale changes to the federal lending system through the budget reconciliation process, including a proposal to eliminate Plus loan programs for graduate students and parents. For his part, Trump has derided Biden’s student loan forgiveness policies as “vile,” but has not put forth a plan of his own.
This is a common complaint by Trump, who routinely criticizes anything the Democrats do, then promises to come up with a better plan and, in the end, fails to do so. Who could forget the eight years of broken promises to develop an “improved” version of Obamacare?
Persis Yu, the Deputy Executive Director and Managing Counsel at the Student Borrower Protection Center (SBPC) said, “The last Trump administration looked the other way when students’ and borrowers’ rights were denied — routinely siding with predatory schools and servicers. 
The fact that education benefits America was known to our first settlers,  whose first acts were to create schools. The first free public school in what is now the United States was established in 1635 in Boston, Massachusetts, funded by taxpayer dollars Today, grades K-12 are still funded by taxpayer dollars, without direct student cost, by monetarily non-sovereign governments. So surely, grades 13+ can be financed by our Monetarily Sovereign government without taxpayer dollars. These days, advanced education is more important than it was four centuries ago, so all the same reasons for free elementary and high school now exist for free college and advanced. The solution to educating everyone who wants it is federal funding of all education. Further, the federal government should fund student salaries to compensate for lost working hours. The “federal debt” excuse is meaningless for a Monetarily Sovereign government. The “inflation” excuse is false. Inflation is caused by shortages of oil, food, shipping, labor, etc., none of which is affected by federal spending on education. We seem to have plenty of money for the military, Congress, the White House, and SCOTUS, as well as tax breaks that benefit the rich. (There is no FICA for tax shelters.) Rich property and business owners receive massive tax breaks; renters and salaried employees get nothing. Trump famously stated, “I love the poorly educated.” It seems he is so enthusiastic about the poorly educated that he wants millions more to join that group. The federal government does not need to lend. Federal lending is a Mafia-like solution for students of modest means who are desperate to climb the social/financial ladder, but become trapped in future-destroying debt. The government should give benefits to the people rather than lend, which would not only help the individuals receiving benefits but, unlike lending, add growth dollars to the economy. We should end all student loan programs and start anew with comprehensive student support programs for grades K-16+, financed by the federal government at no cost to federal, state, or local taxpayers. “Comprehensive” should encompass tuition, books and materials, room and board, tutoring, transportation, and salaries to cover lost work time. This would decrease the number of poorly educated individuals, increase the number of well-educated individuals, and alleviate a significant financial burden on students, their families, and state or local governments. Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell; MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell; https://www.academia.edu/

……………………………………………………………………..

The Sole Purpose of Government Is to Improve and Protect the Lives of the People.

MONETARY SOVEREIGNTY
The solution to inflation: View inflation as a lack of supply problem, not an excessive demand problem

Background

Inflation is a general, progressive elevation in the prices of services and goods within the economy.

It is not an increase in one price or a dozen prices. It is a general increase in prices. And it is not a momentary price change; it is a progressive change taking place over months and years.

The U.S. government is Monetarily Sovereign. It has the unlimited ability to create U.S. dollars.

The Federal Reserve views inflation as an “excessive demand” problem, raising interest rates to combat it. The Fed’s theory is:

–Higher interest rates make borrowing more expensive for consumers and businesses. This tends to reduce spending on big-ticket items like houses and cars and can lead to decreased business investment.

–As interest rates rise, saving becomes more attractive. People may save more rather than spend, reducing overall economic demand.

–Higher interest rates reduce the overall demand for goods and services by curbing spending and borrowing. With lower demand, prices will stabilize or decrease, helping control inflation.

–The Fed aims to bring demand in line with supply by slowing down economic activity. This helps prevent the economy from overheating and keeps prices from rising too quickly.

–Higher interest rates can also influence inflation expectations. If businesses and consumers expect inflation to be controlled, it can become a self-fulfilling prophecy, helping stabilize prices.

Unfortunately, bringing down demand is recessionary. Also, when interest rates rise, businesses’ borrowing costs increase. This includes loans for expansion, equipment, and operational expenses.

Businesses facing higher borrowing costs may raise prices to maintain profit margins, potentially leading to higher consumer prices.

Historically, however, inflation has not been an excessive demand problem but a lack of supply problem.

business owner talks to customer
I’m sorry, ma’am. We could lower our prices if we didn’t have to pay such high interest rates on our business debt.

Rule #1. A price or prices can rise progressively only if there is a scarcity of crucial products or services- notably oil, food, and labor.

Prices cannot increase when products and services are plentiful.

Price increases would be temporary without scarcity as plentiful supply would naturally reduce prices.

For instance, it is believed that inflation can be caused by:

Expectations: If consumers or businesses expect prices to rise, they may temporarily increase their purchases or adjust their pricing.

However, without underlying scarcity, the market will self-correct.

Currency Devaluation: Devaluation can increase import costs, resulting in higher prices for imported goods.

However, if these goods are plentiful globally and alternative sources exist, the price increases may be reversed.

Devaluation is intended to boost exports, thereby injecting money into the economy. Contrarily, the supporters of devaluation often criticize government deficit spending for the same reason, as it also increases the money supply.

Increased Demand: Increasing demand typically indicates a healthy economy. If supply can match demand, prices will stabilize.

However, when supply falls short of demand, shortages lead to prolonged price increases.

Inflation occurs due to scarcity. Whether it involves oil, food, labor, or other essential inputs, this scarcity increases prices.

When there is no underlying scarcity, price increases due to expectations, devaluation, or demand growth will be temporary and self-correcting.

Rule #2. There is no “excessive demand”; instead, there is “inadequate supply.” Inflation always is supply-based, never demand-based.

Increased demand is an essential requirement for economic growth that should be encouraged rather than suppressed.

This perspective alters the understanding of demand-pull and cost-push inflation typically taught in economics classes.

Demand-pull inflation supposedly occurs when demand for goods and services exceeds supply, leading to higher prices. This should be viewed as inadequate supply, i.e., shortages, and cured by addressing the scarcity of goods and services, not the demand.

Cost-push inflation has been said to occur when rising production costs (e.g., wages and raw materials) lead businesses to increase prices, resulting in inflation. Production costs rise only when shortages, e.g., labor shortages push up wages, and raw material shortages push up purchase costs.

This inflation should be cured by addressing the shortages of labor and raw materials.

Rule #3. Recession is not an effective cure for inflation. Both recession and inflation can exist simultaneously (i.e., “stagflation”).

The two frequently attempted solutions for inflation—reducing federal spending and raising interest rates—are detrimental to growth and can lead to recession.

Leech - Wikipedia
Increasing interest rates to cure inflation is like applying leeches to cure anemia.

Reducing federal spending can worsen inflation by creating raw materials and labor shortages. Raising interest rates may also increase inflation by elevating business and consumer costs.

Rule # 4. To prevent/cure problems, cure the cause(s). Because inflation should be viewed as a supply problem, not a demand problem, curing supply constraints is the preferred approach to managing inflation.

This includes increased government investment in infrastructure, shipping, basic materials, innovation (R&D), and workforce development through education and training.

Encouraging demand and ensuring supply keeps pace supports sustainable economic growth and helps combat inflation without leading to a recession.

Summary: To prevent and cure inflation:

  1. Government policies should prioritize increasing supply through strategic investments rather than relying on monetary policy to reduce demand. Increasing demand is essential for economic growth.
  2. When inflation is related to oil shortages, the government should fund increased oil exploration, drilling, refining, and delivery, as well as increased funding for renewable energy creation and distribution.
  3. When inflation is related to food costs, the government should fund aid to farming, farm education, farm equipment, storage, and shipping.
  4. When inflation is related to increased labor costs, the government should fund education and training. It should also reduce labor costs by eliminating FICA and reducing business taxes.
  5. Other inflation-causing shortages should be addressed via federal support
  6. Discontinue efforts to reduce federal spending, the deficit, and the debt. So-called “excessive” federal spending does not cause inflation, and it can be part of the cure.
  7. Stop raising interest rates as a cure for inflation. Low rates do not cause inflation, and high rates increase the cost of goods and services—exactly the opposite approach to inflation prevention and cure.

A Monetarily Sovereign government should view inflation as a lack of supply problem, not an excessive demand problem, to prevent and cure inflation without a recession.

Cure the supply problem, and you cure inflation without a recession.

Rodger Malcolm Mitchell

Monetary Sovereignty

Twitter: @rodgermitchell

Search #monetarysovereignty

Facebook: Rodger Malcolm Mitchell;

MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell;

https://www.academia.edu/

……………………………………………………………………..

The Sole Purpose of Government Is to Improve and Protect the Lives of the People.

MONETARY SOVEREIGNTY


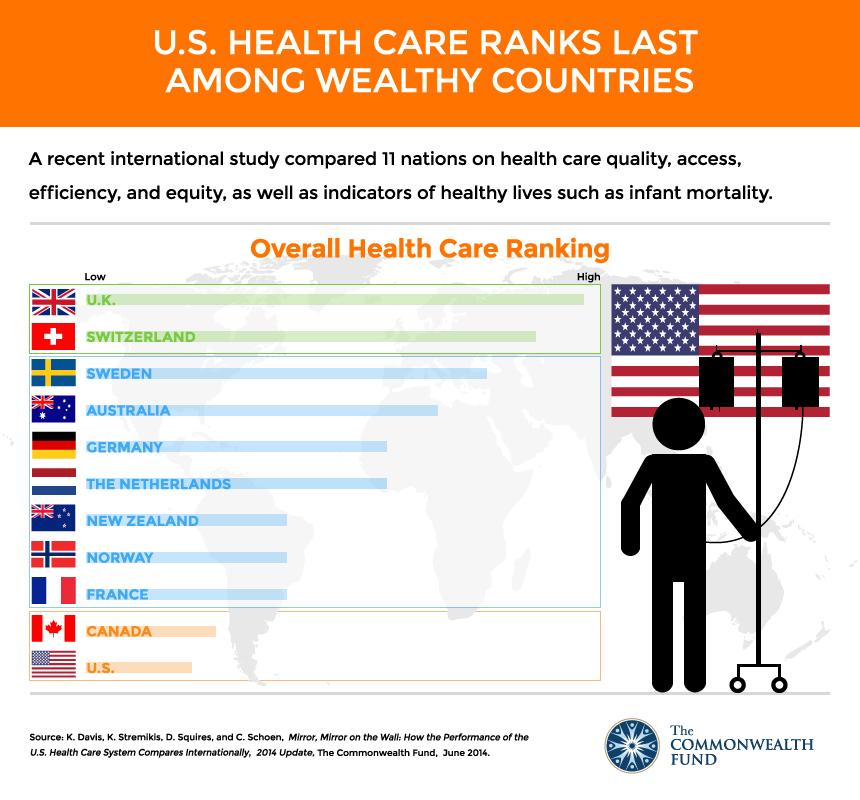
Why the U.S. has a shortage of doctors, and what can be done about it. The U.S. ranks last in healthcare.

If you are a regular reader of this blog, you know:
  1. The U.S. federal government is Monetarily Sovereign. It has the infinite ability to create its sovereign currency, the U.S. dollar. It never can run short of dollars.
  2. It can pay any financial obligation regardless of size, without levying taxes, merely by touching computer keys.
  3. Contrary to popular belief, federal spending is financed by creating new money rather than taxpayer funds. When federal taxes are collected, they are effectively destroyed. Federal “debt” does not represent a financial burden on the federal government or taxpayers.
  4. Federal spending does not cause inflation. Shortages of critical goods and services — usually food, water, and employees — cause inflation. Federal spending cures inflation when it addresses these shortages,
Please keep these facts in mind as we discuss excerpts from an article in the January-February edition of the AARP Bulletin:
By Howard Zucker*:
shortage of doctors
WHERE HAVE ALL THE DOCTORS GONE?
“How can I find a doctor who can help me?” As a physician, I get this question from friends and family all the time. And for most of my professional life, I was able to refer them to a medical colleague; a simple phone call was all it took to get someone an appointment within a reasonable amount of time. But no longer. The average wait for new patients to see a physician is 26 days, and that’s for mostly healthy people. In a medical emergency, the situation can become even more frightening: Twenty-two percent of acutely ill patients 65 or older who sought medical attention had to wait six days or more for an appointment, according to a 2021 survey by the Commonwealth Fund. This is a crisis. And it’s a crisis that’s getting worse, rapidly. “The backbone of our health care system, private practice, is on the brink of collapse,” warns Clarel Antoine, M.D., professor of obstetrics and gynecology at New York City’s NYU Grossman School of Medicine. “The nearly 70 million Americans on Medicare, many with chronic conditions, can expect longer waiting times for medical care. Although there were some 835,000 practicing doctors in America in 2023, according to the U.S. Bureau of Labor Statistics, we are currently experiencing a shortage because demand exceeds supply. The current shortage of physicians, combined with a number of other factors, has placed such an intense strain on doctors that many in the medical field are choosing to switch professions or simply retire early. And despite efforts by the Association of American Medical Colleges (AAMC) to graduate more doctors, those efforts simply can’t keep up with the drain. Why don’t we have enough doctors? In 1980, a U.S. government report concluded that American teaching hospitals were graduating too many medical students. It predicted a surplus of 70,000 physicians by 1990, an alarming statistic. In response, medical schools established what became a 25-year moratorium on increasing class size, enforced by the AAMC and the American Medical Association (AMA). Yet there was a significant flaw to that initial report: It failed to account for the nation’s rising population, which is now 110 million more than it was 45 years ago. By 2005, as the population grew and the potential for a severe physician shortage emerged, the AAMC and AMA reversed their recommendation, and in the past 20 years, more and more young people have trained to be doctors. Yet despite the more than 97,900 students in medical school, 38,000 in osteopathic school, and 162,000 doctors currently in residencies and fellowships, the AAMC predicts a shortage of up to 86,000 physicians by 2036. By then, it projects that the U.S. population will have risen 8.4 percent since 2021. The population of those over 65 will increase by 34 percent, while the number of people 75 and older will increase by 55 percent. “Medical education is a long journey, and even though medical school enrollment has risen, we need more residency positions [where med school graduates get hands-on training], which requires increased government support,” says David Skorton, M.D., president of the AAMC. It’s not just that we don’t have enough doctors. Part of the problem may be that we don’t have enough of the right kind of doctors. Becoming a doctor is expensive: The average medical student emerges with roughly $235,000 in debt.
There is no reason for this. Our Monetarily Sovereign federal government easily could fund medical school education for everyone who wanted one without collecting a penny in taxes.
Now consider that the average primary care physician (PCP) in internal medicine, geriatrics, pediatrics or family medicine makes about $250,000 to $275,000 a year.
Not nearly enough to pay off his/her loans.
Becoming a PCP just isn’t financially feasible for most recent graduates. Two-thirds of newly minted doctors are choosing to become specialists, which allows them to earn salaries upwards of twice what a primary care doctor can make. “Primary care physicians are undervalued by government and insurance companies, and that is reflected in decreased compensation,” says Isaac Opole, M.D., president of the American College of Physicians. “It makes the field unattractive to medical students.” Yet it is the PCP who provides the annual checkups that may detect problems early on, and who serves as the gatekeeper for referrals to specialists. Many people with private insurance, as well as those enrolled in Affordable Care Act plans, are required to see a PCP before they can access specialists in a majority of fields. And while many med students are choosing to go into specialty care, others opt not to become physicians at all. Indeed, more than 50 percent of medical students and residents surveyed preferred to pursue careers that do not involve direct patient care, such as research or teaching, according to a 2023 report from Elsevier Health. One in 4 contemplate dropping out of medical school altogether, citing overwork, financial stress and mental health concerns. In a study published in 2019, parts of chromosomes that shorten with age eroded six times faster than average for doctors in their first year of training after medical school; researchers attributed the accelerated aging to the doctors’ stress levels.
a doctor overworked overburdened drowning in patients
Your doctor has too many patients and not enough time.
Why your doctor doesn’t have time for you Many doctors dreamed of medicine as a profession from early childhood. In past generations, it was common to see physicians practicing long past the age when they could retire. Yet a recent AMA survey found that 1 in 5 doctors were hoping to find a way out of medicine in the next two years. Among those 55 or older, that figure was 1 in 2. Why? Part of what’s driving this is the growing trend of private equity firms and corporations, such as CVS Health and Amazon, purchasing hospitals and private practices. One major medical group, with about 90,000 doctors in some 2,000 locations across the country, has spent billions of dollars acquiring physician-owned practices, home health centers and surgical centers. This past April, the Physician Advocacy Institute reported that just shy of 80 percent of all doctors were employed by hospitals or corporations, up 200 percent in just over 10 years. Typically, when for-profit firms acquire practices, they approach these acquisitions utilizing a profit-based strategy. What does that look like? Corporate entities now govern doctors’ allotted time with patients, often allowing just 15 minutes per visit, a situation that isn’t healthy for either the doctor or the patient. “They control every aspect of a doctor’s professional life, and it’s all about the money,” one doctor told me. A 2024 JAMA Internal Medicine report said that 61 percent of doctors surveyed found private equity ownership unfavorable for health care. For every hour seeing patients, the average doctor now spends two hours doing administrative tasks, according to the AMA. A primary driver of paperwork: the electronic health record, or EHR.
doctor drowning
Your doctor is drowning in work.
“The EHR is the bane of existence for every doctor in the country,” says Opole. The EHR was designed to eliminate a paper-based tracking system and make patients’ health records easier for various health professionals to access. But in practice, doctors say, its primary focus is documenting for regulators and billing for insurers. To handle rising administrative demands, doctors have begun cutting back on office hours, resulting in even less time available to see patients. A 2023 Mayo Clinic study noted that 40 percent of doctors it surveyed intended to reduce their work hours in the coming 12 months.
The federal government could and should fund non-medical, administrative support help for doctors without collecting a penny in taxes.
“The doctor-patient relationship requires time to establish a trust, which comes with patients sharing stories of their life with you as it relates to their health,” John Dooley, M.D., an internist in private practice in Washington, D.C., shared with me one evening while driving home at 9:30 p.m. from a grueling day of work. “That doesn’t happen if you only give them 15 minutes.” Every physician told me they are burned out. Simply put, they are being asked by the business world that owns their practices to do medicine, at times, in ways they view as not in the patient’s best interest. Meanwhile, those who cling to their independent practices are finding it impossible to hold on given the financial pressures on them.
The government could pay doctors more. After all, one good doctor is worth more to America than a score of Elon Musks.
Yet another troubling trend: More than 300 doctors now die every year from suicide, a rate twice that of the general population. “We take highly intelligent people with a calling, put them in a demanding and often hostile work environment without any reasonable labor protections, and they cannot even meet their basic needs,” says Pam Wible, M.D., who runs suicide-prevention workshops for physicians. “They can find themselves on the path to taking their own life.” At a recent visit, my own primary care doctor, Paul Arias, M.D., shared that “the pandemic drove many doctors into retirement; others became ill and required disability and, sadly, some died. For those who remain, many fight daily with insurance companies to get approvals for a patient’s labs or procedure. It’s exhausting. Corporate America has taken over medicine.”
And yet, the Republican Party wants to privatize Medicare so that insurance companies can make more money and provide worse service.
To increase revenue, reduce paperwork and regain control of their lives, more and more doctors are choosing concierge medicine, a system in which patients pay a yearly out-of-pocket fee in exchange for longer visits and shorter wait times. Costs can range from $2,000 to $10,000 annually, though some practices have upfront prices that are markedly higher. And since most Americans don’t have the financial resources to pay such high and nonreimbursable fees, this further drains the pool of doctors available, especially to older people on fixed incomes.
massively crowded doctor's office
There were more of us, but they died waiting for an appointment.
I have a concierge doctor. My previous doctor served more than 2,500 patients. Wait times were long, but visits were short. My concierge doctor has about 500 patients. I can see her on a moment’s notice, and we spend at least a half-hour discussing my medical situation, often far more than a half-hour. She knows me far better than my previous doctor ever could. Concierge is the private sector’s solution to the federal government’s failure to do what it could easily do: Pay doctors more and pay for their non-medical assistance. It’s not a good solution, however, because if protects only those who can afford the service fee. It reminds me of the private sector’s poor solution to Medicare’s failure to fund everything medical: Medicare Advantage. This partially private-sector-funded program is famous for requiring advance notice of medical procedures, dramatically reducing the number of procedures authorized. Americans suffer needlessly when medical service is restricted by the ability to pay and the profit motive. It is disgraceful that America, which could afford the best medical care, has mediocre to poor care.
“There is a perfect storm coming,” says Bruce Scott, M.D., president of the AMA, “with increased patient complexity, decreased reimbursements and increased demand for prior authorizations from the insurance company. The combination of these makes it increasingly difficult for physicians to accept new patients and, in some cases, even keep their doors open. We can’t afford to lose even one more doctor.”
And now the real embarrassment: Advice on how to jump the line:
To ensure you get the care you need:
  1. Become friends with the nurses or schedulers in the doctor’s office. Learn their names and make sure they know yours. They can let you know if a cancellation has occurred and keep your name on a waiting list.
  2. Schedule your next appointment while you are at your current one. That’s your best shot at securing a spot on the calendar.
  3. Make sure to fill out all health forms online in advance of your visit. You may have only the smallest of windows to talk with a provider, so make sure you’ve provided as much information as possible to maximize your time in the doctor’s office.
  4. Ask about telehealth options. If the physician’s practice cannot see you in the office, speak with the scheduler to see if a telehealth visit is possible. In surveys, about 87 percent of doctors reported using telemedicine, but only 37 percent of adult patients had taken advantage of it within the previous 12 months, according to CDC data.
  5. Or ask if one of your doctor’s colleagues or another provider in the practice can see you.
  6. Ask your doctor for a referral — and to reach out on your behalf. If your doctor is retiring, moving or turning to concierge medicine, and following them is not an option, ask them for a referral. If they can recommend someone else in their group, even better — that comes with the advantage of your medical records being readily available.
  7. And always check to see if that new physician accepts your insurance, including Medicare.
  8. Ask your insurance company for a list of names of physicians. If you are on Medicare, go to Medicare.gov and click on the Providers & Services tab to find and compare doctors by location. You may want to consider a physician who is not geographically convenient to your home but who meets your other needs.
  9. Don’t be shy about going to urgent care or the ER if necessary. In many cases it’s better to get someone to look at you today than to wait weeks for your regular doctor.
  10. Monitor your health at home. Learn more about home care devices that can help to detect important changes in your health, such as a blood glucose monitor, pulse oximeter (to measure oxygen levels), blood pressure monitor, or electrocardiogram (ECG) to track heart rhythms. Calling a doctor’s office to report a change in a vital sign can speed up an appointment, give you some worthwhile reassurance — or urge you to get to an emergency room.
  11. Do some research. Use the internet wisely. Physician reviews may not be particularly helpful, as they are not only subjective but often filled with complaints; satisfied customers are less likely to post reviews. What is useful, however, are a physician’s board certification, specialty training, insurance plans and hospital affiliations. 
*Howard Zucker is board-certified in six medical specialties. He has served as U.S. deputy assistant secretary of health, New York State commissioner of health, assistant director-general of the World Health Organization, and as a deputy director at the Centers for Disease Control and Prevention.
Those eleven suggestions just “shuffle the deck. They do not improve overall care. Jumping the line doesn’t make the line shorter. America has become so wedded to the false notion that the private sector is always superior to the government we tend to forget some important points:
  1. Government workers are no different from private sector workers. Some are smart, hard workers;  some are not. As groups, they are the same
  2. The federal government has the infinite ability to risk money for unprofitable research and development.  Only the federal government could have funded putting a man on the moon, and it continues to fund work by private companies like SpaceX.
  3. Government spending adds to economic growth. The formula for Gross Domestic Product is: GDP=Federal Spending+Non-federal spending+Net Exports.
  4. The profit motive causes some of the worst aspects of America’s healthcare system, like unreasonable refusals to pay medical claims.
Sadly, our political leaders act as though federal money is limited. So currently, Millions of Americans suffer and die too early because Congress does not understand Monetary Sovereignty. Here is what a knowledgeable and caring Congress would do with the infinite dollars it has available to spend without levying taxes.
  1. Offer a free, comprehensive, no-deductible Medicare plan to every person in America, regardless of age or income. It would support every aspect of healthcare, including dental, eye, exercise, and personal training. There would no longer be different plans because one plan would cover everything.*
  2. Fund free education and training for everyone who wants to become a doctor or nurse.
  3. Fund research and development of medications and treatments for all diseases, including rare diseases that otherwise may be unprofitable for pharmaceutical companies.
  4. In exchange for federal support, pharmaceutical companies would receive limited patent protection on medicines.
  5. Federal support for doctors so that the concierge system no longer would be financially attractive.
*Currently, Medicare doesn’t cover:
    • Custodial Care: Long-term care services, such as nursing home care or home health aide services, are not covered.
    • Routine Physical Checkups: Regular physical exams and certain preventive services are covered, but routine checkups are not.
    • Dental Services
    • Eye Examinations and Eyeglasses
    • Hearing Aids and Examinations
    • Cosmetic Surgery: Procedures that are not medically necessary, such as cosmetic surgery, are not covered.
    • Chiropractor Services: Chiropractic care is generally not covered unless part of a treatment plan for a specific medical condition.
    • Certain Immunizations: Some immunizations are covered, but others, such as travel vaccines, are not.
    •  Hospital services exceeding Medicare length-of-stay limitations:
      • Days 1-60: Medicare covers the full approved amount after you’ve paid the deductible. For 2025, the deductible is $1,676.
      • Days 61-90: You pay a daily coinsurance of $419.
      • Hospital services exceeding Medicare length-of-stay limitations.
      • Days 91-150: These are called “lifetime reserve days,” and you pay a higher daily coinsurance of $838 per day. You have 60 lifetime reserve days that can be used during your lifetime.
      • After 150 days: You are responsible for all costs.
To see the dozens of medically related problems and procedures Medicare doesn’t cover, see here. Why doesn’t Medicare cover the above, especially when some are covered by Medicare Advantage and some private insurers? The answer: To save money. But Medicare, as a federal agency, doesn’t need to save money. It is funded by the federal government (not by FICA), which has infinite money. This is a clear example of our Monetarily Sovereign federal government pretending it is monetarily non-sovereign. SUMMARY Not only is the US short of doctors and nurses, but astoundingly:
U.S. ranks last in health care compared with nine other high-income countries, report finds. People in the U.S. die the youngest and experience the most avoidable deaths, despite spending much more on health care. The U.S. ranks as the worst performer among 10 developed nations in critical areas of health care, including preventing deaths, access (mainly because of high cost) and guaranteeing quality treatment for everyone, regardless of gender, income or geographic location, according to the report, published Thursday by The Commonwealth Fund, an independent research group.   The researchers looked at how the U.S. compared with nine other countries: Australia, Canada, France, Germany, the Netherlands, New Zealand, Sweden, Switzerland and the United Kingdom. Each country was graded on five categories: access to care, care process, administrative efficiency, equity and health outcomes.

The Trump administration’s solution to the problem is to fire as many government workers as possible (Elon Musk’s Department of Government Efficiency (DOGE)) to save the government money, not to save the public money or to improve health care for the populace.

  Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell; MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell; https://www.academia.edu/

……………………………………………………………………..

The Sole Purpose of Government Is to Improve and Protect the Lives of the People.

MONETARY SOVEREIGNTY
A puzzle perhaps you can solve

The puzzle is, can something be too simple to be believed? In the mid-19th century, Dr. Ignaz Semmelweis discovered that washing hands with a chlorinated lime solution could significantly reduce the incidence of puerperal fever (childbed fever) among women in maternity wards. Despite his compelling evidence and efforts to convince his colleagues, many doctors ridiculed him and refused to adopt his practices.
From Wikipedia: Ignaz Philipp Semmelweis was a Hungarian physician and scientist who was an early pioneer of antiseptic procedures and was described as the “savior of mothers.” Postpartum infection, also known as puerperal fever or childbed fever, consists of any bacterial infection of the reproductive tract following birth, and in the 19th century was common and often fatal. Semmelweis discovered that the incidence of infection could be drastically reduced by requiring healthcare workers in obstetrical clinics to disinfect their hands. In 1847, he proposed hand washing with chlorinated lime solutions at Vienna General Hospital’s First Obstetrical Clinic, where doctors’ wards had three times the mortality of midwives’ wards. The maternal mortality rate dropped from 18% to less than 2%, and he published a book of his findings, Etiology, Concept and Prophylaxis of Childbed Fever, in 1861. Despite his research, Semmelweis’s observations conflicted with the established scientific and medical opinions of the time, and his ideas were rejected by the medical community. He could offer no theoretical explanation for his findings of reduced mortality due to hand-washing, and some doctors were offended at the suggestion that they should wash their hands and mocked him for it. In 1865, the increasingly outspoken Semmelweis allegedly suffered a nervous breakdown and was committed to an asylum by his colleagues. In the asylum, he was beaten by the guards. He died 14 days later from a gangrenous wound on his right hand that may have been caused by the beating.
I hope I won’t be similarly confined because, for 25 years, I have struggled to explain what seems to me to be the simple concepts of Monetary Sovereignty. The question: Is Monetary Sovereignty so simple, so obvious, that you believe “it can’t be that easy‘? (It is.) Or, “if it were that simple, someone else would have thought of it.” (Others have.) Or, “that’s not what schools, economists, and the media teach.” (That’s the problem.) Here are three simple facts about our economy. 1. Money is not a physical thing. Gold, silver, and paper are not money, but they can represent money.
A dollar bill is a title to a dollar, not a dollar itself. All forms of money merely are bookkeeping entries. For example, a $10 gold coin is just a title to $10. The coin always is worth exactly $10 as money, though it may be worth thousands as barter. As money, that gold coin is worth neither more nor less than a $10 paper bill or the $10 on your checking account bank statement. Thus, money is just government-approved numbers on a statement. The U.S. government has the infinite ability to create these bookkeeping entries simply by pressing computer keys. 2. A government having the infinite ability to create, spend, and control a specific currency is sovereign over that money and it is called “Monetarily Sovereign.”  The governments of the U.S., Japan, the UK, Canada, and Australia are examples of Monetary Sovereignty over their respective currencies.

Alan Greenspan: “There is nothing to prevent the federal government from creating as much money as it wants and paying it to somebody.”

The governments of Italy, France, Germany, and Greece are monetarily non-sovereign. They do not have their own sovereign currencies. Instead, they use the euro, over which the European Union (EU) is sovereign. These nations can run short of euros, while the EU cannot. The nations rely on taxes; the EU needs no taxes. The Monetarily Sovereign U.S. government  cannot unintentionally run short of its money. Given a creditor’s demand for a million, or a billion, or a trillion trillion dollars, the U.S. government could pay immediately, without collecting a single penny in taxes. What does that tell you about federal debt? Just as the U.S, cannot unintentionally run short of dollars, the EU cannot run short of euros. Contrast with any monetarily non-sovereign entities — euro nations, businesses or people — which do not have the infinite ability to pay bills and can run short of whatever currency they are using. 3. Government spending of its Monetarily Sovereign currency is not inflationary. Historically, all inflation is supply-based — i.e, shortage(s) of critical assets, usually oil and/or food — not demand-based. While government spending can increase demand for specific products, this doesn’t cause inflation, which is an overall increase in the prices of almost all products.
These three fundamentals seem simple and straightforward. Yet, for perhaps 25 years, I have failed to help most people understand them. #1 confuses those who mistakenly believe the pieces of green-printed paper in their wallet are actual dollars, not just titles to dollars. #2 is vaguely understood except by all those who believe federal finances are the same as personal finances.. #3 is denied outright by those whose vision of supply and demand makes them believe excessive demand caused inflation rather than a lack of supply. To help people understand, I have given examples of the Monopoly game, which can be played without physical paper “money”—just a balance sheet—and that, by rule, the Bank (a corollary for the federal government) cannot run short of money. I have presented graphs demonstrating how inflations are closely related to oil costs, not to federal spending. I have presented graphs showing that recessions occur immediately after reductions in federal deficit spending growth and are cured by increased federal deficit spending growth. I have shown that every depression in U.S. history has come shortly after the federal government reduced deficit spending.

1804-1812: U. S. Federal Debt reduced 48%. Depression began 1807. 1817-1821: U. S. Federal Debt reduced 29%. Depression began 1819. 1823-1836: U. S. Federal Debt reduced 99%. Depression began 1837. 1852-1857: U. S. Federal Debt reduced 59%. Depression began 1857. 1867-1873: U. S. Federal Debt reduced 27%. Depression began 1873. 1880-1893: U. S. Federal Debt reduced 57%. Depression began 1893. 1920-1930: U. S. Federal Debt reduced 36%. Depression began 1929. 1997-2001: U. S. Federal Debt reduced 15%. Recession began 2001.

I have published articles by thought leaders from 1940 to today who falsely claimed that the federal debt is a ticking time bomb. During those 84 years, the debt grew from $40 billion to $30 trillion, yet this so-called “debt bomb” never exploded. I encounter articles daily discussing the dangers of federal debt and deficits. Currently, Congress is struggling with the absurd federal debt limit, which ignores the government’s unlimited capacity to meet its financial obligations. Even this morning, I read again about how federal agencies like Social Security and Medicare are in danger of running short of money, though Congress could supply all the funds needed just by voting. Every day, dollars are deducted unnecessarily from paychecks to “pay for ” some federal expense when, in fact, federal taxes pay for nothing. The federal government already has infinite dollars. Think. With infinite dollars, why would it need taxes? A simple question with a simple answer, yet most people are stumped by it

The sole purposes of federal taxes are:

1. To control the economy by taxing what the government wishes to discourage and by giving tax breaks to what the government wishes to reward and

2. To assure demand for the dollar by requiring taxes to be paid in dollars.

3. To help the rich become more affluent by providing tax breaks not available to the rest of us.

The wealthy promote the idea of “small government,” not because they genuinely believe the unfounded claim that “government is the problem,” but because they recognize that government establishes regulations they prefer to avoid. These regulations regarding clean air, clean water, food safety, and fair treatment by banks and businesses hinder the wealthy’s relentless pursuit of power and wealth, often at the expense of the rest of society. Most Congresspeople understand all these points but continue disseminating disinformation for political reasons. (Wealthy political donors pay a lower percentage of their incomes than the rest of us, so useless tax collections widen the Gap between the rich and us. The Gap makes them rich; we all would be the same without it.) Sadly, while the rich don’t want us to understand, most of us blindly follow their lead, just as the unfortunate pregnant women followed the fatal lead of mid-19th century doctors. Through the years, I have provided examples, data, and proofs. At the same time, again, some disingenuous Congressperson, deceptive economist, misleading writer, or uninformed friend assures you that Social Security and Medicare will become insolvent without tax increases or benefit cuts. Monetary Sovereignty is not complicated. It’s not, as they say, “rocket science.” It’s dead simple. However, I do not know how to help the populace understand what will benefit them. Consider the suggestion: “Eliminate FICA.” Is that too difficult to contemplate, or is it too easy to believe? What is the psychology of the millions who cannot accept the often-proven fact that the federal government has infinite money while accepting the never-proven nonsense that a Presidential election was stolen? Would you be outraged if your local car dealer tried to overcharge you or if your favorite football team refused to honor your tickets? Where is your passion against paying thousands of dollars in unnecessary taxes? Where is your anger about billionaire Trump paying far less taxes (almost nothing, actually) than you do? Why aren’t you frothing at the mouth about your doctor bills when the federal government could and should fund comprehensive, no-deductible Medicare for every man, woman, and child in America without collecting a penny in taxes? Why aren’t you screaming on the phone about proposed cuts to Social Security? If you heard about a billionaire who refuses to give his infant child enough money for medical care, would you be outraged? Well, the government is a multiple trillionaire, and you are its child. Get outraged. If I can’t convince people to make meager efforts to contact their Congresspeople about something that will save them many thousands of dollars and their health, improve their lives and their children’s lives, all at no cost, what is the purpose of reason? You’ve gone through the effort of reading this far. Why not make it meaningful? Call your Senator and Representative. Today. Now. “Why not” is the puzzle. Rodger Malcolm Mitchell Monetary Sovereignty Twitter: @rodgermitchell Search #monetarysovereignty Facebook: Rodger Malcolm Mitchell; MUCK RACK: https://muckrack.com/rodger-malcolm-mitchell; https://www.academia.edu/

……………………………………………………………………..

The Sole Purpose of Government Is to Improve and Protect the Lives of the People.

MONETARY SOVEREIGNTY